Vola: Cash Advance & Credit

- 2.05K Reviews
- 4.7
- Downloads
- 500.00K
- 3.4.15
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Quick access to cash advances for eligible users
- Simple application process completed entirely from a mobile device
- Transparent repayment dates shown before accepting an advance
- May help cover unexpected short-term expenses
- Credit-building features can support responsible financial habits
Cons
- Availability and terms may vary by state and user eligibility
- Advance limits may be modest for new or infrequent users
- Fees can make borrowing expensive compared with traditional credit
- Repayment is typically scheduled automatically from your bank account
- Late or failed repayments may lead to additional charges or account issues
Review of Vola: Cash Advance & Credit Appxis
When money is tight in a household, the problem is often less dramatic than an unpaid bill and more awkward: one person is waiting for payday, another is managing groceries, and everyone is trying to avoid dipping into savings. I tested Vola: Cash Advance & Credit with that kind of shared-household situation in mind. It is a finance app from Vola inc. that combines cash advances with budgeting and spending tracking, so its appeal is not limited to borrowing. The more useful question is whether it helps you coordinate a short-term gap without turning a shared device or shared budget into a source of confusion.
My overall impression is that Vola is most practical when one adult remains clearly responsible for the account and uses the app as a personal financial tool while discussing the broader plan with other household members. It is free to install, rated for Everyone, and has built a sizeable audience, with more than 500 thousand installs and a 4.7 average from roughly 11 thousand ratings. Those figures suggest that the idea is easy to understand, but ease of access should not be mistaken for effortless approval or a substitute for a proper emergency fund.
How Vola fits into a shared household
A realistic example would be a couple whose rent and utilities are covered, but whose checking balance is temporarily low because a paycheck arrives later than expected. One person could use Vola to review spending, look at the available cash-advance route, and decide whether a small bridge is sensible. The other person might not need access to the account at all; they may simply need a clear answer about what is available, what will be repaid, and which expenses should wait.
That distinction matters. Vola is not something I would treat as a household wallet where several people freely tap through the same profile. It is better understood as an individual account used within a household conversation. The app can help one person see the short-term picture, but it does not remove the need to agree on priorities. Before requesting money, I would compare the advance with the actual amount needed, identify the next income date, and leave room for fixed bills that are still pending.
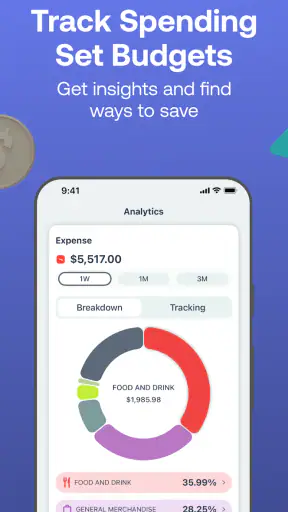
The spending tracker is particularly useful at this stage because a cash shortage can look larger than it really is. A quick review may reveal several small purchases, subscriptions, or delivery charges that are competing with the same balance. On the other hand, the tracker cannot make a household budget accurate if transactions are missing, delayed, or spread across accounts that are not being considered. I would use it as a decision aid, not as the only record of shared finances.
For a roommate arrangement, the boundaries are even more important. If one roommate pays the internet bill and another handles household supplies, Vola may help the account holder understand personal cash flow, but it does not automatically create a fair split. I would keep reimbursements and shared obligations written down separately. Borrowing through the app to cover someone else’s portion can quickly become a personal debt problem disguised as household cooperation.
What the first setup should accomplish
The initial setup should be approached slowly, especially on a device that other people use. I would create the account while logged out of other finance services, check every screen before confirming anything, and avoid saving access details where children, guests, or roommates can see them. A shared tablet is convenient for recipes and bills, but it is a poor place to leave a financial account open.
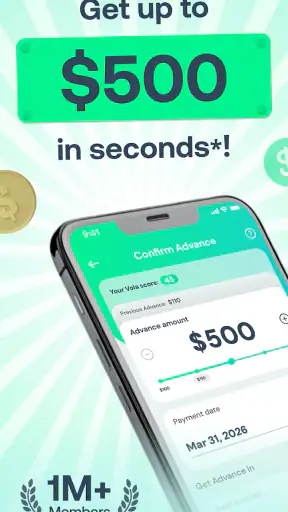
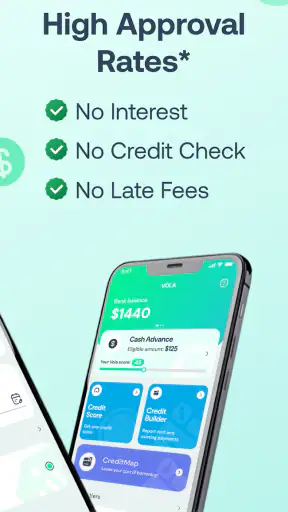
Vola’s central promise is access to an instant cash advance without a traditional credit check, alongside tools intended to help build credit, budget, and track spending. That combination can sound like three separate solutions, but they serve different purposes. The advance addresses timing. Budgeting addresses planning. Credit-related activity concerns longer-term financial history. I would not use the first benefit as proof that the other two will immediately repair a weak financial position.
Before relying on an advance, I would read the repayment information presented inside the app and make sure the expected repayment fits comfortably after the next deposit. The important test is not whether the money solves today’s problem; it is whether repayment creates a new problem a few days later. If the answer is uncertain, the safer choice may be to delay a discretionary purchase, ask a bill provider about timing, or use an established savings buffer instead.
The app is free to download, but “free” does not mean that every financial action has no cost or consequence. I would inspect the terms shown during the relevant process rather than assuming that installation tells me everything about borrowing. This is one of the areas where a quick tap-through can be expensive: the useful information is often the repayment obligation and eligibility conditions, not the download price.
Keeping account boundaries clear
Households often share phones, passwords, or email inboxes for convenience. That arrangement deserves extra care with a finance app. I would keep the Vola login separate from a child’s profile, avoid handing over an unlocked phone during a money conversation, and make sure notifications do not expose sensitive details on a lock screen. These are simple habits, but they matter more than any budgeting chart if several people can physically reach the device.
I would also avoid creating a second account for another household member simply to make coordination easier. Each person should understand whose identity and financial information are being used. If two adults need separate views, separate accounts and a shared conversation are cleaner than passing one login around. The app can be part of the discussion without becoming a communal credential.
For parents, the Everyone content rating is reassuring in the narrow sense that the app is not classified as mature entertainment, but it should not be interpreted as a recommendation for children to manage advances. Financial maturity is different from an age label. I would keep borrowing decisions with an adult who understands income, repayment, and the household’s other commitments. A teenager might learn from a supervised budget discussion, but I would not give unsupervised access to a borrowing account.
Using the tracker for coordination rather than surveillance
The spending tools are most helpful when they lead to a specific household decision. For example, I might review the last several days before grocery shopping, separate essential purchases from flexible ones, and set a realistic amount for the next trip. That workflow is more valuable than opening the tracker repeatedly without changing anything. The point is to turn visibility into an action: postpone, replace, reduce, or proceed.
There is also a trust issue. If one partner uses Vola to monitor personal spending, the app should not become a justification for policing every purchase. A shared budget works better when both people agree on which expenses need discussion and which remain personal. I would use the information to answer questions such as “Can we cover this bill before payday?” rather than “Why did you buy this?” The former supports coordination; the latter can damage it.
Another practical limitation is that a household may have money spread across multiple banks, cards, and cash transactions. A spending view can be incomplete if the family treats it as a full accounting system while leaving other activity outside the workflow. I would reconcile the app’s picture with bank statements and upcoming bills before making a borrowing decision. This extra step takes a few minutes and prevents a misleading sense of precision.
Vola can also be useful for a person who lives alone but shares a device with a partner, parent, or child. In that case, the main benefit is not collaboration inside the app. It is the ability to keep personal financial information separate while still discussing a household plan verbally. I found that distinction healthier than trying to force every money detail into one shared screen.
Where it differs from ordinary alternatives
A conventional bank app is usually the better place to see official balances, scheduled payments, and account history. A spreadsheet may be better for a couple who wants a fully customized household budget with categories, reimbursement notes, and long-term goals. A savings account is better than any advance when it can cover the gap without creating another repayment obligation. Vola’s advantage is convenience: it brings short-term access and financial organization into one focused experience.
That convenience has a trade-off. A bank app reflects the accounts it actually controls, while Vola’s budgeting view is useful only when the information available to it matches the way you spend. A spreadsheet offers complete control but demands discipline. Vola is easier to start with, yet its simplicity may encourage a user to skip the deeper review that a serious household budget requires.
I would choose Vola over a basic budgeting app when the immediate issue is timing and I also want a quick look at spending behavior. I would choose a bank’s tools when security, account accuracy, and bill management are the priorities. I would choose neither as a first response if the household is already borrowing repeatedly to cover ordinary expenses. In that situation, the problem is structural, and another advance may only postpone the difficult conversation.
Credit-building expectations need patience
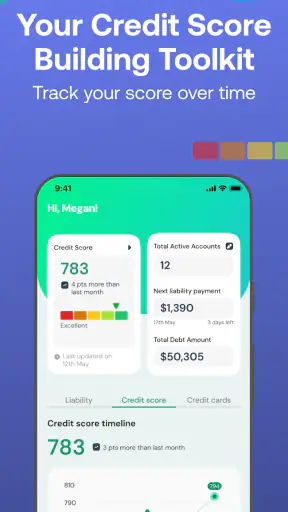
The credit-building angle deserves a realistic interpretation. Improving credit is not the same as receiving cash quickly, and it should not be treated as an automatic result of installing a finance app. I would read the in-app explanation carefully, understand which actions matter, and avoid borrowing solely because credit improvement sounds attractive.
This is especially important in a shared household. One person’s credit profile belongs to that person, even when the money supports rent or groceries for everyone. Partners should discuss the impact before using an individual account for a joint expense. If repayment is missed, the consequences may not be shared evenly, so the person whose account is involved needs a clear plan and final say.
For someone with stable income and an occasional timing mismatch, that distinction may make Vola worthwhile. For someone without dependable income, the app should be approached much more cautiously. A cash advance can smooth a predictable gap, but it cannot create income. If the next payday is uncertain, I would prioritize free advice, creditor communication, and a full budget review instead of relying on repeated advances.
Everyday friction I would plan around
The biggest friction is psychological: instant access can make a temporary shortage feel solved before the repayment has been considered. I would never request an advance while distracted, rushed, or in the middle of an argument about money. A better routine is to write down the exact expense, the next expected income, and the balance that must remain untouched. Then I would open the app and compare that plan with what it shows.
Another limitation is that app-based financial tools depend on accurate personal information and a functioning phone. A shared device can introduce practical problems if someone logs out, changes settings, or clears notifications. I would keep important repayment dates in a separate calendar and retain official records rather than relying on memory or a single screen.
Updates can also change how an app feels over time. Vola’s current version is 3.4.15, and it supports devices running Android 9 or later. That makes compatibility worth checking before installation on an older phone. I would update through the normal app store, review permissions when prompted, and avoid using an outdated device for sensitive financial tasks if it no longer receives security updates.
The developer is Vola inc., and the app has been available since January 23, 2019. Its continued presence and strong user response make it easier to take seriously than an unknown finance tool, but popularity is not a personal guarantee. I would still judge it by whether the repayment plan works for my household, not by how many other people have downloaded it or left ratings.
Who should use it, and who should skip it
I think Vola is a good fit for an adult who has a definable short-term cash gap, wants a clearer view of spending, and is willing to read the borrowing details before accepting anything. It can also suit a household where one person manages the financial account while both adults agree on a simple plan for bills, groceries, and repayment.
I would skip it if the main need is joint bookkeeping, detailed bill splitting, investment management, or a complete replacement for a bank account. I would also avoid making it part of a child’s unsupervised money routine, or using it to conceal spending from a partner. Those situations call for stronger account separation, a shared spreadsheet, a bank tool, or a direct household discussion.
It is not the right choice for someone who expects an advance to solve an ongoing deficit. If every pay cycle begins with a new shortage, the app’s convenience may make the pattern harder to notice. In that case, the budgeting view could still help diagnose spending, but I would use it as a temporary measurement tool rather than a recurring source of borrowed cash.
My household verdict
After using Vola with shared-device and shared-budget concerns in mind, I see it as a focused personal finance companion rather than a family finance hub. Its strongest combination is the ability to examine spending while considering a short-term advance in the same place. That can be genuinely helpful when the gap is specific, the next income is reliable, and the account holder remains in control.
The best household workflow is straightforward: keep the account private, discuss the expense openly, verify the repayment plan, and use the tracker to change behavior rather than merely observe it. I would keep children and casual device users away from the account, and I would never confuse an Everyone rating with permission for unsupervised borrowing.
My recommendation is therefore conditional but positive. If you need a free finance app that brings cash-flow awareness and an advance option together, Vola is worth examining. Use it deliberately, compare it with your bank and savings alternatives, and treat the borrowing feature as a bridge rather than extra income. With those boundaries, Vola: Cash Advance & Credit can support a practical household plan without pretending to replace one.
FAQ
What is Vola: Cash Advance & Credit, and how does it work?
Vola is a financial app designed to help eligible users access cash advances and monitor aspects of their personal finances. After creating an account, you may be asked to connect a bank account and provide information used to determine eligibility. If approved, the available advance, repayment terms, fees, and delivery speed can vary depending on your profile and the current conditions shown in the app.
Who can use Vola, and what information is required to apply?
Availability depends on factors such as your location, age, identity, income activity, and the type of bank account you use. During registration, Vola may request personal details, identity verification information, and permission to review account data through a supported financial connection. Meeting the basic requirements does not guarantee approval, because eligibility and advance limits are determined individually.
How much does Vola cost, and are there any additional fees?
Before accepting an advance, carefully review the complete cost displayed in the app. Depending on the product and your membership or account status, charges may include subscription costs, optional expedited-transfer fees, or other disclosed service fees. The exact amount can change, so do not rely on general examples. Confirm the repayment amount, renewal terms, and cancellation policy before proceeding.
How quickly will I receive money, and how is repayment handled?
The delivery time depends on the transfer method, your bank, verification status, weekends, and whether you choose a faster option. Standard transfers may take longer than expedited delivery. Repayment is generally scheduled according to the advance agreement and may be collected from a linked account or another method available in the app. Check the exact due date and payment authorization before accepting.
Is Vola safe to use, and what should I know about privacy?
Vola may require access to financial information so it can verify eligibility, analyze account activity, and provide its services. Before connecting an account, read the privacy policy, consent screens, and permissions carefully. Use the official app store listing, protect your login credentials, and review connected accounts regularly. A cash advance is still a financial obligation, so consider whether repayment could affect your budget.


