

Google Wallet
Google LLCFinance
Scanned and Safe · Free
- Rating
- 4.4Out of 5
- Downloads
- 1.00B
- Android
- 9
Screenshots
Analysis by Appxis
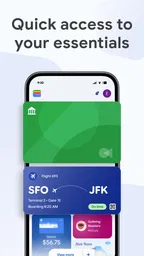
I find the most useful way to think about Google Wallet is as a shortcut for carrying and presenting everyday payment cards and other digital items from a phone. That sounds simple, but the difference shows up in small routines: paying without taking out a physical card, or keeping a ticket close at hand instead of searching through a bag. It is a finance app from Google LLC, and its appeal is less about managing a budget than making selected everyday essentials easier to access.
What the phone-based wallet changes
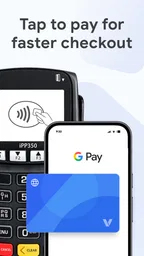
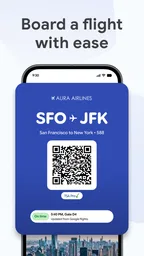
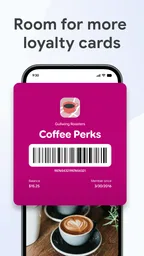
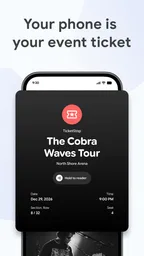
A digital wallet can reduce the number of things I need to carry, but it does not make every payment situation identical. At a compatible contactless terminal, paying with a phone can be quicker than finding a card and putting it away again. For tickets or passes, having them available on the device can also make the handoff at an entrance less fiddly. The practical benefit is ready access when I need to present something, not a replacement for every card or document I own.
That distinction matters when deciding whether to rely on it. I would still keep a physical payment option available for places where phone payments are not accepted, and I would check that the particular card or item I want to use can be added. A digital wallet is most convincing when it fits the places I already go; it is less helpful if I have to change my routine around it.
Coverage of Google Wallet
Getting started and keeping it useful
Google Wallet is free, rated for Everyone, and has been available since June 24, 2011. The app requires Android 9 or later. Google’s large reach is reflected in over one billion installs and an average rating of 4.4 from around 2.2 million ratings, with roughly 121,000 written reviews. Those figures suggest that it is a familiar choice, though popularity alone cannot tell me whether it fits a particular bank, phone, or travel routine.
When setting it up, I would begin with the card or pass I expect to use most, then test the workflow before depending on it for a time-sensitive trip. That small rehearsal is more useful than adding everything at once: it confirms that the item is available where I expect it and that I know how to bring it up quickly. I would also avoid treating the app as an archive for every piece of information I might need. Keeping the wallet focused on frequently used items makes it easier to scan when I am in a queue.
Because this is a phone-based tool, the device itself becomes part of the payment routine. A low battery, a locked-out account, or simply leaving the phone at home can turn a convenient shortcut into an inconvenience. My practical approach would be to keep a backup payment method for essential errands, especially when travelling or when I know I will be away from a charger for a long time.
A payment routine in the real world
Picture a normal weekday: I stop for coffee on the way to work, then pick up a few groceries later. If both counters accept contactless phone payments and my chosen card is ready in the wallet, I can pay without opening a physical wallet at each stop. The gain is modest at any one checkout, but it adds up as fewer little pauses and less rummaging. For a ticket or pass, the same idea is useful when I need to show it at an entrance: keeping it on the phone can be faster than finding a paper copy in a crowded bag.
More Stories While You Read
I would still prepare before reaching the counter. Having the phone accessible and knowing which card or pass I intend to use prevents the awkward moment of holding up a line while I search. If I carry multiple payment cards, choosing a default or otherwise learning the selection flow ahead of time can make the experience more predictable. That is a small habit, but it is the sort of detail that decides whether a mobile wallet feels genuinely effortless or merely different.
How it compares with carrying cards
Compared with a traditional wallet, the main advantage is convenience: a phone can consolidate some items I would otherwise carry separately. Compared with a bank’s own payment app, Google Wallet may be appealing if I want a central place for supported cards and passes rather than opening a separate app for each provider. But a bank app can be the better fit if I mainly want account-specific tools or prefer to keep payment activity inside that bank’s own environment.
It is also not the same thing as a budgeting app. I would not choose it to categorize spending, set savings targets, or get a broad picture of household finances; its role is handling access to payment methods and other wallet items. That narrower purpose is a strength when I want a straightforward checkout tool, but a limitation if I expect one finance app to manage my money from end to end.
Acceptance is another real-world trade-off. Contactless payment depends on the terminal and the card or service involved, so I would not assume a phone will work at every shop, kiosk, or travel point. A physical card remains useful as a fallback, and a paper ticket may still be sensible if a particular venue or journey has its own requirements. I see the app as a convenient option alongside familiar methods, rather than a reason to discard them.
Using Google Wallet with fewer surprises
I approach mobile payments with a little preparation rather than assuming every checkout will go smoothly. Before relying on Google Wallet for a busy day, I’d confirm that my chosen card or pass is ready and keep a physical backup for places where phone payments are not accepted. That simple routine makes the convenience more dependable and sets up the next question: how to handle the phone and account thoughtfully.
Security and sensible backup habits
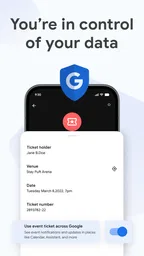
Security is part of the decision, not a detail to think about only after adding a card. I would protect access to the phone with a lock method I actually use and make sure I know what steps are available if the device goes missing. The original experience I describe here includes encryption, passcode protection, and the ability to remotely lock or erase wallet data. Those safeguards are reassuring, but no digital tool removes the need to look after the device and account that give access to it.
For everyday peace of mind, I would avoid leaving a phone unattended after using it to pay and would keep a backup card in a separate place when the stakes are higher, such as a long day out. If the phone is lost, being able to act remotely is valuable; it is still wise to know how to reach that control before an emergency. A quick check of account recovery and device-lock settings is more practical than assuming I will remember every step under pressure.
What to expect from integration and offers
The app can fit naturally into a Google-centered routine, and the published experience describes integration with other Google services and third-party apps. That can reduce switching when a supported purchase or payment is already part of a digital flow. Compatibility is not universal, though: the relevant bank, issuer, merchant, or service must support the item I want to use. I would check my own card and the places I visit rather than taking broad compatibility as a guarantee.
Offers can be a welcome extra, but I would treat them as occasional rather than as a reason to spend. A discount only helps if it applies to something I planned to buy and its terms suit the purchase. I would look at the details before counting on a reward, and I would not assume every user will see the same promotion. The core value for me is quick access to useful items; any offer is a bonus, not the point of installing the app.
Who will benefit, and who may prefer another option
I think this is a strong fit for someone who already carries an Android phone, uses contactless terminals regularly, and wants fewer physical cards or loose passes in daily circulation. It can also suit commuters and frequent errand-runners who value having a payment method close at hand. The clearest benefit comes to people whose banks and commonly visited merchants support the setup they need.
I would hesitate to recommend relying on it as a sole payment method to someone who often visits places with limited contactless acceptance, dislikes using a phone at checkout, or wants detailed financial tracking. In those cases, a physical card, a bank’s own app, or a dedicated budgeting tool may be a better companion. The right choice depends less on how modern a payment method feels and more on whether it works reliably in the reader’s own routine.
Getting Started with Google Wallet
Setting up Google Wallet is a breeze. All you need is a Google account, and you're halfway there. I found the user interface to be intuitive and welcoming, even for those who might not be tech-savvy. Once logged in, simply add your debit or credit card details, and voilà, you’re ready to start making payments with just your smartphone.
Seamless Transactions
One of the first things I noticed was how seamless the transactions are. Whether you're paying at a grocery store, a coffee shop, or even online, just a tap or a few clicks gets the job done. It's like having a magical wallet that works with just about any payment terminal that supports NFC. I particularly enjoyed the contactless payment feature, especially during these times when minimizing contact is a priority.
Security Features
Now, I know what you're thinking: "Is it safe?" Let me tell you, Google Wallet takes security seriously. With encryption and passcode protection, you can rest easy knowing your card details are safe. Plus, if you ever lose your phone, you can remotely lock or erase your Google Wallet data. It’s a reassuring layer of security that gives peace of mind.
Integration and Compatibility
I was impressed by how well Google Wallet integrates with other Google services and third-party apps. Whether it’s splitting a bill with Google Pay Send, buying apps on the Play Store, or even making in-app purchases, it’s all incredibly smooth. The app is also compatible with a vast array of banks and card issuers, making it accessible to a wide audience.
Rewards and Offers
Who doesn’t love a good deal? Google Wallet occasionally offers cashback and discounts with certain merchants, which was a pleasant surprise. It’s not only convenient but also rewarding to use. Keep an eye out for these offers in the app to make the most out of your spending.
Final Thoughts
After using Google Wallet for a while, I can confidently say it has streamlined my payment process. Whether it’s the ease of setup, the security features, or the seamless integration with other services, it’s clear that Google has crafted a solid digital wallet experience. If you’re looking to make your payment process more futuristic and less bulky, give Google Wallet a try. It might just change the way you handle your finances.
Pros
- Seamless integration with Android devices
- Supports multiple payment methods
- Easy to track spending and transactions
- High level of security and encryption
- User-friendly and intuitive interface
Cons
- Limited availability in some regions
- Requires internet connection for many features
- Not all banks are supported
- Occasional app glitches reported
- No reward system like some competitors
Google Wallet FAQ
What is Google Wallet, and how does it work?
Google Wallet is a digital payment platform that allows users to make online transactions, send money to friends and family, and store various payment methods, such as credit cards, debit cards, and bank accounts, securely in one place. It works by linking your payment details to your Google account, enabling easy and quick transactions across various platforms and services.
Is Google Wallet safe to use for online transactions?
Yes, Google Wallet is designed with several layers of security to protect your financial information. It uses encryption and robust authentication processes to ensure that your details are secure. Additionally, users can employ features like two-factor authentication to add an extra layer of security. Google continuously updates its security measures to address any potential threats.
Can I use Google Wallet internationally?
Google Wallet can be used in many countries; however, its availability and the features offered can vary depending on your location. Before using it internationally, it’s advisable to check Google’s official website or app guidelines to understand what services are available in your destination country. Some countries may have restrictions on specific payment methods or services.
What devices are compatible with Google Wallet?
Google Wallet is compatible with most Android and iOS devices. However, for the best experience, it is recommended to use a device with the latest operating system updates. Some features may require NFC (Near Field Communication) support, so check if your device has this capability if you plan on using contactless payment options.
How do I set up Google Wallet on my device?
Setting up Google Wallet is straightforward. First, download the Google Wallet app from the Google Play Store or Apple App Store. Open the app and sign in with your Google account. Follow the on-screen instructions to add your payment methods and set up any security features, such as PIN or biometric authentication, to protect your account. Once set up, you can start using it for transactions.
Read This Page in Another Language
Other Picks in This Category

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5
More Finance Reviews

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5

Trust: Crypto & Bitcoin Wallet
DApps Platform, Inc. 4.5 Out of 5
About This Listing
- Developer
- Google LLC
- Package Name
- com.google.android.apps.walletnfcrel
- Version
- Varies with Device
- Android
- 9
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at google-payments@google.com, visit https://pay.google.com/about, or view the https://policies.google.com/privacy.