

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia KoeFinance
Scanned and Safe · Free
- Rating
- 4.5Out of 5
- Downloads
- 100.00M
- Android
- 5.1
Screenshots
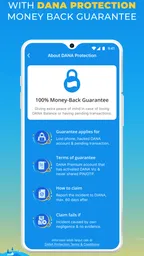
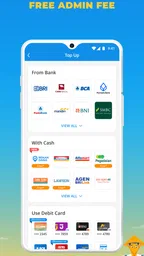
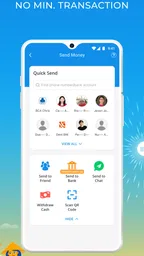
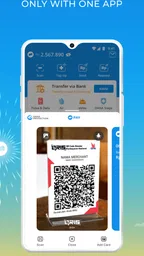
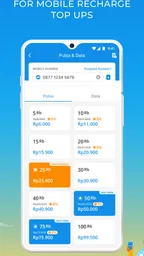
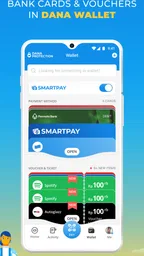
Analysis by Appxis
I judge a digital wallet less by how polished it looks than by what happens at the exact moment I need to pay: whether I can get a clear balance, find the right option, and finish without second-guessing a tap. That makes connectivity part of the experience, not a background detail. DANA Indonesia Digital Wallet is a finance app from PT Espay Debit Indonesia Koe, and I find it most useful when I treat it as a convenient way to manage cashless errands while keeping a backup payment method close.
When a payment depends on a good connection
A wallet is only as reassuring as its response during a transaction. If I am paying at a busy counter, I want enough time to open the app, check what I am confirming, and wait for a clear result before moving on. A weak or interrupted connection can make that sequence feel uncertain, especially if the screen does not immediately show whether a payment completed. I avoid tapping repeatedly in that situation; checking the transaction history or waiting for the app to settle is safer than accidentally starting the same action again.
This is a practical difference from carrying cash. Cash does not need a network, while a digital wallet can be convenient only when the phone and service can communicate. I would not make DANA my sole option for a time-sensitive purchase in a place where reception is unreliable. For routine errands in connected settings, though, being able to keep payment tasks on my phone is a useful trade-off.
Coverage of DANA Indonesia Digital Wallet
Useful in the small gaps of a busy day
The app makes the most sense in everyday moments when I already have my phone in hand: paying a bill at home, sending money to someone I know, or completing a merchant payment without counting out cash. A realistic routine might be checking a bill during a lunch break, making the payment while the connection is stable, then looking at the transaction record before closing the app. That last check is a small habit, but it helps me catch uncertainty while I still remember what I was doing.
For shared expenses, I would use a deliberate workflow: confirm the recipient before sending, check the amount, and keep the confirmation screen or transaction record available until the other person has verified receipt. The convenience of a quick transfer is not a reason to skip those checks. If someone is waiting beside me, I would rather take a few extra seconds to verify the details than rely on memory after a hurried tap.
Recovery, caution, and a sensible backup
Connectivity interruptions and everyday mistakes call for different responses. If an action appears to stall, I would first avoid repeating it immediately, then check whether the app shows a completed transaction. If the status remains unclear, pausing and checking again once the connection is steady is more sensible than guessing. This is especially important for payments, where a second attempt can create confusion even if it eventually turns out the first one worked.
I also recommend keeping a backup payment option for situations where the phone battery is low, reception is poor, or a transaction needs to happen faster than troubleshooting allows. That does not make a wallet less useful; it is simply good planning. People who need every payment method to work without relying on a phone or network may be happier carrying cash or using a physical card as their primary choice.
More Stories While You Read
Using a wallet without wasting mobile data
If I am trying to be careful with mobile data, I reserve app checks for a purpose rather than repeatedly reopening the wallet to browse. I can decide what I need first—pay a bill, send money, or review a transaction—then open the app when I have a usable connection and complete that task in one focused session. This is a modest habit, not a claim that the app has a special low-data mode.
It also helps to avoid doing a financial task while distracted by a patchy signal. Waiting until I am somewhere with a steadier connection can reduce uncertainty and prevent multiple checks. For anyone managing a tight data allowance, the sensible question is not just how often an app connects, but whether each session has a clear purpose. DANA works best for me when I use it deliberately rather than treating it as something to keep refreshing.
A Convenient Way to Pay
First off, let me just say that setting up DANA was a breeze. Within minutes, I was up and running, ready to make my first transaction. It’s designed with user-friendliness in mind, which is perfect whether you’re tech-savvy or a novice in the digital space. From paying bills to transferring money to friends and family, DANA does it all with a few taps. I especially appreciated the seamless integration with various merchants, making everyday transactions more straightforward than ever.
Security Features That Matter
Now, I know what you’re thinking—how secure is this app? Well, DANA has put a lot of thought into security features. It uses encryption, and there are multiple layers of authentication to ensure your money is safe. These include PINs, fingerprint scanning, and facial recognition. Knowing that my transactions and data are secure gives me peace of mind, which is crucial in today’s digital age.
That reassurance should sit alongside good personal habits. I still check the recipient and amount before confirming a transfer, keep my phone protected, and avoid rushing through payment screens when somebody is waiting. Authentication can help guard access, but it does not replace careful review of the details I am about to approve. If I share a device or regularly hand my phone to someone else, I would be especially cautious about how it is secured.
Rewards and Promotions
Who doesn’t love a good deal? With DANA, you’re often greeted with a slew of promotions and rewards. Whether it’s a cashback offer or discounts at your favorite stores, there’s always something to keep an eye out for. This not only adds value to the app but also makes spending a tad more rewarding. I found myself eagerly checking the promotions section to see what’s new and exciting.
I treat a promotion as a bonus, not as a reason to spend. Before relying on an offer, I would read its conditions in the app and check that it applies to the purchase I already planned to make. That keeps the wallet useful even when no deal suits me, and it avoids letting a limited-time incentive dictate an unnecessary shopping choice. Someone who dislikes browsing offers can simply focus on the payment and transfer tasks that matter to them.
User Experience and Interface
The user interface is sleek and modern, with a clean design that makes navigation a breeze. Everything is laid out intuitively, which means you spend less time figuring things out and more time enjoying the benefits. The app is responsive, and transactions are processed swiftly, which is fantastic when you're in a rush.
In my experience, the best way to keep that apparent simplicity useful is to slow down at the confirmation step. Familiar screens can encourage muscle memory, and that is exactly when a wrong recipient or amount can slip past. I review the details before completing a payment, then look for the resulting transaction record rather than assuming a quick animation alone settles the matter.
Who will get the most from it
DANA is a strong fit for someone in Indonesia who wants common money tasks in one phone-based routine: paying bills, sending money to friends or family, and paying participating merchants. It is especially practical if the people and businesses I deal with already accept the wallet, because that makes the convenience tangible instead of theoretical. The app is free, rated for Everyone, and its broad adoption—over 100 million installs—suggests it is familiar to a large audience, though popularity by itself cannot tell me whether every merchant I use will accept it.
It is less compelling as a replacement for every financial tool. A physical card may be the better primary option for a person who prefers card-based payments, and cash remains useful when the phone is unavailable or the network is unreliable. I would also skip making a wallet the center of my routine if I do not want to manage financial tasks on a phone, or if the places where I usually shop do not support it. The right choice depends less on the number of features than on whether it fits the payments I actually make.
How it compares with other ways to pay
Compared with cash, DANA removes the need to carry exact notes for a supported digital payment, but it introduces dependence on a working phone and connection. Compared with a bank app, a wallet is most appealing when I want a focused route for everyday merchant payments or transfers rather than a broader view of banking. Those tools can complement one another: I can use a wallet for convenient transactions and keep my bank account, card, or cash available for other situations.
That distinction matters when choosing what to install. If my main need is to see a complete account picture or handle services specific to my bank, I would start with the bank’s own app. If I want a convenient digital wallet for common cashless tasks, DANA is more directly aimed at that routine. I would compare the payment options I already use and the merchants I visit, rather than assuming one app should replace them all.
What to expect from the app over time
DANA is a mature, actively maintained app: version 2.106.0 is the current version, and it runs on Android 5.1 or later. It has an average rating of 4.6 from around 9.1 million ratings, with about 3.3 thousand written reviews. I see those figures as a sign of broad use, not a promise that every individual transaction will be frictionless. As with any finance app, keeping it updated and using a device that you can secure are sensible parts of a responsible routine.
For a new user, the useful first step is not to explore every screen at once. I would start with one ordinary task, such as checking how a bill payment is presented, and learn where the confirmation and transaction record appear. Then I would try a transfer only after carefully checking the recipient details. That gradual approach makes it easier to understand the flow before relying on it in a rushed public setting.
My connectivity verdict
Connectivity shapes nearly every part of using a digital wallet: opening it at the counter, confirming a payment, and feeling sure that the result has registered. DANA can make everyday cashless tasks feel simpler when reception is steady and the relevant merchant or recipient is supported. In a dead zone, on a nearly empty phone, or during a connection interruption, a backup method is still the sensible choice.
In conclusion, DANA is not just another digital wallet; it’s a comprehensive financial tool that simplifies your life. With its ease of use, robust security, and tempting promotions, it’s hard not to recommend it. Whether you’re looking to pay a bill, send money to a friend, or simply enjoy the convenience of digital transactions, DANA has got you covered. Give it a try—you might just find it becoming an indispensable part of your daily routine.
Pros
- User-friendly interface for easy navigation.
- Quick and secure transactions anytime.
- Supports a wide range of payment options.
- Offers cashback and rewards for users.
- 24/7 customer support available.
Cons
- Limited to Indonesian users only.
- Requires stable internet connection.
- Occasional app lag during peak hours.
- Some features require verification.
- Not all merchants accept DANA payments.
DANA Indonesia Digital Wallet FAQ
What is DANA and how does it work?
DANA is a digital wallet platform in Indonesia that allows users to make cashless and cardless transactions effortlessly. It works by linking your bank account or credit card to the app, enabling you to pay for goods and services, transfer money, and even pay bills directly from your smartphone. The app ensures secure transactions through multiple layers of security, including PIN codes and biometric verification.
Is DANA safe to use for online transactions?
Yes, DANA is designed with robust security features to protect users' information and transactions. It employs encryption technology, secure PIN codes, and biometric authentication to ensure that all transactions are safe and secure. Additionally, DANA is regulated by Bank Indonesia, providing an extra layer of trust and reliability for users.
Can I use DANA without an internet connection?
No, you cannot use DANA without an internet connection. The app requires a stable internet connection to perform transactions, update your account balance, and access various features. However, once a transaction is processed, you will receive a confirmation notification, which can be accessed later even if you are offline.
What are the fees associated with using DANA?
DANA offers many transactions free of charge, such as paying bills, transferring money to other DANA users, and making purchases at partnered merchants. However, there might be fees for certain services like withdrawing money to a bank account or transferring funds to non-DANA users. It's advisable to check the latest fee structure within the app or on the official website to stay informed.
How can I top up my DANA wallet?
Topping up your DANA wallet is simple and can be done through various methods. You can add funds via bank transfer, through ATMs, or by using online banking services linked to your DANA account. The app also supports top-ups through convenience stores and partner merchants, providing flexibility and convenience to users seeking to maintain their wallet balance.
Read This Page in Another Language
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5
More Finance Reviews

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5

Trust: Crypto & Bitcoin Wallet
DApps Platform, Inc. 4.5 Out of 5
About This Listing
- Developer
- PT Espay Debit Indonesia Koe
- Package Name
- id.dana
- Version
- 2.128.0
- Android
- 5.1
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at help@dana.id, visit https://www.dana.id, or view the https://m.dana.id/m/standalone/policy.