UNest: Invest & Save for Kids

- 430.00 Reviews
- 3.8
- Downloads
- 100.00K
- 3.8.1
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Automated investing makes regular contributions easier to maintain.
- Parents can monitor a child’s portfolio from a single account.
- Flexible contribution options support different family budgets.
- A custodial account can help introduce children to long-term saving.
- The app provides a convenient alternative to managing investments manually.
Cons
- Investment returns are not guaranteed and account values can decline.
- Account availability and features may depend on your state and eligibility.
- Fees can reduce returns
- especially when balances or contributions are small.
- Withdrawals may be restricted until the child reaches the applicable legal age.
- Tax and custodial rules can make the account more complex than a savings account.
Review of UNest: Invest & Save for Kids Appxis
Saving for a child is easy to postpone because the goal feels distant, while the practical work of opening an account, choosing investments, and keeping contributions on track can feel like a separate project. UNest: Invest & Save for Kids brings those tasks into a finance app built around a UTMA custodial account. I found its most convincing quality to be focus: instead of trying to serve every kind of investor, it centers the experience on putting money aside for a child and building a long-term habit.
That focus makes it more approachable than a general brokerage app for a parent who does not want to sort through an overwhelming investing interface. At the same time, it is not a magic shortcut to financial planning. You still need to understand what a custodial account means, decide whether the arrangement suits your family, and accept that investing is a long-term activity rather than a guaranteed savings result. My experience with UNest: Invest & Save for Kids is therefore positive, but conditional: it is most useful when its narrow purpose matches the way you want to save.
How the app feels in everyday use
A focused starting point for a child’s financial goal
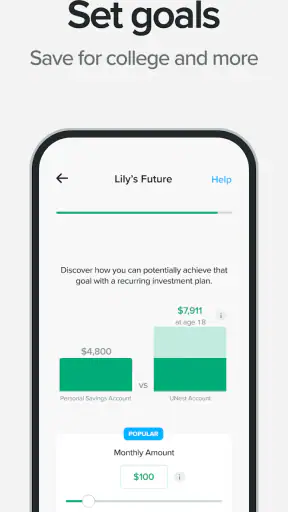
The central idea is straightforward. You use the app to save and invest for a child through a UTMA custodial account, with the intention of building wealth over time. That gives the product a clearer identity than a standard budgeting app, where a child-related goal might be only one category among many. I like that distinction because it encourages a specific conversation: how much can I consistently set aside, and what long-term purpose will this money serve?
The app is developed by UNest Holdings, Inc., and it is free to download. That lowers the barrier for a parent who wants to explore the service before committing to a recurring routine. However, the presence of in-app purchases ranging from about five dollars to around one hundred fifty dollars per item means “free” should not be interpreted as “every part of the experience costs nothing.” Before making the app part of your household finances, I would review the relevant screens carefully and make sure any optional charge fits your budget.
One useful way to approach the app is to treat it as a dedicated destination for one child-related objective, not as a replacement for every financial tool you already use. I would keep ordinary spending, emergency savings, debt payments, and retirement planning in their appropriate places. A custodial investment account can support a child’s future, but it should not compete with essentials that your family may need much sooner.
Speed expectations and the value of a calm interface
For this kind of app, perceived speed is less about flashy transitions and more about whether the path from opening the app to understanding your next action feels clear. UNest has a naturally smaller scope than a full-service investing platform, so I expect it to feel less mentally demanding during routine checks. That is important for parents who may only have a few minutes between school pickup, work, and household tasks.
I would not judge the experience by how quickly a screen appears alone. Financial actions deserve a pause, especially when money is being transferred or an investment choice is involved. A fast interface that encourages careless confirmation would be worse than a slightly more deliberate one. My preferred routine is to open the app, check the child-related goal, confirm that the contribution plan still matches my budget, and close it without turning every visit into a market-watching session.
The focused design also changes how I think about notifications and checking frequency. If your intention is long-term investing, constantly opening the app to react to short-term movement can undermine the original plan. The strongest performance experience is therefore partly behavioral: the app should help you complete a useful task quickly, then get out of the way. It is not the right tool for someone who wants a dense trading dashboard or rapid decision-making.
What happens during heavier use
Heavier use for a custodial savings app is different from heavier use for a game or video editor. You are unlikely to spend hours continuously scrolling through it. The demanding moments are more likely to happen when you review account details, think through a contribution, compare your goal with your household budget, or use the app while the phone is also handling other everyday tasks.
My practical advice is to use it when you can give financial decisions your full attention. Do not begin a contribution setup while rushing through a queue or switching between several apps. Even if the interface itself feels light, the decision behind the screen deserves care. A clear workflow can reduce friction, but it cannot decide whether the amount is affordable or whether a UTMA account is appropriate for your situation.
Families with more than one child should also think about organization before they begin. A separate goal can make each child’s progress easier to understand, but it can also create more administrative work. I would first write down the intended purpose of each account, the expected contribution rhythm, and who should receive updates. That small preparation helps prevent the app from becoming a collection of vaguely named goals that are difficult to review later.
Another non-obvious trade-off is the difference between automation and attention. Regular contributions can make saving easier because the decision is not renegotiated every week. Yet automation can also hide a budget problem if income changes. I recommend pairing any recurring plan with a monthly household check. If your circumstances shift, changing the contribution promptly is better than allowing a useful habit to become a source of stress.
Reliability matters more than visual polish
With a finance app, reliability means more than avoiding crashes. I want confidence that I can sign in when needed, understand the current state of the account, and recover sensibly if a session is interrupted. I also want to know exactly what I am confirming before money moves. These expectations are higher than they would be for a casual utility, because a confusing or interrupted financial workflow can create real anxiety even when no money is lost.
UNest has an average rating of 3.8 from around two and a half thousand ratings, alongside roughly four hundred thirty written reviews. I read that as a mixed but workable public impression rather than an automatic endorsement. The rating suggests that many people find value in the idea and execution, while the less-than-excellent average is a reminder to test the experience against your own expectations. I would pay particular attention to account access, contribution management, and how clearly the app explains each step before relying on it heavily.
Recovery is especially important when a phone loses connection, the app closes unexpectedly, or you simply stop halfway through a setup. My rule is simple: never repeat a financial action immediately just because the screen did not respond as expected. Reopen the app, inspect the account status, and verify whether the action completed before trying again. This is a sensible habit with any finance service, and it is more valuable than chasing the fastest possible interaction.
I also recommend keeping your own basic record of the purpose and expected rhythm of contributions. That is not a criticism of this particular app; it is good household practice. A separate note can help you recognize an unexpected change, remember why a contribution amount was selected, and discuss the plan with another parent or guardian. The app can be the working tool without being the only place where your financial intentions exist.
Device constraints and practical compatibility
The application supports Android devices running version 7.0 or later, which makes it accessible to many older phones as well as newer models. That is helpful for families who do not upgrade devices frequently. Still, operating-system support is only one part of the experience. An older phone may have limited free storage, a tired battery, slower multitasking, or a less dependable connection, and those factors can affect how comfortable any finance app feels.
Because this is a money-management tool, I would avoid using it on a device that is no longer receiving sensible security maintenance, even if the app can technically run there. A supported operating system does not automatically make every old handset an ideal place for sensitive financial activity. Use a device with a screen you can read comfortably, a reliable lock method, and enough stability that you will not be tempted to rush through confirmations.
The app is rated for Everyone, which fits its family-oriented purpose, but an age label should not be confused with financial independence for children. A parent or guardian still needs to understand the custodial structure and the responsibilities attached to it. I would involve a child in learning about saving only at an age-appropriate level, while keeping account access and final decisions under responsible adult control.
Resource demands are likely to be modest because the app is designed for account management rather than media-heavy content, but I would not make a precise battery or memory claim without measuring the exact device and usage pattern. In normal use, the sensible expectation is that it should be opened for short financial tasks rather than left running all day. Closing it after checking a goal is also a good privacy habit when you share a phone or use a device in a busy household.
A realistic family routine
Imagine a parent who receives income at the end of the week and wants to save for a child’s future without mixing that money into everyday spending. On payday, the parent opens UNest, checks the dedicated child goal, and confirms a contribution that still leaves room for groceries, bills, and emergency needs. The important part is not the number on the screen; it is the repeatable sequence. The app gives the goal a visible home, while the parent supplies the judgment and consistency.
At the end of the month, that parent could review whether the contribution remained comfortable, check for any optional purchase before accepting it, and discuss the purpose of the account with the other guardian. If the family budget becomes tighter, the plan should be adjusted rather than protected at all costs. If the budget improves, the parent can reconsider the amount deliberately. This workflow uses the app as a prompt for good decisions instead of treating it as an automatic answer.
A different use case is a relative who wants to contribute toward a child’s future but does not want to manage a general investment account. The dedicated purpose may make the intention easier to explain. Even then, I would clarify who controls the custodial account, what the money is intended for, and how contributions will be coordinated. A simple shared understanding can prevent duplicate efforts or assumptions about access later.
Where it beats ordinary alternatives
Compared with a basic savings account, UNest offers a more investment-oriented way to think about long-term growth rather than leaving every child-related dollar in cash. That can be appealing for a goal with a long horizon, although investment values can move and the account should not be treated like a guaranteed cash balance. A savings account may be the better choice for money that could be needed soon or for families that prioritize stability above potential growth.
Compared with a general brokerage app, the child-centered purpose is the main advantage. A broad platform may offer more flexibility, research, and account types, but that flexibility can make it harder for a beginner to keep one family goal organized. UNest is more appealing when the question is “how do I save for this child?” rather than “how do I manage a complete investment portfolio?” Experienced investors who need detailed control may reasonably prefer the broader alternative.
Compared with a budgeting app, this service addresses the destination of the money rather than the full flow of household spending. A budget tool can show where money is leaking and help create room for saving, while UNest can give the child-related goal a dedicated structure. In my view, the strongest combination is not choosing one blindly: use a budget to establish affordability, then use the custodial investment app only if the account type and time horizon make sense.
Who should use it, and who should skip it
I would recommend trying UNest if you are a parent or guardian who wants a clearly labeled, long-term investment goal for a child and prefers a focused mobile experience over a full brokerage interface. It is also worth considering if you need a practical reminder to make saving a recurring household habit. The free entry point makes exploration easier, though you should still inspect any in-app purchase before accepting it.
I would skip it for now if you are still behind on essential bills, have no emergency cushion, or need the money for a near-term expense. I would also look elsewhere if you want active trading tools, advanced portfolio analysis, several unrelated account types, or complete control over every investment decision. A custodial account is not simply a labeled savings jar, so anyone uncomfortable with its structure should learn more before contributing.
Families should also pause if they expect the app to teach a child every important money lesson automatically. It can support a conversation, but it cannot replace explaining delayed gratification, risk, budgeting, and the difference between a contribution and a guaranteed outcome. The best results come when the adult uses the app as part of a wider family plan.
My performance verdict
UNest has a sensible performance profile for its purpose: it is a focused finance app intended for short, deliberate visits rather than constant use. Its Android support from version 7.0 onward helps it reach older devices, and its child-centered design can reduce the mental clutter found in general investing platforms. I appreciate that the product gives a specific goal a clear identity instead of burying it inside an all-purpose financial dashboard.
The limitations are equally important. A 3.8 average rating and its several thousand ratings suggest a service that deserves personal testing rather than unquestioned trust. The in-app purchase range means the free download still requires attention to possible costs. Most importantly, the app cannot remove the legal, financial, and emotional responsibility that comes with saving through a UTMA custodial account.
After weighing speed expectations, heavier-use moments, reliability, and device constraints, I see this as a good fit for a parent who values simplicity and consistency. I would start with a modest, affordable routine, read every confirmation carefully, review the plan monthly, and avoid checking investment progress obsessively. For a family that wants a dedicated place to build a child’s long-term financial foundation, the strongest reason to choose UNest is its focused purpose, not the promise of effortless wealth.
It is free to install, rated for Everyone, and currently listed as version 3.8.1. With over one hundred thousand installs, it has reached a meaningful audience without becoming the only reasonable option in the category. My final recommendation is cautious but favorable: use it when a UTMA custodial account genuinely fits your plan, keep your expectations realistic, and choose a more flexible brokerage or a straightforward savings account when your needs extend beyond this app’s focused role.
FAQ
What is UNest: Invest & Save for Kids?
UNest is a family-focused investing and savings app designed to help parents and relatives build money for a child’s future. It typically lets adults create an investment account for a beneficiary, make recurring or one-time contributions, and monitor progress from a mobile device. The app is intended for long-term goals rather than short-term spending, so users should review the available account type, investment choices, fees, and eligibility requirements before signing up.
How does investing through UNest work?
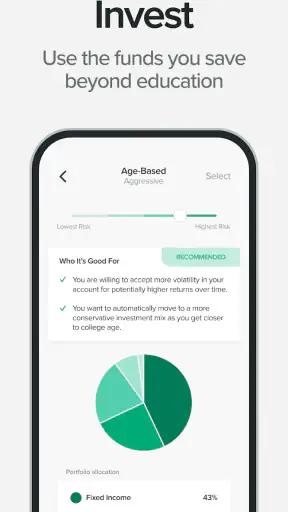
After creating an account, the adult account owner generally provides information about themselves and the child, chooses a contribution amount, and selects from the investment options available in the app. Contributions are invested according to the selected portfolio rather than held as guaranteed cash. Investment values can rise or fall with the market, and returns are not promised. Before depositing money, users should understand the portfolio’s risk level, time horizon, and possible charges.
Is UNest safe, and can I lose money?
UNest may use regulated financial partners and investment accounts, but the app itself does not eliminate normal investment risk. Money placed in market-based investments can lose value, especially over shorter periods or during market declines. Users should read the app’s disclosures to confirm custody, regulatory coverage, account protections, and the identity of the investment provider. It is also wise to use strong login security and avoid treating projected returns as guaranteed results.
Are there fees or minimum contributions on UNest?
The cost of using UNest can depend on the account, plan, investment service, and current pricing structure. Potential expenses may include subscription charges, advisory or management fees, fund expenses, transaction-related costs, or other account fees. Minimum deposits and recurring contribution requirements may also apply. Because pricing can change, prospective users should check the latest fee schedule inside the app or on its official website and compare the total cost with alternatives.
Who can open a UNest account, and how can the money be used?
UNest is primarily aimed at parents, guardians, and relatives saving or investing for a child, but availability can depend on residence, age, identity verification, and the account structure offered in the user’s region. The beneficiary may not control the funds immediately, and withdrawals or qualified uses can be subject to account rules, taxes, or penalties. Read the withdrawal conditions carefully and consider how contributions could affect future financial planning.


