Ualett

- 1.28K Reviews
- 4.6
- Downloads
- 100.00K
- 2.73.0
- Version
Screenshots
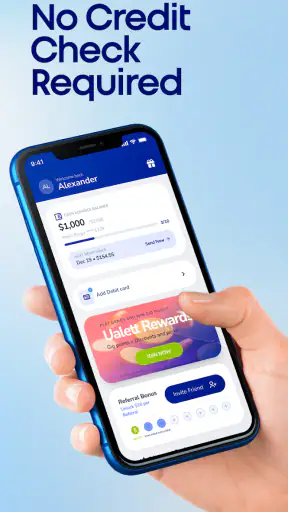
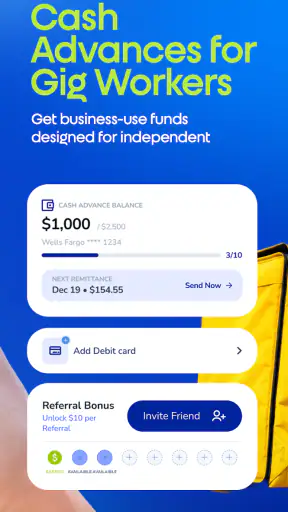
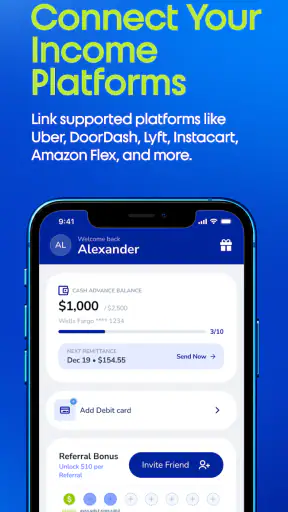
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast access to earned wages without waiting for payday.
- Simple application process completed entirely from a mobile device.
- Useful budgeting support when unexpected expenses arise.
- Transparent repayment schedule helps users plan upcoming deductions.
- Can reduce reliance on high-cost overdrafts or emergency loans.
Cons
- Availability and features may vary by employer or eligibility status.
- Early wage access can encourage repeated borrowing between paychecks.
- Fees may apply depending on the advance amount or repayment option.
- Repayments can leave less money available on the next payday.
- Requires access to employment and payroll information to function.
Review of Ualett Appxis
I approached Ualett as a practical finance app for people whose income comes from gig work rather than a fixed payroll. Its purpose is easy to understand, but the real question is whether it can make an irregular workday feel more manageable. After spending time with it, my view is that Ualett is most useful when you need a focused way to think about money earned through independent or platform-based work, without expecting it to replace a complete bank account or a full budgeting system.
The app is free, aimed at everyone, and developed by Cabicash Solutions, Inc. It has built a respectable user base, with over one hundred thousand installs, a 4.6 average from around 7,600 ratings, and roughly 1,300 written reviews. Those figures suggest that the concept is connecting with a meaningful audience, although popularity alone does not tell you whether its workflow fits your particular kind of gig work.
What to expect before you begin
Ualett is best understood as a specialized financial tool rather than a general-purpose money manager. If you drive, deliver, freelance, take short-term assignments, or combine several sources of flexible income, the app’s focus may feel more relevant than a conventional banking app built around salary deposits and monthly bills. The store summary describes it as being built for gig workers, and that focus shapes the experience.
I would not install it expecting a broad financial dashboard with every possible account-management feature. Instead, I would approach it with one clear goal: make the money side of gig work easier to handle. That might mean organizing your thinking around earnings, dealing with the timing of income, or finding a more direct routine for money that arrives outside a traditional pay cycle.
The distinction matters because gig work creates a different kind of financial pressure. A regular paycheck gives you a familiar date and amount to plan around. Independent work can produce a busy day followed by a quiet one, and the money may move through several services before it becomes available for everyday spending. A focused app can help reduce that mental friction, but it cannot make an unpredictable income stream predictable.
My first piece of advice is to define the problem you want Ualett to solve before you start. If you simply want another place to look at money, the app may not feel essential. If you need a dedicated workflow for gig-related finances, the narrower purpose becomes a strength. The best results come from using Ualett as part of a routine, not as a one-time emergency download.
It is also worth setting realistic expectations about what “free” means in practice. You can download and use the app without paying an upfront purchase price, which lowers the barrier to trying it. Still, financial apps often involve actions, eligibility checks, or terms that deserve careful reading. I would never treat the word free as a reason to skip the details shown during setup or before confirming a money-related action.
Who will get the most from it
Ualett makes the most sense for someone who already thinks of their work as flexible income. A courier working several days a week, a rideshare driver covering selected shifts, or a freelancer balancing multiple small assignments may appreciate an app designed around that reality. The value is less about replacing every financial service and more about giving gig work its own place in your money routine.
It can also suit a person who dislikes mixing work-related money with personal spending from the very beginning. Even if you still use a conventional bank for bills and long-term savings, a dedicated gig-work tool can make it easier to pause and review what your flexible work is actually contributing. That separation is especially useful when your income arrives in uneven amounts.
On the other hand, I would hesitate to recommend it as the only financial app for someone with a salaried job, complex investments, shared household finances, or demanding business-account needs. A traditional bank may be better for established account services, while a budgeting app may offer deeper category tracking and long-term planning. Ualett’s focused design is helpful only when the focus matches your situation.
Setting up a useful starting point
The first setup should be treated as a decision-making step, not a formality. Install the current version, which is 2.73.0, on a device running Android 8.0 or later, then read each screen carefully instead of tapping through automatically. The technical requirement is modest, so compatibility should be straightforward for many Android users, but the more important part is understanding what information the app requests and why it is relevant to the service.
Use details that match the identity and work situation you intend to manage. Financial tools are not a good place for casual test information. A mismatch between your personal details and your actual use case can create confusion later, particularly when the app needs to connect your work context with a financial action. I found that a careful beginning saves more time than trying to correct rushed choices afterward.
Before confirming anything, decide which gig activity you want to use as your first test case. Do not begin with every income source at once. If you deliver for more than one platform or combine contract work with driving, select the activity that is easiest for you to recognize and verify. Starting with one clear stream gives you a clean way to judge whether the app is helping.
A useful setup habit is to keep a note of your starting position outside the app. This does not need to be complicated. Write down which work source you are testing, what you expect to happen, and what result would make the app worthwhile to you. That small reference point prevents vague impressions such as “it seems useful” from replacing a real evaluation.
I would also set aside a few uninterrupted minutes for the first session. Gig workers often install financial apps between jobs, but rushing through identity, account, or work-related prompts can make the experience feel harder than it is. A calm setup lets you read instructions, notice any conditions attached to an action, and stop before committing if something does not make sense.
How to avoid an unhelpful first impression
Do not judge the app solely by how quickly you reach the opening screen. The meaningful test is whether you can move from setup to a clear, understandable financial result. If the first screen feels sparse, that may simply reflect the need for your work context or account information before the app can become useful.
At the same time, do not assume that every unfamiliar prompt is harmless. When money is involved, I recommend checking names, amounts, destinations, and timing before approving anything. This is not a criticism unique to Ualett; it is a sensible habit with any financial service. The app can streamline a task, but the responsibility to verify the task remains with you.
Another practical tip is to avoid changing several variables during the first trial. If you connect multiple work sources, switch routines, and make several financial decisions at once, you will not know which part of the experience helped or caused friction. One source, one goal, and one completed workflow produce a much clearer verdict.
Reaching the first meaningful success
For a first-time user, success should not mean merely opening Ualett or completing registration. A better milestone is completing one small, understandable action related to your gig-work finances and knowing exactly what happened afterward. That could be reviewing a work-related money movement, following the app’s intended process for handling funds, or confirming that the information you entered supports the result you expected.
I recommend choosing a low-pressure moment for this test. Do it after a completed shift or assignment, when you can compare the app’s information with what you already know. Avoid testing the service for the first time when rent, fuel, groceries, or another urgent payment depends on an immediate outcome. A financial app deserves a controlled trial before it becomes part of your emergency plan.
Once you begin the action, read the confirmation screen from top to bottom. Pay attention to the amount, the account or destination involved, and any timing language. The most common mistake with money apps is not failing to find a button; it is confirming a button without noticing a detail. Ualett may make the route feel simple, but simple screens still require careful reading.
After the action is complete, record what you expected and what actually occurred. Note whether the result was easy to understand, whether you had to repeat a step, and whether the information appeared in a place you could find again. This is one of the less obvious ways to evaluate a finance app: clarity after the transaction matters just as much as speed during it.
A realistic everyday routine
Imagine finishing a delivery-heavy afternoon and wanting to separate that day’s work from your normal household spending. Instead of immediately treating every incoming amount as available personal income, you open Ualett as part of your end-of-shift routine. You review the relevant activity, confirm the details, and then decide what portion can safely move into your ordinary spending plan after considering fuel, taxes, maintenance, and other work costs.
The app does not remove the need for those calculations, but it can give the workday a defined financial checkpoint. That is valuable because gig workers often lose track of small amounts across several days. A five-minute review after work may reveal that a busy shift was less profitable than it first appeared, or that a quiet-looking day still contributed useful income.
For a freelancer, the same idea works around a completed assignment rather than a shift. For someone with several platforms, I would use one consistent review point and avoid assuming that gross earnings equal spendable money. The app is most helpful when it supports a disciplined decision, not when it encourages you to spend as soon as money appears.
One advanced but simple workflow is to use the first completed action as a repeatable checkpoint. Keep the same order each time: identify the work source, review the amount, check the destination or status, and then update your separate personal budget. This turns Ualett from an occasional tool into a small operating habit for irregular income.
Where new users may feel confused
The biggest source of confusion is likely to be the difference between gig-work money and money that is truly available for personal use. Ualett can help you work with the former, but your real disposable income still depends on costs and obligations outside the app. Fuel, equipment, taxes, insurance, debt payments, and household bills do not disappear because an amount is visible on a screen.
I would therefore avoid using the app’s visible balance or activity as a direct spending limit unless you have already accounted for those deductions. This is particularly important for people who receive payments from more than one source. A specialized financial app can organize your view, but it cannot automatically know the full financial context of your life unless you deliberately maintain that context elsewhere.
Another point of friction may come from timing. Gig work often involves a gap between completing a task, seeing an earning, and being able to use the money. If you need funds for an immediate purchase, read the app’s status and timing information carefully rather than assuming that a completed work event means instant availability.
If an action seems stalled, first check whether you skipped a required setup step or entered information inconsistently. Then review the confirmation details before trying again. Repeating an action without understanding its current status can create unnecessary uncertainty. I prefer taking a screenshot or keeping a brief written note of what I submitted, provided that doing so does not expose sensitive information.
Privacy is another area where I would be deliberate. A finance app may need personal and work-related information to function, so read the permission and account screens instead of granting access reflexively. If a request does not make sense to you, pause and investigate it through the app’s own support or information screens before continuing. Convenience is not a reason to surrender careful judgment.
When a different tool is the better choice
Ualett is not the right answer for every financial problem. If your main goal is detailed expense categorization, a dedicated budgeting app may offer a clearer month-to-month picture. If you need conventional banking services, a bank’s own application may be more suitable. If you run a larger freelance operation with invoices, business expenses, and tax records, accounting software could be a better foundation.
I would also skip it if you have no connection to gig work and do not want a specialized workflow. A focused app can feel unnecessarily narrow when your income is already stable and your existing bank or budget system handles everything comfortably. Downloading another finance app only adds value when it removes a real point of friction.
There is a trade-off between simplicity and breadth here. Ualett’s gig-worker orientation may make it easier to approach than a large financial platform filled with unrelated tools. But that same specialization means you may eventually need another service for savings goals, household planning, investing, or business administration. I see that as a boundary to understand, not automatically a flaw.
Building a routine after the first result
Once the first action works as expected, the next step is consistency. Use the app at a predictable point in your work cycle rather than opening it only when money feels tight. A review after each workday, after a group of assignments, or whenever a payment becomes available can help you notice patterns that are invisible when you check randomly.
Keep your main financial plan outside the app if that is where you already manage bills and savings. Ualett can serve as the gig-work layer, while your bank account or budget handles the wider household picture. This two-part approach is more realistic than forcing one specialized app to manage every aspect of your finances.
For people with multiple income sources, start by learning one workflow thoroughly before adding another. Compare how easy it is to identify each source and whether the resulting information remains clear. If combining everything makes the app harder to understand, simplify the routine rather than assuming more data is always better.
Review the app after a full working cycle, not just after one successful tap. Ask yourself whether it saved time, reduced uncertainty, helped you separate work money from personal money, or made a decision easier. If the answer is no, there is little reason to keep it at the center of your routine. A free app still has a cost in attention and maintenance.
I also recommend revisiting the app’s current screens and terms whenever an update changes the experience. The current release is 2.73.0, and financial workflows can evolve. Do not rely on memory from your first session when confirming a later action; read the present screen and verify the details each time.
My recommendation for first-time users
After reviewing Ualett as a finance app, I would recommend it to gig workers who want a dedicated starting point for handling irregular work income. Its strongest quality is its clear audience: it is not trying to be everything for everyone. That makes the first step less intimidating for someone whose financial life is shaped by shifts, deliveries, assignments, or several flexible sources.
I would begin with one work stream, one modest test, and no urgent financial dependency. Complete the setup carefully, perform one action you can verify, and compare the result with your own records. If that process feels clearer than your current method, build it into a regular checkpoint. If it feels like another layer of work, a conventional bank app, budgeting tool, or accounting service may suit you better.
The app is free, available to an Everyone audience, and supported by a solid 4.6 average, so trying it is relatively low risk from a download perspective. My more important recommendation is to keep your expectations precise: Ualett can support a gig-worker money routine, but it is not a substitute for judgment, budgeting, or a complete financial plan.
In the end, I see it as a useful specialist rather than a universal solution. For the right user, that specialization is exactly what makes it worthwhile. If you earn money outside a regular paycheck and want a calmer, more deliberate path from completed work to financial action, Ualett is worth testing carefully. Use it to create a repeatable checkpoint, then let your wider budget decide what the money can really do.
FAQ
What is Ualett and what services does it provide?
Ualett is a digital financial service designed to help users manage money through a mobile application. Depending on the country and account type, it may offer features such as receiving payments, transferring funds, viewing transaction activity, and accessing other financial tools. Before downloading, check the official app listing and Ualett’s website to confirm which services are currently available in your region.
Is Ualett available for everyone, and what are the registration requirements?
Ualett availability can depend on your country, age, residency, and the type of account you want to open. Registration may require a valid phone number, email address, government-issued identification, and additional personal information for identity verification. Requirements can change, so users should review the current eligibility rules and make sure their details match their official documents before beginning the sign-up process.
Is Ualett safe to use for managing money and personal information?
Ualett may use security measures such as account authentication, identity verification, encrypted connections, and transaction monitoring to protect users. However, no financial application is completely risk-free. Use the official download source, create a strong password, enable every available security option, and never share verification codes or login details. Also review Ualett’s privacy policy to understand how personal and financial data are handled.
Are there fees, limits, or processing times when using Ualett?
Fees and transaction limits may vary according to the service, payment method, account status, and country where Ualett is used. Some operations may be free, while transfers, withdrawals, card-related services, or currency conversions could involve charges. Processing times can also differ between instant and standard transactions. Always check the in-app fee schedule and confirmation screen before approving a payment or transfer.
What should I do if a transaction fails or I cannot access my Ualett account?
If a transaction fails, first verify your internet connection, account balance, recipient details, and any applicable limits. Avoid repeating the payment until you confirm whether the original attempt was completed. For login problems, use the official recovery process rather than third-party services. If the issue remains unresolved, contact Ualett support through the app or official website and provide the transaction reference without sharing your password or security codes.


