Trump Accounts: Official App

- 453.00 Reviews
- 4.8
- Downloads
- 500.00K
- 2026.34.0
- Version
Screenshots
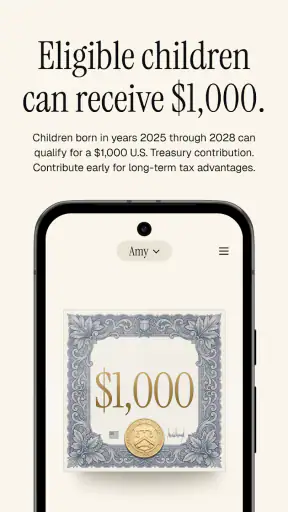
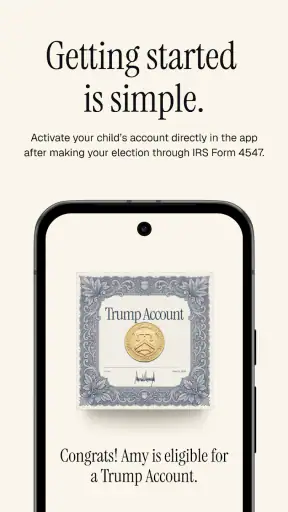
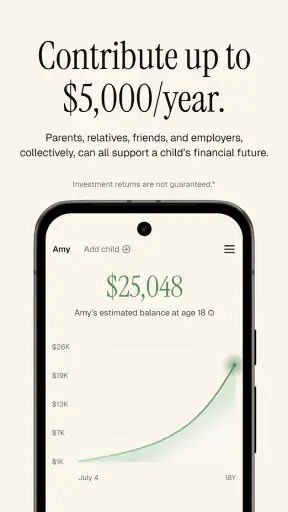
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Official source for managing Trump Account information and updates.
- Simple interface makes key account details easy to find.
- Useful notifications can help users stay aware of important changes.
- Provides direct access to official resources and guidance.
- Available on mobile for convenient access while traveling or at home.
Cons
- Some features may require eligibility or account verification.
- Information may reflect policy changes and become outdated quickly.
- Limited usefulness for people who do not qualify for an account.
- May collect personal or financial data during registration.
- Official content may offer little independent explanation or comparison.
Review of Trump Accounts: Official App Appxis
When I look at a finance app, I want to know what it helps me do in ordinary life, not just what its name promises. Trump Accounts: Official App is built around a focused idea: helping families invest in a child’s future through Trump Accounts. That narrow purpose is also its biggest strength. It is not trying to become a general banking dashboard, a budgeting tool, or a trading terminal. Instead, it gives this specific financial goal its own place on a phone.
I reviewed it as an app from the Department of the Treasury, and my overall impression is that its value depends less on how often you open it and more on whether you have a child-related reason to use it. If that situation applies to you, the app can make a long-term financial task easier to keep in view. If you are looking for everyday spending controls, investment research, or a broad personal-finance suite, you will probably find its scope too limited.
What the app’s central capability means in real use
The important capability here is not simply displaying financial information. It is putting the idea of investing for a child at the center of the experience. That changes the way I think about the app. A normal banking app usually starts with accounts, transfers, cards, balances, and transactions. A brokerage app usually begins with markets, securities, orders, and performance. This one starts with a future-oriented family objective.
That focus matters because saving for a child is easy to postpone. School costs, household bills, and short-term emergencies naturally take priority. A dedicated app gives the goal a visible home instead of leaving it buried inside a general account or a spreadsheet. In my experience, that kind of separation can make a long-term intention feel more concrete, even when the app itself is not something I need to check every day.
The store summary describes the purpose as investing in a child’s future, while the short description identifies the product as Trump Accounts. Those two phrases point to the same practical question: can this app help a parent or guardian understand and manage a child-focused investment arrangement without confusing it with ordinary household money?
That is where I see the strongest potential. Money set aside for a child can become psychologically easier to protect when it is presented as a distinct objective. I am less tempted to treat it as spare cash for an unrelated purchase, and I can discuss it with another adult in the family as a specific responsibility rather than a vague promise to save someday.
There is also an important distinction between an app that supports a financial account and an app that teaches investing from the ground up. I would not approach this as a full learning platform or as a place to explore every possible investment strategy. Its usefulness comes from keeping the child-account purpose clear. That makes it more approachable for someone who wants a direct route into this particular task, but less attractive to an experienced investor who wants broad control and detailed analysis.
A focused tool rather than a complete money-management center
I think the best way to judge this app is by asking whether its limited scope feels intentional or restrictive for you. For a parent who already has a separate bank app and only needs a dedicated place for a child’s account, the focus can be refreshing. There is less chance of mixing school-related investing with grocery spending, credit-card activity, or unrelated accounts.
For someone hoping to replace a bank, brokerage, budgeting app, and family finance organizer with one download, the experience will feel incomplete. That is not necessarily a flaw in the product, but it is a real trade-off. A specialized app can make one task clearer while leaving other tasks to different tools.
The app is free, which removes one obvious barrier to trying it. It is also rated for Everyone, so its presentation is positioned for a broad audience rather than a specialist financial crowd. I still would not interpret that age rating as a substitute for adult judgment. The account concerns a child’s future, and decisions about contributions, expectations, and access deserve careful attention from the responsible adults involved.
How I would use it during a normal family routine
Imagine a parent reviewing monthly finances after payday. The household bills have been handled, and there is a planned amount available for long-term goals. Instead of moving that money into a general savings area and hoping the purpose remains clear, the parent opens the Trump Accounts app to keep the child-focused investment task separate. The useful moment is not a dramatic market check; it is the small act of connecting a recurring family decision with a named future goal.
I would use a routine like that to avoid impulsive changes. First, I would decide the contribution amount outside the pressure of a busy day. Then I would use the app to review the child account and confirm that the action matches the plan. This separation between planning and execution is a practical safeguard: it reduces the chance that a temporary expense or emotional reaction controls a long-term decision.
Another realistic use is a conversation between two caregivers. One person may handle daily bills while the other takes responsibility for the child’s long-term account. A dedicated app gives both adults a more understandable subject to discuss. Rather than saying, “We should probably save more,” they can talk about the specific account, the purpose behind it, and whether the current arrangement still fits the family’s priorities.
For relatives who want to contribute, I would be more deliberate. I would not assume that sending money or asking someone else to act is automatically simple just because an official app exists. I would first clarify who is responsible for the account and what type of contribution is appropriate. The app can be the place where the account is managed, but family communication still matters just as much as the screen itself.
A useful habit is to review the account at a fixed interval instead of repeatedly checking it. Child-focused investing is a long-horizon activity, so frequent attention can create unnecessary anxiety. I would use the app to maintain awareness and complete planned tasks, not to turn a future goal into a daily scorecard.
Practical details that affect the decision
The app is available as a free finance app, and its current version is 2026.34.0. It supports devices running Android 7.0 or later. That broad operating-system requirement should make it approachable for people who keep an older Android phone, although the quality of the experience can still depend on the device itself and the way it handles newer app interfaces.
Its release date is May 27, 2026, so I would treat it as a relatively new product in my expectations. Newer official apps can benefit from a clean, purpose-built direction, but users may also need patience as the product matures. I would keep the app updated through the normal store process and avoid relying on an outdated installation when managing anything important.
The public response is encouraging: it carries a 4.8 average from around 3.1 thousand ratings, with more than 450 written reviews and over 500 thousand installs. Those figures suggest that many people have found the app worth trying, but they do not tell me whether it fits every family situation. A high rating is a useful signal about general satisfaction, not proof that the app replaces every alternative.
I also appreciate that the developer is identified as the Department of the Treasury. For a finance tool connected to a government-backed account concept, that identity is relevant to my trust assessment. Even so, I would still read every on-screen instruction carefully and verify that I am using the official application before entering sensitive information. An official name should encourage careful use, not eliminate it.
Where the focused design helps—and where it gets in the way
The strongest advantage is reduced goal confusion
The clearest benefit is mental separation. When a child’s future is represented in its own financial context, the goal is easier to remember and discuss. That can be more valuable than a long list of advanced tools. A general bank app may show money moving in and out, but it does not necessarily remind me why a particular balance exists. This app’s identity keeps the reason visible.
A second advantage is that the product should be easier to explain to a family member than a full brokerage platform. Someone who is uncomfortable with market terminology may find a child-focused account less intimidating than a screen filled with charts, tickers, and trading controls. I would still expect to learn the financial basics separately, but I would not need to begin with an entire universe of investment choices just to understand the purpose of the account.
A third, less obvious strength is the possibility of creating a cleaner family workflow. One adult can handle routine household money, while another reviews the child account. That division can reduce accidental mixing of funds and make responsibility clearer. The app does not solve family coordination by itself, but its dedicated purpose gives the conversation a useful anchor.
The narrow scope creates real limitations
The same focus can become frustrating if I want a complete view of my finances. I would still need another service for ordinary banking, spending analysis, debt tracking, and broader financial planning. Switching between apps is not a major hardship for everyone, but it does create extra steps. I would not choose this as my only finance app unless my needs were unusually limited.
I would also avoid treating it as a replacement for professional advice in complicated family circumstances. If parents, guardians, relatives, or other responsible adults have different expectations, the hard part may be deciding who should contribute and why—not finding the right button in the app. A dedicated account interface cannot settle disagreements about ownership, timing, or long-term priorities.
There is a behavioral trade-off as well. A separate child account can protect the goal from casual spending, but it may also make the money feel less available when a family faces a genuine emergency. That is exactly why I would decide on an emergency reserve before committing to a long-term child investment plan. The app is better suited to money I can leave invested according to the account’s rules than to cash I may need next month.
Finally, I would not use a high rating as a reason to stop asking questions. Finance apps deserve more caution than entertainment apps. Before relying on the account, I would make sure I understand who can manage it, what actions are available, how contributions are handled, and what the long-term expectations are. Those are practical questions for any child-focused financial product, and the answers should guide my decision more than the app’s attractive simplicity.
How it compares with familiar alternatives
Compared with a standard savings account in a banking app, Trump Accounts: Official App offers a more specific investment purpose. A savings account may be easier to understand for short-term needs and may feel more familiar to a cautious household. I would prefer that route when the money might be needed soon or when the family is still building an emergency cushion.
Compared with a general brokerage app, this product appears more approachable for the narrow task of investing for a child. A brokerage platform is usually the better choice for someone who wants to research investments, manage several goals, or make detailed decisions across a wider portfolio. The cost of that flexibility is greater complexity, and not every parent wants a market-focused interface for a single family objective.
Compared with a spreadsheet, the app gives the child account a dedicated official home rather than leaving the family to maintain formulas and reminders. A spreadsheet can still be useful for planning total household contributions, especially when several goals compete for the same income. I would use a spreadsheet alongside the app if I needed a broader family forecast, not as a substitute for the account’s own management environment.
Compared with a budgeting app, this is aimed at a different stage of the process. Budgeting tools help me decide whether money is available. This app is relevant after I have identified money for the child-focused goal. That distinction is important: if my household budget is unstable, the better first step is managing cash flow, not adding another long-term commitment.
Who benefits most from installing it
I think the strongest audience is a parent or guardian who wants a clear, dedicated way to keep a child’s future investment goal separate from daily finances. It also makes sense for someone who prefers an official, purpose-built experience over assembling the process from a bank app, a spreadsheet, and calendar reminders.
It may also suit families that need a simple shared reference point. When one person contributes and another monitors the account, a focused app can make the arrangement easier to explain. The benefit is greatest when everyone agrees on the goal and understands that the money is intended for the child’s longer-term future.
I would skip it, or at least postpone using it, if I had high-interest debt, no emergency savings, or an income pattern that made regular contributions unreliable. A child’s future matters, but financial stability at home matters too. I would also look elsewhere if I wanted active investment research, detailed portfolio construction, or one dashboard for every account I own.
My final view is positive but deliberately specific. This is not a universal finance solution, and it should not be judged as one. Its value is in turning a child-focused investment goal into a distinct, recognizable task. For the right family, that can make long-term planning easier to remember and less likely to disappear among everyday expenses.
My recommendation is to try it when your main question is how to keep a Trump Account organized and connected to your child’s future. Keep a separate budget for household stability, learn the account rules before acting, and use the app as part of a calm review routine rather than a source of constant market checking. With those expectations, Trump Accounts: Official App feels purposeful, accessible, and worth considering for families whose needs match its focused design.
FAQ
What is the Trump Accounts: Official App used for?
Trump Accounts: Official App is designed to provide information and guidance about Trump Accounts, including eligibility, enrollment, contribution rules, and account-related updates. After reviewing the app, its main purpose appears to be educational and administrative rather than a general banking replacement. Users can explore official explanations and follow relevant instructions, but should still confirm important details through the official government or financial institution channels before taking action.
Who may be eligible to open or receive a Trump Account?
Eligibility can depend on factors such as the child’s age, citizenship or residency status, date of birth, family circumstances, and the specific rules in effect when an application is submitted. The app may help users understand these requirements, but it should not be treated as a personalized eligibility decision. Parents, guardians, and other applicants should review the latest official criteria and provide accurate information during enrollment.
Does the app allow me to deposit, withdraw, or manage money directly?
The Trump Accounts: Official App should not automatically be assumed to function like a complete mobile banking application. Its available features may focus on explanations, registration guidance, status information, or links to approved services rather than direct control of funds. Before downloading, users should check the current app description and permissions, and verify which financial actions must be completed through an authorized provider or official website.
Is the Trump Accounts: Official App free and safe to download?
The app may be available without an upfront download charge, although related account services, investment arrangements, or third-party provider terms could involve separate conditions. For safety, download it only from a trusted Google Play or Apple App Store listing, confirm the developer name, read recent reviews, and avoid unofficial APK files. Never share passwords, Social Security numbers, or banking details through suspicious links or messages.
What information should I prepare before using the app?
Depending on the feature you are using, you may need personal details for yourself and the child, such as legal names, dates of birth, addresses, citizenship or tax information, and documentation proving parental or guardian authority. Prepare information carefully and enter it only on verified screens. If the app redirects you elsewhere, check that the destination is an official government or authorized financial-services website before submitting sensitive data.


