True Finance: Cash Advance

- 4.25K Reviews
- 4.4
- Downloads
- 1.00M
- 10.6.0
- Version
Screenshots
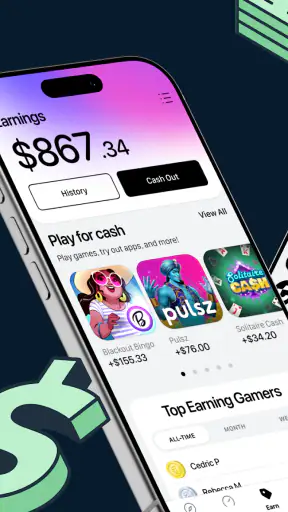
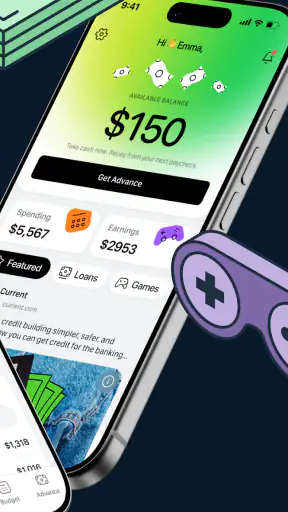
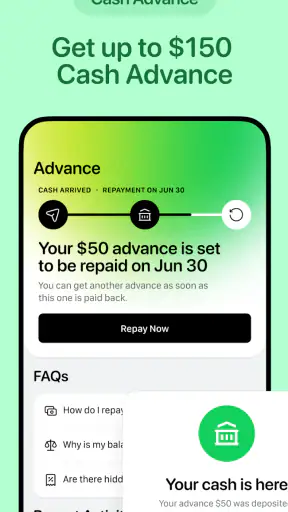
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast application process with minimal paperwork
- Clear repayment schedule helps users plan ahead
- Useful for handling unexpected short-term expenses
- Simple interface makes account details easy to find
- May offer financial education and budgeting resources
Cons
- Cash advances can be expensive compared with traditional loans
- Approval and advance amounts may vary by applicant
- Repayment withdrawals can strain a tight budget
- Not available in every state or for every user
- Late or failed payments may lead to additional fees
Review of True Finance: Cash Advance Appxis
I approached True Finance: Cash Advance as a finance app first and a borrowing tool second. That distinction matters. Its store message is built around fast cash and no credit check, but a short promise like that does not tell me whether an app will feel clear, manageable, or comfortable when money is tight. My review therefore focuses on the choices a user can actually make, the moments that deserve extra attention, and the situations where a cash-advance app may be less suitable than a slower alternative.
True Finance is developed by JoinTrueDev and is available free of charge for everyone. It belongs to the finance category, runs on Android starting with version 7.0, and its current version is 10.6.0. The app has passed the point of being a little-known experiment: it has more than a million installs, with an average rating of 4.4 from roughly forty-seven thousand ratings and about four thousand two hundred written reviews. Those figures suggest broad interest, although they do not replace careful reading when the product involves access to money.
How True Finance feels when money is urgent
The strongest reason to consider this app is speed. If an unexpected expense appears between paydays, a conventional bank application may involve a full credit process, a branch visit, or a waiting period that does not match the urgency of the situation. True Finance is aimed at a different moment: the user who wants to explore a cash advance without beginning with a traditional credit-check process.
That convenience also changes how I judge it. With a budgeting app, a confusing screen is annoying. With a borrowing app, confusing wording can affect a real financial decision. I would not treat the first approval-looking message as the end of the process. I would move through each screen slowly, check the amount, review any repayment information shown, and make sure I understand what I am accepting before continuing.
A realistic example would be a car repair that cannot wait until the next pay cycle. I can see why someone might open True Finance, enter the requested details, and look for a short-term option rather than using a credit card or asking a friend. In that situation, the useful workflow is not simply “get money quickly.” It is to compare the amount needed with the amount offered, check the total obligation, and decide whether the next paycheck can absorb the repayment without creating a second emergency.
That last step is where the app should be used with discipline. A fast advance can solve a timing problem, but it does not make the underlying expense smaller. I would use it only for a defined gap with a clear repayment plan, not as a way to cover recurring bills month after month. If rent, utilities, food, or existing debt already consume most of the next paycheck, a cash advance may postpone the pressure rather than remove it.
What the no-credit-check message means in practice
The phrase “no credit check” is attractive to people who may not qualify for ordinary credit products, but I would not read it as “no assessment” or “no conditions.” Any financial service still needs enough information to determine whether it can present an offer and how that offer works. The important question is not merely whether a traditional credit check occurs; it is what information the app requests, why it requests it, and what the final terms mean.
My practical advice is to treat every permission and form field as part of the decision. If a screen asks for information that seems unrelated to the cash-advance request, I would pause rather than automatically approve it. I would also avoid entering details while distracted or rushing, because the fastest route through an application is not always the clearest route.
For someone comparing alternatives, True Finance sits closer to an emergency-access tool than to a full banking replacement. A bank account app may offer stronger day-to-day money management, a budgeting app may be better for preventing the next shortfall, and a credit union or employer-based advance program may be preferable when its terms are more transparent. The right comparison is therefore not “which app is fastest?” but “which option solves this exact cash-flow problem at the lowest understandable cost and risk?”
Controls I would check before accepting anything
The most important controls are the ones that let me stop, revise, or leave. I want to know whether I can change the requested amount before submission, whether the repayment date is visible, and whether the app clearly separates an eligibility result from an actual agreement. These are small interface details, but they determine whether I remain in control during a high-pressure decision.
I would also look for a clear confirmation step rather than assuming that tapping a button is harmless. Before confirming, I would reread the amount received, the amount expected back, the timing, and any charge or condition displayed on screen. If the wording is difficult to understand, that is a reason to stop and seek clarification, not a reason to hurry because the application feels urgent.
Another useful habit is to save or record the final terms for personal reference. I would keep the confirmation information in a secure place and add the repayment date to my calendar. This is especially helpful when the app is used during a stressful event, because remembering the exact details later can be harder than expected.
Account access deserves the same care. I would use a strong, unique password if the app requires one, avoid sharing login details, and review the account periodically rather than leaving it untouched after receiving funds. If the app provides settings for notifications or account management, I would use them deliberately. Notifications can be useful reminders, but they can also become noise if every alert is accepted without thought.
Privacy decisions happen before the advance
Finance apps naturally involve sensitive moments. A user may enter identity information, income-related details, banking information, or contact data. I do not assume that a permission is harmless simply because it appears during a familiar signup flow. I read the explanation attached to each request and consider whether the choice is necessary for the action I am trying to complete.
My approach is to grant the minimum access needed for the specific task. If a permission can be denied without blocking the core application process, I would leave it disabled until I understand why it is useful. If denying it prevents progress, I would decide whether the service is worth that trade-off rather than granting access automatically. This is not about treating every request as suspicious; it is about making the choice consciously.
I would pay particular attention when the app moves from general browsing to account connection or application submission. That transition is a data-sensitive moment because the information entered may be used to evaluate eligibility or arrange delivery of funds. I would verify that I am on the intended screen, check the spelling of account details, and avoid using a public or shared device for the process.
It is also worth separating convenience from necessity. A feature that makes an application faster may still be optional. I prefer an app that lets me review what I am sharing and gives me a clear way to manage the account afterward. When those choices are visible, I can decide with more confidence. When they are buried behind vague wording, I become much more cautious, regardless of how attractive the advance sounds.
Where user agency can be lost
Financial urgency makes people vulnerable to optimistic assumptions. A user may see a promising result and mentally spend the money before reading the conditions. I think the safest way to use True Finance is to keep the decision in stages: first explore, then review the offer, then compare it with alternatives, and only afterward decide whether to proceed.
That staged approach also helps with amount selection. If I need a modest sum, I would not request more simply because a larger amount appears available. Borrowing only what addresses the immediate expense reduces the chance of turning a temporary gap into a larger repayment problem. It also makes it easier to judge whether the advance is genuinely useful rather than merely tempting.
I would never let speed pressure me into sharing verification codes, passwords, or account credentials with another person. If someone claims to represent the service and asks for information outside the normal in-app flow, I would stop and verify the request through an official channel. The app may be designed for quick access, but account security still depends on the user protecting private details.
After the advance, I would check the account again rather than assuming everything is finished. I would confirm that the expected transaction occurred, watch for the repayment date, and review notifications for changes or requests. If I no longer intend to use the service, I would look through the account controls and support options to understand how to manage or close the account. That follow-up is easy to skip, yet it is one of the best ways to keep an emergency tool from becoming an unattended financial commitment.
Who will benefit most from it
True Finance makes the most sense for an adult who has a specific, short-lived cash-flow gap and already knows how the repayment will fit into the next budget. It may appeal to someone who wants to explore an advance without starting with a traditional credit-check route, especially when a conventional lender would be too slow or inaccessible.
I would also see value for a user who prefers handling the process from a phone and is willing to read every screen carefully. The free download lowers the barrier to trying the app, but the financial decision itself should never be treated as free simply because installing the app costs nothing. The real evaluation begins when the user sees the available terms.
It is less suitable for someone looking for long-term debt management, automatic budgeting, or a substitute for stable income. It is also a poor fit for anyone who cannot identify the next repayment source. In those cases, a nonprofit debt adviser, a local credit union, an employer-supported option, or a direct conversation with the bill provider may offer a healthier path. A slower solution can be better when it prevents repeated borrowing.
How it compares with familiar alternatives
Compared with a credit card, a cash advance may feel more targeted because the user seeks a defined amount for a near-term need. A credit card can be more flexible, but that flexibility may encourage a balance to remain open. The better choice depends on the exact terms and on whether the user can repay promptly. I would compare the total obligation rather than choosing based on speed alone.
Compared with an overdraft, True Finance may be preferable when I want to decide on an amount in advance instead of allowing a bank balance to fall below zero unexpectedly. An overdraft, however, may already be part of an existing account relationship and could be simpler for a very small timing issue. Again, I would examine the cost, timing, and consequences of each route.
Compared with a budgeting app, True Finance addresses the immediate shortage rather than the pattern that caused it. A budgeting tool may be the better long-term investment if the same problem appears every pay cycle. I would use the advance only as a bridge while also identifying the recurring expense, irregular income, or payment date that keeps creating the gap.
Compared with borrowing from a friend or family member, the app may feel more private and structured, but personal borrowing can sometimes avoid formal application steps or financial charges. The trade-off is emotional and practical rather than purely technical. I would choose the option that preserves dignity while remaining clear and realistic for everyone involved.
My verdict after weighing convenience against caution
True Finance: Cash Advance is easy to understand as a concept: it is a free finance app from JoinTrueDev designed for people seeking quick access to cash without beginning with a conventional credit check. Its broad adoption and 4.4 average rating show that many users are interested in this type of service, and the Everyone age classification makes its audience broad. The current 10.6.0 release also indicates an actively maintained product line rather than a forgotten listing.
Still, I would not recommend it on speed alone. My recommendation depends on the user reading the complete offer, checking the repayment impact, limiting permissions to what feels justified, and keeping control of account access. The safest use is a one-time bridge with a written repayment plan, not a routine answer to an ongoing budget deficit.
If I had a clear emergency expense, enough income arriving soon, and terms I could explain in my own words, I would consider using it. If the repayment details were unclear, the requested information felt excessive, or the advance would leave me short again, I would choose another route. That is the honest position: True Finance can be useful in a narrow situation, but its convenience should support a careful decision rather than replace one.
FAQ
What is True Finance: Cash Advance, and how does it work?
True Finance: Cash Advance is a financial app designed to help eligible users explore short-term cash advance options and manage related financial information from a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking details so the service can assess eligibility. Approval, available amounts, fees, and repayment terms are not guaranteed and can vary by user and location.
Is True Finance: Cash Advance a direct lender?
Before applying, it is important to understand True Finance’s role in the transaction. The app may operate as a connection service or marketplace rather than lending money directly. In that case, your information could be shared with third-party lenders or financial providers. Carefully review the final offer, including the lender’s identity, annual percentage rate, fees, repayment schedule, and any authorization for automatic withdrawals before accepting anything.
How much money can I receive, and how quickly is it deposited?
The amount you may be offered depends on factors such as your income, banking history, eligibility, state regulations, and the policies of the participating provider. A cash advance is not automatically approved simply because you submit an application. If approved, the timing of a deposit may range from the same business day to several business days, depending on verification, banking hours, weekends, and the receiving institution.
What fees, interest, and repayment conditions should I check?
Users should read the complete terms carefully because the total cost of a cash advance can include interest, origination charges, subscription fees, late fees, or other service costs. Repayment may be scheduled as a one-time withdrawal or several automatic payments from your bank account. Compare the annual percentage rate and total repayment amount with other options, and confirm what happens if a payment is late or your account lacks sufficient funds.
Is True Finance: Cash Advance safe to use, and what information does it collect?
As with any financial application, use the official Google Play or Apple App Store listing and verify the developer before downloading. The app may request sensitive information such as your identity details, contact information, income, employment data, and bank account credentials. Review its privacy policy, permissions, security practices, and data-sharing disclosures. Never provide passwords, verification codes, or banking access through unofficial links or messages.


