Together Loans

- 272.00 Reviews
- 4.3
- Downloads
- 100.00K
- 9.1.2
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple way to explore shared loan options with another applicant
- May help combine incomes when applying for eligible loan products
- Useful for couples
- family members
- or co-borrowers planning together
- Centralized application details can make coordination more convenient
- Can provide access to loan information without visiting a branch
Cons
- Approval and rates depend on lender criteria
- credit
- and income
- Both applicants may share responsibility for repayment
- A missed payment could affect each borrower’s credit history
- Loan availability and terms may vary by location
- Sharing financial details requires trust between all applicants
Review of Together Loans Appxis
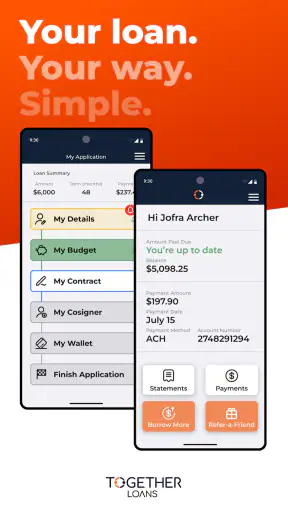
Managing a loan is rarely something I want to do from a crowded website or a folder of emails. I usually want a quick way to check where things stand, understand what needs attention, and avoid missing an important payment detail. Together Loans is built around that narrower need: it is a finance app from Transform Credit Inc for managing a Together Loans account in one place. After looking at how it fits into everyday borrowing, I see it as a focused companion rather than a complete personal-finance manager.
The app is free to install, carries an Everyone age rating, and works on Android devices running version 7.0 or later. Its current version is 9.1.2, which gives the product a reasonably current feel for people using older phones as well as newer ones. It has passed the early discovery stage too, with more than one hundred thousand installs and a 4.3 average from roughly six hundred ratings. Those figures do not make it automatically right for everyone, but they do suggest that borrowers are finding a practical reason to keep it available.
How Together Loans fits into real loan management
My first impression is that the app makes most sense when I already have a Together Loans relationship. It is not designed as a general-purpose budgeting tool where I can combine bank accounts, compare every lender, or build a broad spending plan. The useful question is much simpler: can I use one mobile place to stay on top of my loan?
That focus is its main strength. A dedicated loan app can be easier to return to than a general finance application filled with unrelated charts and account connections. If I only need to review my borrowing and handle routine account tasks, a focused interface may reduce the number of steps between opening the app and finding the information I need.
There is also a practical psychological benefit. Loan management is easier when it becomes a small, repeatable habit instead of something I postpone until a letter, reminder, or unexpected concern forces me to deal with it. I would be more likely to open a dedicated account app during a weekly money check than search through old messages for the right account page.
A realistic everyday use case
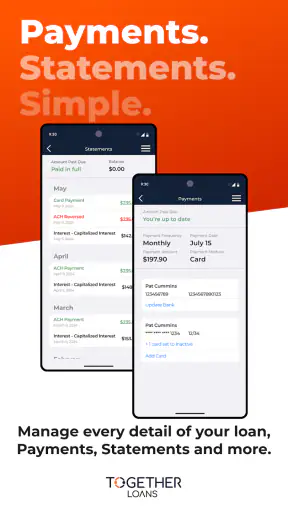
Imagine that I am paid near the end of the week and use that time to review upcoming commitments. I open Together Loans, check the state of my loan, and compare what I see with the money I have set aside for regular bills. If something looks unfamiliar, I can investigate it while I still have time to contact the lender rather than discovering the issue after a payment problem.
That workflow is deliberately modest, but it is useful. The app does not need to replace my banking app to earn a place on my phone. It only needs to make loan-related checking less awkward. I would keep my bank application for balances and transfers, a budgeting app for household planning, and Together Loans for the account it is specifically meant to manage.
One tip I would give a new user is to open the app at a calm moment, not for the first time when a payment is already urgent. Confirm that the account information is familiar, learn where the important loan details appear, and make a note of any support route shown inside the account. This small setup habit makes later checks faster and helps separate a genuine account issue from simple uncertainty about where to look.
What the current release tells me
The current release, 9.1.2, is the version I would expect users to encounter today, while the app itself was released on April 2, 2024. That combination points to a product that has moved beyond its initial launch and is being maintained through later revisions. It is fair to view the newer version as evidence of ongoing product work, but not as proof that every possible loan-management feature has been added.
This distinction matters with financial software. An updated version can improve reliability, navigation, compatibility, or account handling without changing the basic purpose of the app. I would therefore expect the core experience to remain centered on managing a Together Loans account, rather than turning into a full banking platform. That is a sensible direction if the app stays clear and dependable.
For existing users, the most important effect of a newer release is usually not a dramatic visual change. It is whether opening the app feels predictable, whether account information is easy to locate, and whether routine actions create less friction. When I review a loan app, I care more about those quiet improvements than decorative redesigns because a financial tool is often used for a few focused minutes at a time.
Users on older Android phones should pay attention to the minimum operating-system requirement. Android 7.0 is not especially demanding, so the app remains accessible to people who have not upgraded recently. That is valuable for a finance tool: borrowers should not need a brand-new handset simply to check a loan account. At the same time, older devices can vary in speed and security support, so keeping the phone itself updated where possible is still a sensible part of responsible account use.
Where it is stronger than usual alternatives
Compared with managing the same loan through a mobile browser, a dedicated app can feel more direct. I do not have to remember which page to open or work around a desktop-oriented layout. The trade-off is that the app occupies space on my phone and gives me one more account application to maintain. For someone who checks a loan often, that exchange is worthwhile; for someone who looks once every few months, a browser may be enough.
Compared with a general budgeting app, Together Loans has a narrower but potentially cleaner job. A budgeting tool may help me understand how a loan affects my whole household, but it may not provide the same account-specific path for checking the loan itself. I would not use Together Loans as a replacement for a budget planner because it is not the right tool for comparing groceries, utilities, savings, and debt in one overview.
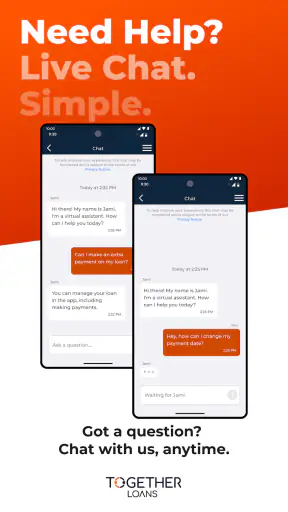
It also differs from contacting support every time I need a routine update. Self-service is convenient when the question is straightforward and the relevant account information is already available. However, I would not treat the app as a substitute for human assistance when a payment is disputed, personal details are wrong, or I need an explanation of a lending decision. Those situations deserve careful clarification rather than a quick tap through an account screen.
Small workflows that make the app more useful
The most useful habit is to pair an app check with an existing money routine. I might review it after checking my bank balance, before planning discretionary spending, or on the same day I reconcile recurring bills. This turns the app into a checkpoint instead of an emergency tool. The key is consistency, not repeatedly opening it without a clear purpose.
A second useful approach is to treat displayed information as something to verify when it affects a decision. If I am deciding whether I can afford another commitment, I would use the loan details as one part of the calculation and also review my bank account and personal budget. A loan-management app can show the state of that loan, but it cannot understand every other obligation in my life.
Third, I would avoid relying on memory after viewing the account. If a figure, date, or account status affects what I plan to do next, I would record the relevant detail in my normal financial notes or calendar, using the app as the source for checking rather than assuming I will remember it correctly. This is especially helpful for people who have several recurring commitments and do not want a single app to become their only reminder system.
These workflows reveal an important trade-off. The app can make access more convenient, but convenience does not remove the need for careful review. A focused loan app is at its best when it reduces searching and repetition while I remain responsible for understanding what I am agreeing to and for acting before a deadline.
Who should use it, and who should skip it?
I would recommend Together Loans to an existing Together Loans customer who wants a straightforward mobile route to their account. It is also a reasonable choice for someone who prefers a dedicated finance app over logging in through a browser, especially if regular loan checks are part of their monthly routine. The free price removes an obvious barrier to trying it, provided the person already has a reason to manage this particular loan through the app.
I would skip it if I am looking for loan comparison, refinancing research, credit education, or a complete household budget. Those needs call for different tools. I would also hesitate if I rarely use mobile finance services and already have a browser workflow that is quick, familiar, and reliable. Installing an app is not automatically an improvement when the existing method already handles occasional checks comfortably.
It is not the right answer for someone who expects one application to manage loans from several unrelated providers. Its identity is tied to Together Loans, so the value depends on having the matching account relationship. Likewise, people who need extensive financial analysis may find a dedicated budgeting or debt-planning tool more informative, then use this app only for account-specific confirmation.
Remaining gaps and points of friction
The narrow scope that makes the app approachable can also make it feel limited. I would not expect the same breadth of planning tools found in a full personal-finance application, and I would not judge it harshly for that. The more important question is whether the focused account experience is complete enough for routine management. If I still need to move repeatedly between several channels for ordinary questions, the convenience advantage becomes smaller.
Another possible friction point is the difference between viewing information and resolving a problem. An app can help me see an account, but a complicated repayment concern may still require direct communication. That is normal for financial services, yet users should approach the app with realistic expectations. It can be the first place I check, not necessarily the final place where every issue is settled.
I would also be careful about using any financial app while distracted or on an unfamiliar network. I prefer checking that I am in the official application, reviewing the account details before taking action, and avoiding rushed decisions based on a notification or message. These are not glamorous features, but they matter more than a polished screen when the subject is borrowing.
The rating of 4.3 from about six hundred ratings is encouraging, while the roughly two hundred seventy written reviews give prospective users more context than a score alone. I treat both as signals rather than guarantees. A person who only needs basic account access may have a very different experience from someone expecting advanced budgeting, detailed repayment forecasting, or broad lender support.
What I would watch as the app evolves
For future releases, I would watch how clearly the app communicates changes that affect existing borrowers. In a loan app, even a small adjustment to the location or wording of an important account detail can create confusion. Clear navigation and stable access should remain more important than adding features simply to make the release notes look busy.
I would also look for improvements that help users distinguish routine information from something requiring action. A good account experience should make it obvious what I am viewing, what I can do next, and when I should seek help. That kind of clarity would benefit both first-time users and people who have managed their loan through the app for a long time.
Another area worth watching is how well the app serves different phone generations while keeping account access dependable. Supporting Android 7.0 and later makes the app available to a broad range of devices, but continued compatibility work matters as the mobile environment changes. For existing users, a release is valuable when it preserves access without making familiar tasks harder.
Finally, I would judge future development by whether it respects the app's focused purpose. Together Loans does not need to imitate a bank, a credit marketplace, or a complete budgeting suite to be useful. Its best evolution would make loan management clearer, faster, and easier to verify while leaving broader financial planning to tools designed for that job.
My final view after using it as a loan companion
Together Loans is a sensible option for the specific borrower it is built to serve: someone who wants mobile access to a Together Loans account without turning loan management into a larger financial project. I like its focused role, free availability, broad Android compatibility, and the fact that the current version shows continued work after launch. The app is easiest to recommend when the user already knows exactly why they need it.
My honest reservation is that its usefulness depends heavily on expectations. It should not be mistaken for a complete money-management system, a loan comparison service, or a replacement for support when an account issue is complicated. I would use it alongside my banking and budgeting tools, not instead of them.
If that division of responsibilities suits you, the app can make a repetitive financial task less inconvenient. I would install it, learn the account layout before I need it, connect its checks to an existing money routine, and keep independent records for important decisions. For a Together Loans customer, that is a practical and measured way to get value from the app without asking it to do a job it was never meant to handle.
FAQ
What is Together Loans, and how does the app work?
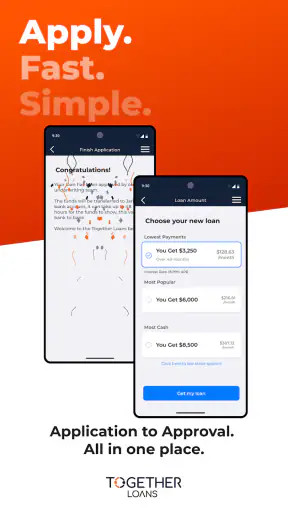
Together Loans is a loan-related service designed to help users explore borrowing options and manage the application process from a mobile device. Depending on your location and eligibility, the platform may collect personal and financial information, present available loan offers, and connect you with lenders or brokers. It is important to understand that the app may not be the lender itself, and approval, rates, fees, and repayment terms can vary.
Can I be approved for a loan through Together Loans?
Approval is never guaranteed. Together Loans may assess information such as your income, employment status, credit history, requested amount, and repayment ability before showing potential options. Each lender uses its own eligibility requirements and risk assessment. Even if the app displays an offer, you should review the final agreement carefully, since the amount, interest rate, fees, and repayment schedule may differ from your initial expectations.
What information does Together Loans require from users?
To process a request, Together Loans may ask for identifying details, contact information, employment and income data, banking information, and permission to perform credit-related checks. Providing accurate information is essential because incorrect or incomplete details can delay the application or lead to unsuitable results. Before submitting anything, check the app’s privacy policy to understand how your data is collected, shared with providers, stored, and protected.
Are loans obtained through Together Loans expensive or subject to fees?
The cost of borrowing depends on the lender and your personal financial profile. A loan may include interest, origination charges, late-payment fees, broker fees, or other costs, and some short-term products can have particularly high annual percentage rates. Do not rely only on the advertised amount or monthly payment. Compare the APR, total repayment, repayment dates, and all applicable charges before accepting an offer.
Is Together Loans safe to use, and what should I check before downloading it?
Before using Together Loans, download it only from an official app store or verified source and confirm the developer’s identity, permissions, privacy policy, and customer-support details. Avoid any service that asks for upfront payment to guarantee approval or pressures you to accept immediately. Read independent reviews and the complete loan agreement, and never share passwords, security codes, or unnecessary banking credentials through unofficial channels.


