Till: Debit Card for Kids

- 318.00 Reviews
- 4.5
- Downloads
- 100.00K
- 162.41.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Parents can set spending limits and monitor purchases in real time.
- Kids learn budgeting through controlled
- everyday card spending.
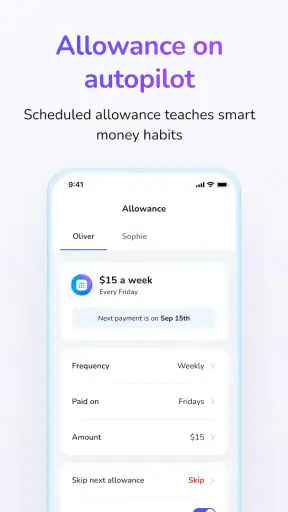
- The app can support allowances and recurring payments.
- Parents retain oversight without handling every small purchase.
- Useful transaction notifications help identify spending quickly.
Cons
- Availability and features may vary by country or region.
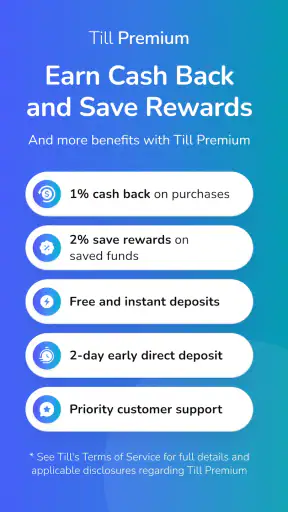
- The service may require a paid subscription or account fees.
- Kids need a compatible smartphone and internet access to use the app.
- Some merchants or payment types may not accept the card.
- Parents must review privacy and data-sharing settings carefully.
Review of Till: Debit Card for Kids Appxis
Choosing a money app for a child is less about finding the longest feature list and more about finding a setup that a family can actually use every week. I approached Till: Debit Card for Kids with that in mind. It is a finance app from Till Financial, paired with a debit card intended to help kids and teens become more thoughtful spenders. The app is free to download, rated for Everyone, and has built a solid audience with over 100 thousand installs and an average rating of 4.5 from around 2.2 thousand ratings.
My main takeaway is that Till makes the most sense for parents who want to introduce everyday spending in a controlled way rather than simply hand over cash or open a standard adult banking app. It can turn small purchases into practical lessons, but it is not automatically the best choice for every family. The right decision depends on how much guidance you want, how independently your child already handles money, and whether you are comfortable with the app’s optional paid elements.
What I would consider before choosing Till
The real question is how much structure your family needs
Before installing a kids’ debit card app, I would first ask what problem I am trying to solve. If the goal is simply to give a teenager spending money, a conventional bank account or prepaid card may be enough. If the goal is to teach planning, make spending visible, and create regular conversations about choices, a dedicated family finance app is more appealing.
Till sits in that second group. Its purpose is not just to replace notes and coins with a card. The useful part is the shared context around spending: a child gets a practical way to use money, while a parent gets a reason to stay involved. That makes it particularly relevant for allowances, school-day purchases, small personal treats, and the gradual move toward independent spending.
I would also think about the child’s age and temperament. A curious child who benefits from seeing the result of each purchase may learn a lot from this kind of setup. A teenager who already manages money confidently may find parental involvement unnecessary. The Everyone content rating makes the app broadly suitable from a content perspective, but suitability in real life still depends on maturity and the family’s rules.
Look beyond the card and examine the family workflow
The card itself is only one part of the experience. A useful setup needs a routine: deciding when money is added, agreeing on what the money is for, checking spending together, and discussing what happens when the balance runs low. Without that routine, even a well-designed finance app can become another forgotten icon.
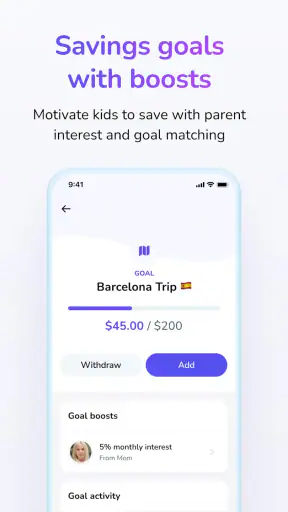
I found it helpful to think of Till as a conversation tool as much as a payment tool. For example, a parent could set a regular allowance, ask the child to divide it between immediate spending and a personal goal, and then review the result later. The important lesson is not that every purchase must be approved. It is that the child can start connecting a decision at the checkout with the money available afterward.
That workflow is more valuable than a one-time lecture about saving. It gives the child repeated, low-stakes practice. It also gives parents a chance to correct misunderstandings early, such as assuming that a card balance will refill automatically or treating available money as unlimited.
Three practical tests I would use before committing
First, decide whether you want visibility or full control. Some parents mainly want to know where a child’s spending money goes, while others want a more hands-on arrangement. Till is most attractive when you want a middle ground: the child can practice making choices, but the family still treats the account as part of a shared learning process.
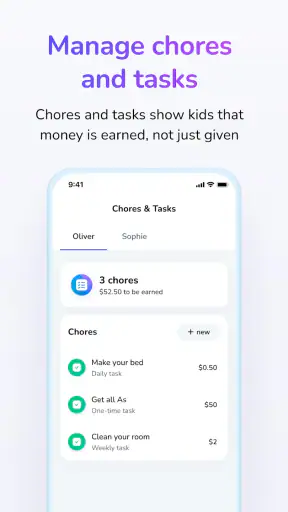
Second, test whether the app fits your allowance habits. A weekly allowance, money for chores, and occasional transfers require different routines. If your family changes its approach frequently, the value of a structured app may be reduced by the effort of constantly explaining new rules. I would agree on a simple schedule before making the card part of daily life.
Third, consider how you will handle exceptions. Children may need money for an unexpected school activity, a forgotten lunch, or a group outing. A good family plan should explain what happens in those moments. The app can support the money arrangement, but it cannot replace a clear agreement about emergencies, borrowing, or asking for help.
Where Till works particularly well
It makes spending lessons concrete
The strongest reason I would recommend Till is that it brings financial education into ordinary moments. Abstract advice such as “save more” is easy to ignore. Seeing a balance change after buying a snack is much more immediate. The child can understand that money is limited, that choices compete with one another, and that waiting for a future goal may require skipping something today.
This is especially useful when the parent avoids turning every transaction into a judgment. I would not use the app to criticize every small purchase. Instead, I would ask questions such as, “Was that worth it to you?” or “How much do you want to keep for the weekend?” Those questions make the card part of a learning process rather than a surveillance device.
A realistic school-week example
Imagine a teenager receiving money for several school days. On the first day, the teenager buys an inexpensive drink and a snack. By midweek, there is less available for an outing with friends. With Till, that situation can become a useful review of priorities: was the early convenience worth the later restriction, and what could be done differently next time?
The lesson works because it happens at the right scale. The child is not dealing with rent, bills, or a complicated bank statement. The amounts are small enough to recover from a poor choice, but meaningful enough to show consequences. I see this as one of the app’s less obvious strengths: it can make financial cause and effect visible before the stakes become serious.
It supports a gradual move toward independence
Parents often face an awkward transition. Holding every dollar too tightly leaves a child unprepared, but giving unrestricted access can create avoidable problems. A dedicated debit card for kids offers a practical middle stage. The child gets experience using a payment card, while the family can continue setting expectations around spending.
That gradual approach matters for teenagers preparing for more independence. They need to learn not only how to pay, but also how to pause before paying, check what remains, and recognize when a request for more money is really a request to change priorities. Till is well suited to that educational phase.
The app has a focused purpose
Because Till is built around children, teens, and spending habits, its purpose is easier to explain than a general banking application. A child does not need to navigate a broad collection of adult financial products to understand the basic idea. A parent can introduce it with a simple rule: this is your spending money, and we will use the app to help you learn how to manage it.
That focus can also make family discussions less intimidating. Instead of presenting a child with a full banking environment, parents can begin with everyday decisions. Later, those lessons can support conversations about saving, budgeting, and responsible card use.
Useful insight: treat the first month as a learning experiment
I would not begin by trying to create a perfect budget. For the first few weeks, I would observe how the child naturally uses the card. Does the balance disappear quickly? Does the child ask before spending? Does the child remember upcoming plans? Those patterns reveal more than a parent’s assumptions.
After observing the routine, I would adjust one thing at a time. Perhaps the allowance timing needs to change, or perhaps the child needs a separate target for a planned purchase. This approach reduces arguments because the family is responding to real behavior instead of imposing a complicated system from day one.
Useful insight: use spending reviews to teach trade-offs, not shame
A review should focus on choices and consequences rather than labeling purchases as good or bad. A small treat may be entirely reasonable if the child understood the trade-off. Conversely, a supposedly sensible purchase may still be a problem if it was made without considering a known obligation.
This distinction is important because the app is most effective when the child feels ownership. If every transaction becomes an opportunity for criticism, the child may stop engaging honestly. I would keep reviews short, regular, and focused on what the child wants to do differently next time.
Useful insight: create a rule for balance surprises
One practical source of confusion in any family money system is the unexpected balance. A child may assume that money is available because a parent added it, while the parent may assume the child knows why it appeared. I would agree in advance on how additions are explained and whether the child should ask before using unexpected funds.
That small rule prevents misunderstandings and turns deposits into teaching moments. It also helps distinguish regular allowance from special-purpose money, such as funds intended for a particular activity.
What may cause friction
The app does require family participation. Parents who want a completely hands-off solution may become frustrated if they must explain rules, review spending, or keep the allowance routine consistent. A child who sees the card as unlimited freedom may also resist the educational side of the arrangement.
There is another consideration: although the app is free, in-app purchases range from $7.99 to $79.00 per item. I would review any optional purchase carefully before committing to it and decide whether the free experience already meets the family’s needs. The presence of paid items does not make the app unsuitable, but it does mean the household should set a clear boundary around spending inside the app itself.
Version and device considerations
Till’s current version is 162.41.0, and it requires Android 7.0 or later. That makes checking the child’s device an important first step, especially if the phone is older or shared within the family. I would install it on the devices that will actually be used for the routine, rather than assuming every family phone will be compatible.
The app was released on April 27, 2022, and has since attracted more than two thousand ratings and over three hundred written reviews. Those figures suggest that it is not a brand-new experiment, but I would still judge it by how well it fits the family’s current habits rather than by popularity alone.
When another type of option may fit better
A regular bank account may suit older, confident teenagers
If a teenager already understands balances, card payments, and basic budgeting, a conventional youth or bank account may be a better long-term direction. It can feel more like the financial environment the teenager will eventually use as an adult. The trade-off is that the experience may be less focused on teaching and less approachable for a younger child.
I would choose that route when independence is the priority and the parent does not need a child-centered learning layer. Till is better when the family wants to build habits deliberately rather than simply provide access to an account.
A prepaid card may be enough for a narrow purpose
Some families only need a controlled way to provide spending money during travel, school events, or occasional outings. In that case, a simple prepaid solution may involve less setup and fewer ongoing conversations. It can be practical when the card is temporary or used for one specific purpose.
The weakness is that a narrow prepaid arrangement may not encourage a consistent allowance routine. If the goal is to teach decision-making over time, Till’s family-oriented approach is more compelling. If the goal is merely to limit the amount available for a particular occasion, a simpler option may be easier.
Cash remains useful for younger children
Cash has an advantage that digital cards cannot completely replace: the child can physically see the money getting smaller. For a young child who is still learning basic counting, that visual feedback may be more powerful than an app balance. Cash also avoids device issues and does not require a child to understand card payment habits immediately.
I would consider starting with cash when the child is just beginning to learn what money is. Till becomes more attractive when the child is ready to practice the behavior they will need for modern everyday spending, including checking a balance and making choices without holding every bill in their hand.
Think about the cost of switching
Moving from cash to Till is not only a technical change. It changes how the family talks about money. The child may need time to understand that a card is not a source of extra funds, and the parent may need to stop rescuing every poor decision. I would explain the rules before handing over the card and agree on how often spending will be discussed.
Switching away from Till can also take adjustment if the child has become used to a particular routine. That is not a reason to stay with it forever, but it is a reason to choose deliberately. I would avoid changing systems in the middle of an important period unless the current arrangement is causing real problems.
Who should skip it
I would skip Till if the family does not want to participate in financial coaching at all. A child-centered debit card works best when adults provide context and consistency. I would also look elsewhere if the child needs a fully independent banking relationship, if the household prefers physical cash only, or if optional in-app spending would create unnecessary temptation.
It may also be a poor fit for families that want one financial app for every adult and child need. Till has a specific purpose, and that focus is a strength for learning but may feel limited beside a broader banking setup. In that situation, a general account could reduce the number of systems to manage.
My recommendation after weighing the trade-offs
I recommend Till: Debit Card for Kids to parents who want a practical bridge between cash allowances and adult banking. Its best use is not as a replacement for family guidance. Its best use is as a shared framework for letting a child make manageable spending decisions, see the consequences, and gradually become more confident.
I would start with a simple plan: define the allowance purpose, explain what happens when the balance is low, and schedule a brief review after the first few weeks. I would resist adding complicated rules until the child’s real habits make a need clear. That keeps the experience approachable and gives the child a genuine sense of responsibility.
The free price makes it easy to explore, while the Everyone rating and Android 7.0 minimum make the basic device check straightforward. At the same time, families should remember that optional purchases can cost from $7.99 to $79.00 per item, so I would decide in advance whether those purchases are allowed. The app’s strong average rating and more than 100 thousand installs are encouraging signs of interest, but personal fit matters more than those figures.
My final judgment is positive, with a clear condition: use Till as a teaching routine, not just as a card. It is a strong choice for parents who want their kids and teens to practice spending in everyday situations while adults remain involved. For a child who needs visible cash, a teenager ready for a conventional account, or a family seeking a completely hands-off solution, another category may be better.
FAQ
What is Till: Debit Card for Kids, and how does it work?
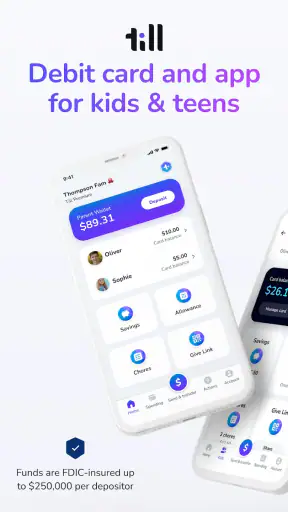
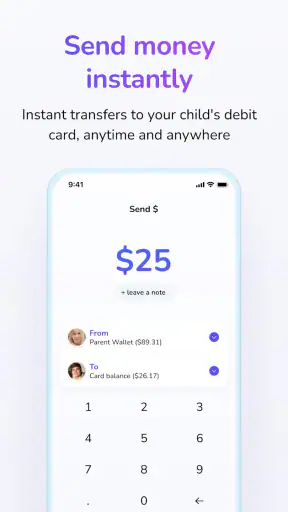
Till is a family-focused debit card and money-management app designed to help children learn how to spend, save, and manage money under parental supervision. A parent or guardian typically creates the account, controls the child’s card settings, and can transfer money or assign allowances. The exact features, availability, and account requirements may vary depending on location and the current terms offered by Till.
What age is Till suitable for, and does a parent need to approve the account?
Till is intended for children and teenagers, but the appropriate age range depends on the provider’s current eligibility rules and local regulations. Because the account involves a payment card for a minor, a parent or legal guardian generally needs to open or authorize the account, verify their identity, and remain responsible for supervision. Check the latest requirements before signing up, especially if your child is near an age limit.
Can parents control spending and monitor transactions with Till?
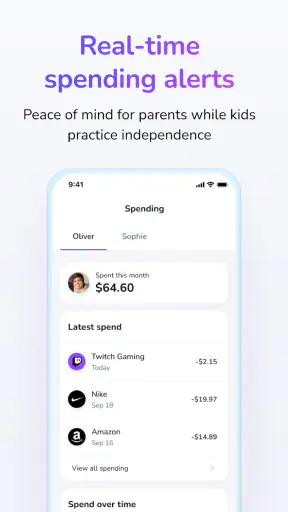
The main benefit of a children’s debit-card service such as Till is parental oversight. Parents can generally review transactions, send money, manage allowances, and teach spending habits from their own account or dashboard. Depending on the plan and region, controls may include notifications, spending limits, or card-management options. Parents should still review the available controls carefully, since features and restrictions can change.
Are there fees or spending limits associated with Till?
Before downloading or ordering a Till card, families should review the current pricing information carefully. Costs may include subscription charges, card-related fees, replacement-card fees, or charges for certain services, while some features may be included at no additional cost. There may also be transaction, ATM, funding, or daily spending limits. Fees and limits can depend on the selected plan, location, and account terms.
Is Till safe for children to use, and what happens if the card is lost?
Till is designed around supervised spending, which can make it a useful way to introduce children to real-world money management without giving them unrestricted access to a traditional bank account. However, parents should explain card security, PIN protection, and responsible purchasing. If the card is lost or stolen, it should be locked or reported through the app as quickly as possible, followed by any replacement steps required by Till.


