Split Pay: Split Bills in Two

- 462.00 Reviews
- 4.8
- Downloads
- 100.00K
- 2.0.4
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Splits shared expenses quickly between two people.
- Clear payment tracking helps avoid forgotten reimbursements.
- Useful for meals
- trips
- rent
- and everyday shared purchases.
- Simple interface makes adding and reviewing bills straightforward.
- Reduces awkward conversations about who owes what.
Cons
- Designed mainly for two-person splits
- limiting larger group use.
- Both users may need the app for the smoothest experience.
- Features may depend on supported payment services and regions.
- Frequent shared expenses can require repetitive manual entries.
- Privacy-conscious users may hesitate to link financial information.
Review of Split Pay: Split Bills in Two Appxis
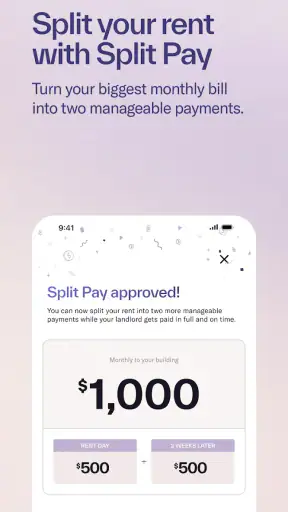
Paying a large expense all at once can make an otherwise manageable month feel unnecessarily tight. Split Pay: Split Bills in Two is a finance app from Split Pay built around that simple problem: rent, mortgage and car payments can be divided into two payments instead of leaving the full amount to one moment. I approached it as a first-time user would, looking for a clear path from installation to a useful result rather than treating it like a general budgeting tool.
The app is free and aimed at Everyone, which makes the initial decision easy: there is no purchase barrier to test the idea. It belongs to a narrower part of personal finance than a traditional expense tracker or banking app. You are not opening it primarily to review every coffee or build a long-term investment plan. You are opening it when the timing of a major recurring bill matters as much as the total amount.
That focus is both its appeal and its main boundary. If your goal is to divide restaurant bills among friends, track shared household spending or manage several bank accounts in one dashboard, this is probably not the tool I would choose. If your biggest concern is how to handle a substantial housing or vehicle payment in two stages, the concept is much more relevant.
Getting from installation to a useful payment plan
What I expected before using it
The store summary points directly to rent, mortgage and car payments, so I did not expect a broad financial command center. That helped set the right expectations. The useful question is not whether the app can replace a bank, but whether it can make a two-part payment routine easier to understand and follow.
Its public reception is encouraging, with a 4.8 average from around 3.3 thousand ratings and more than 100 thousand installs. Those figures suggest that the central idea is resonating with a meaningful audience, although they do not remove the need to check whether the workflow matches your own payment arrangement.
The app was released on December 5, 2023, and the current version is 2.0.4. It requires Android 10 or later. Those details matter to a first-time user because an older phone may be the first obstacle before the financial workflow even begins. On a compatible device, the free entry point makes it practical to try without committing money simply to understand the service.
Start with the bill, not with your whole financial life
My advice is to install Split Pay with one specific payment in mind. Do not begin by trying to reorganize every monthly obligation. Pick the bill whose timing causes the most pressure, such as rent arriving before your income feels fully available, or a vehicle payment that competes with other early-month expenses.
Have the basic facts ready before you begin: the amount you need to cover, the date or schedule connected to that bill, and the account or payment method you normally use. This preparation is more valuable than entering a long list of unrelated expenses. A focused first setup makes it easier to tell whether the app actually improves your routine.
I also recommend checking the payment arrangement itself before relying on any plan. Splitting your own preparation into two stages is not the same as changing the terms agreed with a landlord, lender or finance provider. The app can help you organize the timing, but your original payment obligation still matters. If a creditor requires one payment on one exact date, you should confirm that a two-part approach is acceptable before treating the app as a solution.
The first setup should answer three practical questions
As you move through the initial workflow, keep asking three questions: what total am I trying to cover, when does the money need to be ready, and what will I do at each stage? These questions prevent a common mistake with payment-planning tools: confusing a schedule with extra money.
A split arrangement changes the timing of your contributions or payments; it does not reduce the underlying bill. That distinction is especially important for someone using the app for a mortgage or car payment. I would write the full obligation down separately, then use the app to make the two-part plan visible. This simple habit keeps the convenience from turning into false confidence.
For a first-time user, the best setup is deliberately small. Enter or organize one recurring obligation, review the result, and only then decide whether another payment belongs in the same routine. Starting with several bills at once makes it harder to identify where confusion came from if the schedule does not fit your income pattern.
Your first meaningful success
The first successful action is not merely opening the app or creating an account. It is reaching a point where you can look at one major bill and know exactly what the two payment stages mean in your month. If you can explain the plan to yourself without reopening the app, the setup has done its job.
Imagine a renter who receives income in two parts during a month. Instead of waiting until the rent deadline and hoping the full amount is still available, that person can use Split Pay to structure the obligation around two moments. The practical benefit is visibility: the rent is treated as an ongoing responsibility rather than a surprise that appears at the end of the month.
That scenario also shows the app's strongest use case. It is most useful for people whose total income is sufficient, but whose cash flow feels uneven. Someone who cannot cover the full bill even after planning will not solve the underlying problem simply by dividing the timing. The app can organize money; it cannot create it.
Once the first plan makes sense, I would add a reminder to review it before each stage. Even if the app presents the split clearly, your income date, bank balance and other obligations can change. A quick check prevents you from following last month's arrangement automatically when this month's circumstances are different.
Where first-time users may hesitate
The phrase “split in two” sounds simple, but it can lead to several different interpretations. It might mean dividing the amount into two contributions, arranging two payment events, or using a service that sends money on your behalf. Those are not identical. Before committing to a schedule, read each screen carefully and identify whether you are planning your own funds or initiating an actual payment process.
This is also where I would avoid entering sensitive financial information casually. Use the official app source, check that the developer name is Split Pay, and make sure you understand what an action will do before confirming it. Finance apps deserve more attention than a casual utility because an unclear tap can affect a real obligation.
Another possible source of friction is the difference between a recurring bill and a one-time expense. Rent, mortgage and car payments naturally repeat, so a routine can become valuable. A one-off bill may still be organized in two stages, but the benefit is smaller unless its deadline genuinely creates a cash-flow problem.
How it compares with familiar alternatives
A banking app is usually better for seeing actual balances, completed transactions and the official status of a payment. A spreadsheet is often better for people who want complete control over formulas, multiple income sources and long-term projections. A standard budgeting app is stronger when the main task is categorizing spending across an entire household.
Split Pay makes more sense when the problem is narrower: one large obligation needs to be handled in two parts. Its advantage is reduced mental overhead. You do not need to build a full budget just to think clearly about rent or a vehicle payment. The trade-off is that a focused tool may leave you wanting more context if your financial situation is complicated.
I would choose a bank app when confirmation and account history are the priority, a spreadsheet when flexibility matters most, and Split Pay when a clear two-stage routine is the missing piece. In practice, they can complement one another, but I would not mistake this app for a replacement for official payment records.
Three habits that make the app more useful
- Plan around your real income rhythm: choose two stages that reflect when money actually arrives, rather than selecting dates that look tidy but leave you short before payday.
- Keep a separate full-bill check: after arranging the split, compare the combined amount with the original obligation so that a partial view never replaces awareness of the total.
- Review before repeating: recurring payments feel automatic, but income changes, holidays and unexpected expenses can make last month's plan unsuitable.
A fourth habit is useful for couples or housemates: agree on who is responsible for each stage before using the schedule. The app may help one person organize the payment, but it does not automatically settle disagreements about ownership, reimbursement or shared contributions. Clear communication outside the app remains essential.
Who should use it, and who should skip it?
I think Split Pay is a good fit for a person with a predictable major bill and a predictable income pattern who wants to distribute the pressure across two moments. Renters, homeowners and drivers may all recognize the problem, especially when one payment dominates the beginning or end of the month.
It can also suit someone who dislikes full budgeting apps. If categories, charts and account connections feel like unnecessary work, a focused payment routine may be easier to maintain. The value comes from using it consistently for the specific obligation that causes stress, not from filling it with every detail of your financial life.
I would skip it if you need debt counseling, investment management, detailed household accounting or a complete transaction ledger. I would also be cautious if your income is irregular enough that two planned stages are still unreliable. In that situation, a flexible cash-flow worksheet or direct conversation with the bill provider may be more appropriate.
Important questions to settle before relying on the routine
One question is whether the app changes the bill itself. It should be treated as a way to organize a two-part approach, not as permission to ignore the original terms of a lease, loan or payment agreement. Confirm the acceptable method with the relevant provider whenever the payment is contractually fixed.
Another question is whether the app replaces your bank. It does not occupy the same role in my workflow. I would still use the bank or lender's official record to verify that a payment was received, while using Split Pay to keep the preparation and timing understandable.
You may also wonder whether it is suitable for shared bills. It can be useful when one person is coordinating a household payment, but the people involved still need to agree on contributions and deadlines. A split schedule is not automatically the same as splitting responsibility among several people.
Device compatibility is another practical checkpoint. The current version is 2.0.4 and the minimum operating system is Android 10, so I would check the phone's software before planning around the app. This is a small step, but it avoids discovering an installation problem when a payment deadline is close.
Finally, ask whether the app solves a recurring problem or merely adds another place to check. If your bank already gives you a clear way to reserve money ahead of a bill, the extra routine may not be worthwhile. If you repeatedly reach a large payment date feeling unprepared despite having enough income overall, the focused structure is more likely to earn its place.
My recommendation after testing the workflow
I like Split Pay because it starts with a recognizable financial pain point instead of asking me to build an entire personal-finance system. The free price makes experimentation low-risk, and the focus on rent, mortgage and car payments gives the app a clear identity. Its strongest result is psychological as much as practical: a large obligation becomes a sequence I can prepare for rather than one intimidating deadline.
Still, I would use it with discipline. Keep the original bill visible, verify the official payment status elsewhere, and review the plan whenever income or expenses change. The app is not a shortcut around affordability, and it should not be used to make an unaffordable obligation look manageable.
For a first-time user, my suggested path is simple: install it on a compatible device, choose one major recurring payment, prepare the amount and timing details, create a two-stage routine, and check that the combined plan matches the real obligation. If that process leaves you more confident and less likely to scramble before the deadline, then Split Pay is doing exactly what I would want from a focused finance app.
FAQ
What is Split Pay: Split Bills in Two, and how does it work?
Split Pay: Split Bills in Two is designed to help you divide shared expenses between two people without relying on manual calculations. After entering the bill amount, you can usually choose how the cost should be divided, such as equally or according to individual amounts. It is useful for meals, rent, shopping, travel expenses, and other everyday payments.
Can I split a bill unevenly with Split Pay?
Yes, the app is intended to be useful when two people do not owe the same amount. Instead of simply dividing the total in half, you can enter different contributions or adjust the split according to what each person ordered or paid for. Before confirming the calculation, check that the individual amounts add up correctly to the complete bill total.
Does Split Pay include tips, taxes, or additional charges?
Split Pay can be helpful for bills that include more than the original purchase amount, but the exact handling of tips, taxes, service fees, and discounts may depend on the app’s available options and version. It is best to enter the final amount shown on the receipt or carefully include each extra charge before sharing the result.
Is Split Pay: Split Bills in Two free to download and use?
The availability of free features, advertisements, subscriptions, or optional purchases can vary depending on the platform and the current version of Split Pay. Before downloading, review the app store listing for its latest pricing information. If the app offers premium tools, confirm what is included in the free version so you know whether it meets your needs.
Does Split Pay require an account or internet connection?
A simple bill-splitting calculator may work without creating an account or maintaining a constant internet connection, which is convenient when you are paying at a restaurant or traveling. However, features such as synchronization, sharing, updates, or payment-related tools may require connectivity. Check the permissions and store description before installation, especially if privacy is important to you.


