

SoLo Funds: Lend & Borrow
Solo FundsFinance
Scanned and Safe · Free
- Rating
- 4.6Out of 5
- Downloads
- 500.00K
- Android
- 8.0
Screenshots
Analysis by Appxis
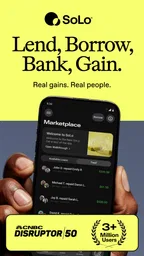
When an unexpected bill lands between paydays, it can be tempting to look for any quick way to cover it. I see SoLo Funds as a more specific option: it connects people seeking short-term loans with people willing to lend. That peer-to-peer approach may suit someone who values a direct, community-based arrangement, but it also asks both sides to make thoughtful decisions rather than treating borrowing as automatic.
What the app offers today
SoLo Funds is a free finance app from Solo Funds, available on Android and iOS. It is rated for Everyone, and its current version is 2.9.11. It has an average rating of 4.2 from around 21,000 ratings, with about 5,000 written reviews and over 500,000 installs. Those figures suggest a substantial user base, but they are not a promise that every loan request will be funded or every lending experience will go smoothly.
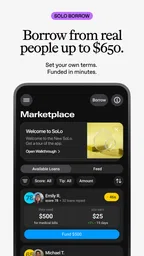
The central idea is simple: borrowers post requests, while lenders decide whether to fund them. A borrower can state the amount needed and a repayment date, and may offer a tip as an incentive to a lender. That flexibility is part of the appeal, but it is worth pausing over the total repayment obligation before accepting any offer. A small, immediate solution can become a harder problem if the date or amount does not fit your budget.
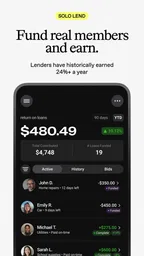
For lenders, the app presents borrower information, including a SoLo Score and repayment history, to help inform a choice. I would treat those as decision aids, not guarantees. Lending through an app still means taking on uncertainty, so only consider money you can afford to have tied up or potentially not receive back on schedule.
Setting Up and Getting Started
Jumping into the SoLo Funds app was surprisingly easy. It’s available on both Android and iOS, so no one’s left out. The interface is super user-friendly, and within minutes, you’re all set up with your profile. All you need is to link your bank account, which, by the way, is securely handled. Trust me, they’ve got their security game on point!
How It Works
The idea here is pretty straightforward. You can either lend money to others or borrow from them. If you’re the one lending, you can browse through requests and select whoever you’d like to lend to based on their profile and repayment history. It’s kind of like lending to a friend, except you’re doing it through an app with a bunch of features to protect your interests.
For borrowers, the process is just as straightforward. You post your request, stating the amount you need and when you can pay it back. There’s a cool feature where you can offer a ‘tip’ to lenders, which is essentially an incentive for them to lend you the money. It’s a win-win situation!
More Stories While You Read






Choosing the right role for your situation
Borrowing makes the most sense when the need is specific, short-term, and matched to a realistic repayment plan. Imagine a necessary car repair arrives just before payday and delaying it would interfere with getting to work. You could consider a request only after checking that the repayment date leaves room for rent, food, and other bills. If repayment depends on an uncertain bonus, a client paying late, or another loan arriving, I would not treat the app as a safe fix.
Lending calls for a different kind of discipline. It may appeal to someone who wants to help other users while evaluating individual requests, but it is not a substitute for a savings account or a predictable investment. Before choosing a request, I would read the profile details carefully, compare the repayment history with the requested terms, and decide in advance what amount I could tolerate being delayed. The ability to select whom to fund is useful; it does not remove the possibility of a late or missed repayment.
Community and Reliability
One thing I really appreciate about SoLo Funds is the emphasis on community. It’s not just a transaction; it feels more like a community effort to help each other out. Plus, there are ratings and reviews for both lenders and borrowers, so you can gauge who you’re dealing with.
And if you’re worried about reliability, they’ve got you covered. The app has a SoLo Score that helps lenders assess the risk before they lend money. It’s a neat way to ensure everyone’s responsible and trustworthy.
Where it differs from familiar alternatives
Compared with asking a bank for a personal loan, this model is organized around individual requests and peer decisions rather than a conventional lender’s application process. That can feel more direct, but it is not the same as having a bank approve a fixed product with terms you can assess in advance. Compared with a credit card, it also does not simply provide a reusable credit line for everyday purchases. The request-and-funding model is better suited to a defined short-term need than to ongoing cash-flow gaps.
It also differs from borrowing informally from a friend. The app gives users profiles, histories, and a process for making requests, which can make the interaction feel more structured. Still, that structure should not lead either side to overlook the personal financial risk. A borrower should not assume a request will be matched just because it is posted, and a lender should not assume a score or positive review guarantees repayment.
Small decisions that can prevent bigger trouble
As a borrower, I would work backward from the repayment date before posting anything. Start with expected take-home income, subtract bills already due, and leave a buffer for ordinary surprises. Then decide whether the amount requested is the minimum that solves the problem. Asking only for what is needed can make repayment easier to plan and avoids turning a temporary shortfall into a larger obligation.
The tip deserves similar care. It may help make a request more appealing to a lender, but it is still part of the cost of getting money. I would compare the full amount due with other realistic options rather than choosing a tip simply to make the request look attractive. If paying it back would force you to skip another essential bill, the safer decision may be to seek a different arrangement or wait.
Lenders can also use a simple personal rule: do not let the app’s browsing experience turn lending into impulse spending. Set a limit before reviewing requests, avoid concentrating money you need soon in a single loan, and judge each borrower on the information available rather than on an appealing story alone. Diversifying decisions may reduce dependence on one request, but it cannot eliminate risk or guarantee an overall return.
My Personal Experience
I decided to give both lending and borrowing a shot. As a lender, it was reassuring to see all the necessary info before making a decision. Plus, getting paid back was a breeze. On the flip side, borrowing was equally smooth. I posted my request, received funds in no time, and the repayment process was straightforward. Honestly, I was impressed by how hassle-free everything was.
What to keep in mind before relying on it
Even when an individual experience is smooth, I would not build a monthly budget around receiving funds through a request. Timing and lender interest matter, so a borrower facing a deadline should have a backup plan. The app is more appropriate for a one-off gap than for recurring expenses that show the regular budget is not working. Repeatedly borrowing to cover essentials can make the next repayment harder, even if each request seems manageable on its own.
For someone deciding whether to lend, the key question is not simply whether a borrower looks reliable. It is whether the lender can handle the possibility that the money will not come back when expected. If that uncertainty would affect rent, bills, or emergency savings, I would keep the money accessible instead. Anyone who needs guaranteed access to their funds should choose a more liquid, lower-risk place for them.
The app was released on October 22, 2021, and version 2.9.11 is the current release identified here. Those facts establish a product history and a present version, but a version number alone does not tell me which individual screens or policies have changed over time. Existing users should focus on what they see in the current app before accepting a request or lending: review the displayed terms, repayment date, and account details rather than relying on memory of an earlier experience.
Who should choose another option
I would skip SoLo Funds if you need certainty that a loan will arrive by a particular hour or date, if you cannot identify a dependable repayment source, or if you are uncomfortable with peer-to-peer lending risk. It is also a poor fit for lenders who expect guaranteed returns, and for anyone who would be distressed by a delayed repayment. In those cases, a more conventional source of credit, a payment plan negotiated directly with a service provider, or help from a trusted person may be more suitable, depending on the costs and terms involved.
On the other hand, it may be worth considering if you understand the request-and-lender model, need a clearly bounded short-term amount, and can assess the repayment plan honestly. For a lender, it may suit someone comfortable reviewing requests one by one and accepting uncertainty. The free price to download does not make borrowing or lending financially risk-free, so I would make the decision based on the actual terms shown for a request, not on the fact that the app itself costs nothing.
What I would watch as a user
Before each transaction, I would check whether the amount, repayment date, and any offered tip still make sense for my circumstances. I would also pay attention to how the app presents borrower histories and the SoLo Score, remembering that these tools help with judgment rather than replacing it. For current users, changes to the request flow or displayed terms are worth reviewing carefully as the app evolves; for new users, the practical test is whether the current process offers enough clarity to make a decision without rushing.
My overall view is that SoLo Funds has a clear purpose and a distinctive peer-to-peer approach, with useful context for people on both sides of a request. Its community feel and borrower information can make the process more considered than an informal cash ask, but neither feature removes financial uncertainty. I would use it selectively, with a repayment plan or lending limit set beforehand, and would choose another route whenever certainty matters more than flexibility.
Pros
- Quick loan approval process
- User-friendly interface
- Low interest rates
- Flexible repayment terms
- Secure transactions
Cons
- Limited to U.S. users
- Requires bank account linking
- Potential for high late fees
- Strict credit checks
- No offline access
SoLo Funds: Lend & Borrow FAQ
What is SoLo Funds and how does it work?
SoLo Funds is a peer-to-peer lending platform designed to provide users with the flexibility to lend and borrow small amounts of money. The app operates by connecting borrowers in need of quick cash with lenders willing to fund their loans. Borrowers can request loans by setting their terms, including the amount needed and the repayment date. Lenders can then choose to fund these requests based on their preferences. The platform also includes a social impact aspect, allowing users to support their communities financially.
Is SoLo Funds safe to use for transactions?
SoLo Funds employs various security measures to protect users' financial and personal information. The app uses encryption technology to ensure data privacy and has implemented secure transaction protocols to safeguard monetary exchanges. Additionally, the platform verifies user identities to increase trust and reduce fraud. While no system is entirely foolproof, SoLo Funds prioritizes user security and continuously updates its systems to address potential vulnerabilities.
What are the fees associated with using SoLo Funds?
SoLo Funds does not charge any mandatory fees to borrowers or lenders. However, borrowers can choose to offer a voluntary 'SoLo Tip' to lenders as an incentive for funding their loan requests. Additionally, borrowers may opt to contribute to the SoLo Community Fund, which supports users who may be unable to repay their loans on time. These contributions are optional, and the platform's primary revenue comes from these voluntary transactions.
Who can use SoLo Funds, and are there any eligibility requirements?
SoLo Funds is available to individuals who are at least 18 years old and reside in the United States. Users must also have a valid bank account to facilitate transactions on the platform. While there is no credit check required to join, borrowers are encouraged to maintain a positive repayment history to increase their chances of having their loan requests funded by lenders. The platform aims to be inclusive, providing financial solutions to those who may not qualify for traditional lending options.
How quickly can I expect to receive a loan through SoLo Funds?
The time it takes to receive a loan through SoLo Funds can vary based on several factors, including lender availability and user profile. Once a loan request is posted, lenders can review and decide whether to fund it. In many cases, loans can be funded within hours, but it may take longer if there are fewer active lenders at the time. The app's design facilitates quick transactions to provide borrowers with the financial assistance they need in a timely manner.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Solo Funds
- Package Name
- com.solofunds
- Version
- 2.19.0
- Android
- 8.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at help@solofunds.com, visit https://solofunds.com/, or view the https://solofunds.com/privacy.