

Self - Credit Builder & Cards
Self Financial, Inc.Finance
Scanned and Safe · Free
- Rating
- 4.7Out of 5
- Downloads
- 1.00M
- Android
- 7.0
Screenshots
Analysis by Appxis
I’d approach Self - Credit Builder as a structured credit-building tool, not a quick way to borrow spending money. The central trade-off is easy to miss at first: you make scheduled payments toward a loan, but the funds are held rather than handed to you upfront. That can suit someone who wants a steady repayment record and can manage the monthly commitment, but it is a poor fit if you need cash immediately or might struggle to keep payments current. I’d decide whether that trade makes sense before signing up, rather than treating the app as a general-purpose finance account.
Where people can get stuck
The most common point of confusion is the gap between making payments and receiving the saved funds. This is not an instant cash advance: the money becomes available at the end of the payment schedule described in the original review. If your reason for downloading it is an urgent bill, that timeline may not match your need. I’d separate the two goals in my own budget: credit-building is a longer-term project, while emergency cash needs a different plan.
Another possible snag is expecting a score to change as soon as a payment clears. Credit-building depends on a record developing over time, and a score can move for reasons beyond one account. I’d treat any score displayed in a finance app as a progress signal, not a promise or a complete picture of every lender’s decision. The useful question is whether I can keep the commitment consistently, not whether the number jumps after the first payment.
Check the commitment before you begin
Before choosing a plan, I’d read its payment schedule and total obligations carefully, then compare the monthly amount with bills that already have fixed due dates. The app’s appeal is partly that payments can be automated and reminders can help, but automation is not a substitute for having enough money in the account. A calendar reminder a few days before a scheduled payment is a simple backup, especially if your income arrives on varying dates.
It also helps to confirm that the personal and payment details you enter are accurate. If an application step does not go through, I’d first check for typos, confirm that the connection is stable, and review any on-screen instructions rather than repeatedly submitting the same information. Those are basic checks, but they can prevent a small setup mistake from turning into a confusing account issue.
Recover the routine when life gets busy
A realistic example: I’m paid every other week, have rent and utilities due at different times, and want to build a payment history without relying on memory. I’d map the plan’s monthly due date against my paydays, keep a modest buffer if possible, and use the app’s reminders as a prompt to check that the money is available. That routine makes the commitment easier to manage than simply assuming an automated payment will always work.
If a payment seems missing or the app shows something I don’t understand, I’d avoid making a duplicate payment until I’ve checked the account activity and the payment status. Then I’d use the app’s support channel for an account-specific answer. General troubleshooting can help with a login or connection problem, but only support can clarify what happened to a particular payment. That distinction matters: a delay in what appears on screen is not, by itself, proof that a payment failed.
More Stories While You Read






Know what the app can and cannot solve
Self is a finance app from Self Financial, Inc., and it focuses on a specific task: building credit through a repayment plan while setting funds aside. It is not interchangeable with a budgeting app, a regular savings account, or a credit card used for everyday purchases. Those tools serve different jobs. A budget can help you see where your money goes; a savings account can keep cash accessible; a credit card can provide revolving credit but requires careful management. I’d choose based on the gap I’m actually trying to fill, rather than expecting one app to do all three.
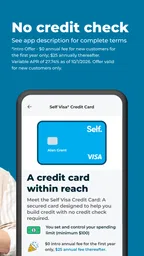
The no-credit-check positioning may make the app worth exploring for people who have limited credit history or want another route to establish one. Still, approval, account terms, and the effect on an individual credit profile are personal matters, so I would read the current plan details before committing. If I already have a manageable credit product that reports payment history, adding another monthly obligation may not be necessary. And if I need flexible access to cash, a product that holds the funds until the schedule ends is likely the wrong tool.
For an everyday workflow, I’d use the app as a deliberate monthly commitment rather than something to check obsessively. Review the plan, note the due date, verify that a payment has posted, and look at credit progress occasionally. Checking a score repeatedly can create noise without changing the habits that matter most. The more useful benefit is having one clearly defined payment routine that I can sustain alongside rent, utilities, and other priorities.
What Exactly is Self - Credit Builder?
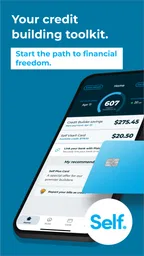
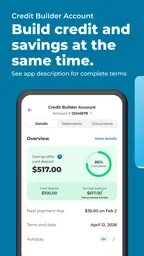
Imagine having a tool that not only helps you build your credit but also saves money while you’re at it. That’s pretty much the premise of this app. It’s designed for those of us who’ve struggled with credit scores and need a straightforward way to boost them. The app offers a unique feature: it allows you to take out a small loan, which you pay back in monthly installments. The catch? You don’t get the money right away. Instead, it’s placed in a secured account, and once you’ve paid off the loan, you get the funds. This process is reported to the credit bureaus, helping to improve your credit score.
How Does It Work?
Getting started with Self - Credit Builder is a breeze. You download the app, sign up, and choose a credit-building plan that fits your budget. The app offers a variety of plans, so whether you’re a newbie or a seasoned credit-builder, there’s something for everyone. Payments are automated, which is a lifesaver for those of us who forget to pay bills on time. Plus, the app sends you reminders, so you’re always on track.
The best part? You can monitor your credit score within the app. It’s incredibly satisfying to see your score inching upwards as you make your payments. And the sense of accomplishment when you finally unlock the funds at the end of your payment schedule? Priceless!
Is It Worth the Download?
If you’re serious about improving your credit score and don’t mind a bit of delayed gratification, Self - Credit Builder is definitely worth a shot. It’s user-friendly, the interface is clean and intuitive, and the customer support is top-notch. I had a few questions when I first started using the app, and the support team was quick to respond and incredibly helpful.
However, like any tool, it’s not a magic bullet. You need to be committed to making those monthly payments on time. But if you stick with it, you’ll likely find your credit score in a much better place than when you started.
In conclusion, if you’re looking for a practical, effective way to build your credit, Self - Credit Builder might just be the perfect app for you. Give it a try, and you might find yourself pleasantly surprised by how much you enjoy the process of improving your financial health. Happy credit building!
Who benefits most from this approach?
I’d consider it most carefully if I’m new to credit, have had difficulty establishing a payment record, and can commit to a recurring amount without borrowing against next month’s essentials. The practical value is not simply that an account exists; it is that a repayment habit can be made visible over time. Someone who already pays a manageable credit card in full may get more value from keeping that routine than adding another account and another due date.
It may also suit a person who likes having a defined endpoint and a savings outcome attached to the effort. Because the funds are not available at the start, the structure can discourage treating the loan as extra spending money. That same structure is a drawback if flexibility matters more than discipline. Before enrolling, I’d ask myself whether I would still be comfortable with the plan if an unexpected expense came up during the repayment period.
How it compares with familiar alternatives
Compared with using a standard credit card, this approach avoids putting everyday purchases on a revolving balance, but it does not provide the same immediate purchasing flexibility. A card can be useful for someone who already understands statement balances and can pay reliably; it can be costly or stressful for someone likely to carry a balance. Self’s installment structure is a different kind of commitment, and the held funds mean it should not be judged as a substitute for available credit.
A secured card is another common route people consider. It generally involves access to a card backed by a deposit, while this app’s reviewed approach centers on scheduled loan payments and funds received later. Neither route is automatically better. I’d compare the obligations, accessibility of money, and the habits each product encourages. If my priority is accessible savings, an ordinary savings account is more direct; if my priority is building a payment routine without needing to use a card, Self may be more relevant.
Self is free to download, carries an Everyone age rating, and has a 4.5 average from around 91,000 ratings, with over 1 million installs. It launched on March 30, 2018, and version 6.23.0 runs on Android 5.0 or later. Those details help place it as an established finance app, but popularity cannot tell me whether a particular plan fits my cash flow. I’d still make the decision from the terms and my monthly budget, not from the rating alone.
Small habits that make the plan easier to manage
One useful technique is to treat the due date as a bill that arrives before the actual payment date: check the available balance early, then leave enough room for essential expenses. If income is irregular, I’d be especially cautious about choosing a commitment that only works in a perfect month. A reminder is helpful for attention, but it cannot solve a shortfall, so I would avoid setting the payment amount at the absolute edge of what I can afford.
I’d also keep a simple record of the plan’s schedule outside the app, such as a note in my regular calendar. That is not because the app must fail; it is a low-effort way to see the payment alongside rent and utilities. If the phone is unavailable or I change devices, I can still remember what I committed to and when I need to review the account.
When checking credit progress, I’d focus on the general direction over a reasonable stretch of time rather than reacting to every fluctuation. Credit files can reflect several accounts and events, so a single score movement does not explain the whole story. If the number does not move as expected, I’d first confirm that payments are current and allow reporting time; I would not assume that opening the app more often can accelerate the result.
Questions worth resolving before signing up
Can I get the money immediately? No: the structure described here holds the funds until the repayment schedule is complete, so it is not an option for an urgent cash need. Does having the app guarantee a score increase? No product can make that outcome certain for every person; payment history is one part of a broader credit picture. I’d use the app with a realistic expectation of building a record, not as a promise of a particular score.
What if I miss or cannot make a payment? I’d check the plan’s current terms and contact support promptly rather than guess about consequences or make a second payment to compensate. What if I already have a credit card or another loan? I’d compare the new obligation with what I already manage and avoid stacking payments just to collect accounts. The best next step may be improving consistency with existing bills instead of adding another product.
Self Financial, Inc. makes this app for a focused credit-building use case, and that focus is both its strength and its boundary. It is not a universal fix for credit problems, and it does not remove the need to read the plan details or keep enough money available each month. For people who want a structured installment routine and can wait for the saved funds, it is a credible option to investigate. For anyone who needs immediate access, unpredictable flexibility, or a tool for broad budgeting, I’d look elsewhere first.
My practical verdict
After weighing the workflow against the trade-offs, I’d recommend Self - Credit Builder selectively, not automatically. The app has a clear purpose, a familiar mobile setup, and helpful reminders and score monitoring, but its usefulness depends on choosing a payment commitment that remains comfortable beyond the first month. I’d read the plan carefully, line the due date up with my income, and keep the app as one part of a wider money routine.
Self is free to install, and its current version is 6.23.0, but the important decision is not the download. It is whether a delayed-access repayment plan fits your goals better than a card, a savings account, or simply maintaining the credit accounts you already have. If you can answer that honestly and the schedule works for your budget, I think it is worth exploring. If not, skipping it is a sensible financial choice, not a failure to build credit.
Pros
- Helps improve credit score effectively.
- Easy to use and navigate interface.
- Affordable monthly payments.
- Secure and reliable financial app.
- Automated savings feature.
Cons
- Requires a monthly fee to use.
- Limited customer support options.
- Can't link external bank accounts.
- No immediate credit score boost.
- App notifications can be overwhelming.
Self - Credit Builder & Cards FAQ
What is the main purpose of the Self - Credit Builder app?
The Self - Credit Builder app is designed to help individuals improve their credit scores by offering a credit builder account. It allows users to build a positive payment history without requiring a traditional credit check. By making regular, on-time payments, users can enhance their credit profile, which is crucial for securing future loans or credit cards at better rates.
How does the Self - Credit Builder account work?
When you open a Self - Credit Builder account, you agree to a set loan amount that is held in a secured Certificate of Deposit (CD) account. As you make monthly payments, these are reported to major credit bureaus, helping to build your credit score. Once the loan term is complete, the full amount, minus any interest and fees, is returned to you.
Are there any fees associated with using the Self app?
Yes, there are fees associated with using the Self app. These typically include an administrative fee when opening an account, as well as interest on the credit builder loan. It's important to review all fee structures and terms within the app to fully understand the cost involved in using the service.
Is the Self - Credit Builder app safe and secure?
The Self - Credit Builder app prioritizes user security by employing industry-standard encryption and security measures to protect your personal and financial information. Additionally, as a financial service, Self is subject to regulatory oversight, which adds an extra layer of protection for users. Always ensure your app is updated to the latest version to benefit from enhanced security features.
Can using the Self - Credit Builder app guarantee an improved credit score?
While the Self - Credit Builder app is a tool designed to potentially improve your credit score, it cannot guarantee results. Success depends on making consistent, on-time payments and managing other aspects of your credit profile responsibly. Users should also monitor their credit reports for accuracy and address any issues that may arise to optimize credit improvements.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Self Financial, Inc.
- Package Name
- com.selflender.thor
- Version
- 10.0.0
- Android
- 7.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@self.inc, visit https://www.self.inc, or view the https://www.self.inc/privacy-policy.