Rocco - Fast Cash Advance

- 1.38K Reviews
- 4.2
- Downloads
- 100.00K
- 3.0.0
- Version
Screenshots
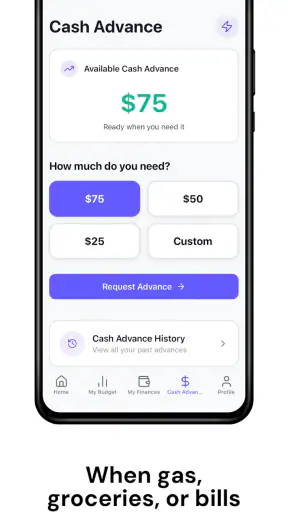
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Quick application process with a simple
- mobile-friendly interface.
- May help cover unexpected expenses between paychecks.
- Clear repayment details are shown before accepting an advance.
- No need to visit a physical branch to request funds.
- Useful budgeting tools can help users track upcoming repayments.
Cons
- Availability and terms may vary by state
- eligibility
- and banking history.
- Fast funding may include express-transfer or other additional fees.
- Repayment on payday can leave less money for essential expenses.
- Not a long-term solution for repeated financial shortfalls.
- Users should review privacy permissions before sharing financial information.
Review of Rocco - Fast Cash Advance Appxis
When an unexpected bill lands before payday, the hardest part is often not finding a financial app; it is understanding what will happen after you request help. I tested Rocco - Fast Cash Advance with that question in mind. This free finance app from Rocco Finance, Inc. presents itself around cash advances and personal finance services, so its appeal is easy to understand: it is aimed at people who need a short-term way to manage a gap rather than a full banking replacement.
My overall impression is cautiously positive. The app is straightforward enough to explore, and its focus is narrower than a traditional budgeting or banking app. That can be useful when the immediate problem is timing. At the same time, a cash advance is not extra income, and the most important part of using an app like this is checking the complete repayment picture before accepting anything. The useful question is not only “Can I get money?” but also “What changes in my next cash-flow cycle?”
From a sudden shortfall to a clearer decision
Starting with the real problem
I would open Rocco when a necessary expense arrives before my regular income, not when I am looking for long-term financial growth. That distinction matters. Someone facing a one-off timing issue may appreciate a focused cash-advance service, while someone trying to reduce debt, build savings, or understand spending habits will probably need a broader personal finance tool as well.
The app is free to install and carries an Everyone content rating, which makes it approachable for a wide audience. It was released on March 14, 2022, and the current version is 3.0.0, with Android support beginning at version 8.0. Those details do not tell me whether an individual request will be accepted, but they do make the basic compatibility question simple for many Android users.
Before opening the application, I would write down three things: the amount needed, the date income is expected, and the bills that must be paid before then. This small preparation is more valuable than rushing through a request. It gives the app a job to solve and makes it easier to recognize when the proposed advance would merely move the same problem a few days forward.
Moving through the initial request
The first useful habit is to treat the opening screens as an assessment rather than a promise. A service built around cash advances needs enough information to determine whether its offering fits the user. I would read each prompt carefully, use consistent information, and avoid guessing just to move faster. A rushed answer can create confusion later, especially if the request needs to be reviewed again.
I also recommend keeping personal details accurate and checking the app name and developer before entering sensitive information. Rocco Finance, Inc. is the developer associated with the application. That simple identity check is worth doing whenever a financial app is installed, particularly if it appears in search results alongside similarly named products.
One practical workflow is to complete the request only after checking the destination account and the upcoming deposit schedule. If the money is intended for an urgent utility payment, for example, I would first confirm the payment deadline and then compare it with the expected repayment timing. This prevents a common mistake: solving an immediate bill while leaving too little for rent, food, transport, or another fixed obligation.
Understanding the handoff from request to offer
The important handoff happens when the app moves from collecting information to presenting the actual terms or next step. This is where I would slow down. I would look for the amount involved, the total amount expected back, the relevant dates, and any conditions attached to the transaction. If those details are not immediately clear, I would not treat speed as a reason to continue.
Rocco’s narrow focus can be an advantage here because it keeps the task centered on the short-term need. In a conventional bank app, a user may have to navigate among transfers, overdraft tools, credit products, and account settings. In a budgeting app, the same situation might produce charts and spending categories but no immediate route to cover the gap. Rocco occupies a different space: it is designed around access to a cash advance and related personal finance services rather than acting as a complete financial dashboard.
That difference also creates a trade-off. A bank may offer a familiar account relationship and clearer visibility into existing balances. A credit card may provide a reusable line, though often with its own costs and repayment risks. A budgeting app may be better for preventing the next shortfall. Rocco can be more direct for a specific cash-flow problem, but it should not replace those longer-term tools.
Checking the outcome before accepting
Once an offer or result is shown, I would take a screenshot or note the key figures for my own records, provided doing so does not expose private information. I would then compare the repayment obligation with my next realistic budget, not with an optimistic version of it. If the advance would leave me short again, the correct outcome may be to stop and look for another solution.
This is also the point where users often wonder whether approval is automatic. I would not assume that installing the app or completing the request guarantees access to funds. Financial services commonly depend on individual eligibility and review, so the responsible approach is to regard the request as an application process until the app clearly shows the final result and the associated terms.
Another question is how quickly money will arrive. The word “fast” describes the app’s positioning, but I would still distinguish between a decision, an approved advance, and money actually appearing where it is needed. Timing can matter when a bill is due, so I would not make an irreversible payment based solely on expecting an advance that has not yet been completed.
Managing the handoff after approval
If the request is approved and the funds become available, the job is not finished. I would immediately update my budget to include the repayment. This is one of the less obvious but most important uses of a cash-advance app: it should become part of a written plan, not a separate event that disappears after the money arrives.
For an everyday example, imagine that a phone bill is due two days before payday and there is no room in the current account. I would check whether the bill can be moved, whether a trusted person can help, and whether the advance’s full repayment fits after payday. If Rocco provides an acceptable route, I would use the money only for that defined need, record the obligation, and avoid treating the remaining balance as spending money.
If the advance is not approved, the same workflow can still be useful. The request may reveal that the amount is too high for the situation or that another option deserves attention. I would then contact the bill provider, ask about a payment arrangement, reduce a nonessential expense, or use an established banking option if its terms are clearer. The value of the process is not limited to receiving funds.
What the app does well in practice
Rocco’s strongest quality is focus. Its store summary describes cash advances and personal finance services, and the experience is best understood through that lens. I do not approach it expecting investment tools, detailed household accounting, or a replacement for a checking account. I approach it when the problem is an immediate mismatch between when money is needed and when income arrives.
The app also has enough public traction to feel like an established product rather than an unknown experiment: it has more than one hundred thousand installs, with a 4.2 average from around four thousand ratings. I treat those figures as context, not as proof that every user will have the same experience. Financial circumstances vary too much for a rating alone to answer questions about eligibility, timing, or suitability.
In my view, the best users are organized people facing a temporary gap who are willing to read terms and plan the next repayment. The worst fit is someone already relying on advances repeatedly, someone who cannot identify the next reliable source of repayment, or anyone looking for a way to increase monthly income. In those cases, a debt counselor, a bank conversation, or a structured budget review may be more appropriate.
Where the flow becomes uncomfortable
The main friction is not necessarily the number of screens; it is the seriousness of the decision behind them. A quick interface can make borrowing feel like an ordinary purchase, even though the consequences reach into the next pay cycle. I would resist any design that encourages tapping through without reading, and I would leave the process if the total obligation or timing was difficult to understand.
There is also a practical limitation in using a specialized advance service: it addresses liquidity, not the cause of a recurring deficit. If groceries, housing, transport, or existing repayments regularly consume more than income, another advance may create a repeating loop. Rocco may help with one isolated interruption, but it cannot by itself repair an unbalanced budget.
Users should also think about privacy and device security in ordinary terms. I would use a screen lock, keep the operating system updated, and avoid completing a sensitive financial request on a shared or unsecured device. These are not special features of Rocco; they are sensible precautions whenever an app handles personal financial information.
Another point of friction is comparison. Because the app is free to download, it is easy to focus on the absence of an installation charge and overlook the financial terms of the service itself. I would compare the complete obligation with alternatives such as a payment extension, an existing overdraft facility, a credit union option, or help from a trusted person. The cheapest-looking route at the beginning is not automatically the least expensive after repayment.
Who should choose it, and who should look elsewhere
I would recommend giving Rocco a careful look if you need a focused cash-advance service, use Android 8.0 or later, and can explain exactly how the advance will be repaid. It is especially suitable for a defined, short-lived timing problem where the amount and date are both manageable.
I would skip it if you want a full budget planner, investment account, everyday banking replacement, or a tool that will automatically solve ongoing overspending. A traditional bank app is likely better for managing existing accounts and transfers. A budgeting app is better for examining spending patterns. A credit product may be more suitable for some users, but only after comparing its cost and repayment structure carefully.
For iPhone users, I would verify platform availability before planning around the service. The Android requirements are clear enough for compatible devices, but the practical decision should always be based on whether the app can be installed and used on the device in hand. I would not wait until an urgent bill is due to discover that a preferred device or account setup is not supported.
My final assessment after following the workflow
Rocco - Fast Cash Advance is a focused finance app rather than a universal money manager. I like that its purpose is easy to understand, and I can see why someone with a temporary cash-flow gap would prefer a direct service over a large banking application filled with unrelated tools. The free entry point and Everyone rating also make it simple to investigate.
My recommendation comes with a firm condition: use it as a planned bridge, not as a recurring income source. Read the complete offer, confirm the repayment schedule, and compare alternatives before accepting anything. If the numbers fit comfortably, the app may be a practical option for a specific emergency. If they do not, the fastest decision is often the one that prevents the next shortfall.
After reviewing the full input-to-outcome journey, I would describe Rocco as useful but situational. It can make a narrow problem easier to address, yet the responsibility remains with the user to understand the handoff from request to repayment. Its real value depends less on how quickly an advance appears and more on whether that advance leaves the rest of your finances stable.
FAQ
What is Rocco - Fast Cash Advance, and how does it work?
Rocco - Fast Cash Advance is a financial app designed to help eligible users request a short-term cash advance through a mobile device. After creating an account, you generally provide personal and financial information so the service can evaluate your request. If approved, the available amount, fees, repayment date, and transfer method are shown before you accept the offer. Approval and funding are not guaranteed.
Who can use Rocco - Fast Cash Advance?
Eligibility depends on factors such as your age, location, identity, income, employment or banking information, and other criteria used by Rocco or its lending partners. Downloading the app does not automatically qualify you for an advance. Requirements may change, so review the current terms inside the application and confirm that the service is available in your state or country before submitting sensitive information.
How much does a Rocco cash advance cost?
The cost can vary according to the amount requested, repayment period, optional services, and the provider or partner handling the advance. Before accepting an offer, carefully check the total repayment amount, service charges, express-transfer fees, subscription costs, late-payment consequences, and any other applicable charges. Do not rely only on the advertised advance amount; compare the full cost with other available options.
When will I receive the money, and how is repayment handled?
Funding speed depends on approval, verification, your bank, the selected delivery method, weekends or holidays, and whether an optional expedited transfer is available. Repayment is normally scheduled for a stated date and may be collected from a linked bank account or another authorized method. Make sure sufficient funds are available and read the agreement carefully to understand extensions, failed payments, and late fees.
Is Rocco - Fast Cash Advance safe to use?
As with any financial application, use Rocco carefully and verify that you are downloading the official version from a trusted app store. Review its privacy policy, permissions, security practices, and the identity of any lending partners before sharing information. Never provide passwords, verification codes, or banking credentials through unofficial messages. A cash advance can be expensive, so use it only after understanding the repayment obligations.


