Robinhood Banking

- 2.33K Reviews
- 4.9
- Downloads
- 100.00K
- 2.18.7
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Commission-free stock
- ETF
- options
- and crypto trading
- Clean interface makes investing approachable for beginners
- Fractional shares allow investing with small amounts
- Automatic recurring investments support consistent saving
- Instant deposits can provide faster access to available funds
Cons
- Limited customer support options may frustrate users needing urgent help
- Crypto assets cannot be transferred to every external wallet
- Advanced traders may find the research tools too basic
- Options trading carries significant risk for inexperienced investors
- Account features and availability vary by state and eligibility
Review of Robinhood Banking Appxis
Robinhood Banking is the kind of finance app that can feel immediately useful because it brings everyday money management and investing into the same familiar space. I found the first impression clean and approachable, especially for someone who wants to check balances, review activity, and think about investing without moving between several unrelated services. It is free, aimed at Everyone, and developed by Robinhood, so the barrier to trying it is low. The more important question, though, is whether it remains useful after the initial curiosity disappears.
My answer is cautiously positive: it can earn a lasting place on your phone if you want a simple connection between banking and investing, but it is not automatically the best financial home for every person. The app’s value depends less on how exciting it feels during the first week and more on whether its layout helps you build a repeatable money routine. I would recommend approaching it as a practical financial tool rather than as a shortcut to better financial decisions.
From first-week appeal to long-term usefulness
Why the first week feels straightforward
The strongest early appeal is concentration. Instead of treating banking as one task and investing as another, Robinhood Banking presents them as parts of one financial workflow. That can make the app especially attractive when you are tired of checking one service for cash and another for investments. Opening the app to review your current position, inspect recent activity, or decide what needs attention feels more direct than managing several disconnected accounts.
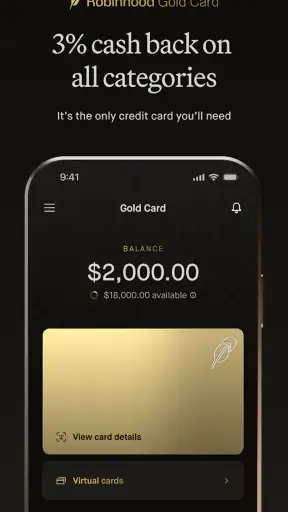
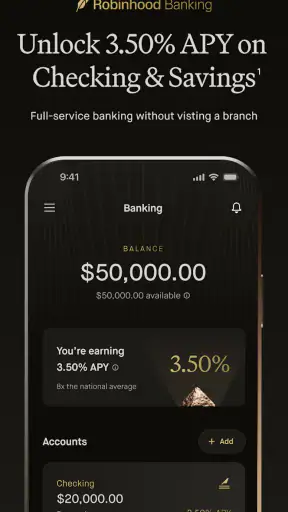
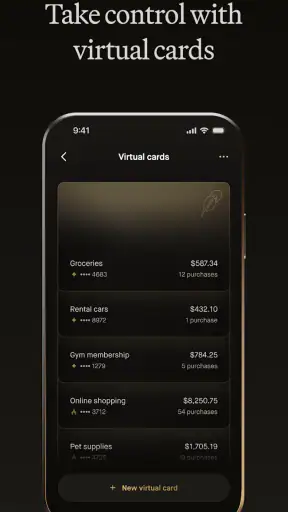
I also appreciate that the product is not positioned as a complicated specialist tool. Its store summary focuses on credit card and banking, while the broader Robinhood experience is associated with accessible investing. That combination gives the app a useful starting point for people who are comfortable with mobile banking but do not want a dense interface filled with technical language.
The first-week test I would suggest is simple: do not judge it by how quickly you can open an account or browse around. Use it during normal moments. Check it before paying a bill, after receiving income, and when reviewing recent spending. Those ordinary interactions reveal whether the app actually reduces friction or merely looks easier during an initial tour.
As a free finance app, it is easy to experiment without committing money to the software itself. That does not mean every financial decision made inside it is risk-free. The distinction matters: the app may simplify access and organization, but it cannot remove market risk, personal budgeting problems, or the need to understand what you are doing.
A realistic everyday routine
Imagine checking your money on a weekday morning. You want to know whether a recent payment cleared, whether your available cash is enough for the week, and whether you still intend to transfer money toward an investment goal. In a fragmented setup, that may require opening a bank app, a card app, and an investment platform. Robinhood Banking is more appealing when it lets you complete that review in one sitting.
The useful habit is not constant monitoring. It is a short, scheduled check with a clear purpose. I would use the app to confirm activity, look for anything unfamiliar, and then leave it alone rather than reacting to every market movement. That approach protects the banking side from becoming tangled with impulsive investment decisions.
One non-obvious advantage of a combined financial environment is that it can expose the trade-off between available cash and money you are willing to invest. Seeing those areas close together may encourage more realistic planning. The danger is the reverse: a convenient view can make invested funds feel like ordinary spending money. I would keep a separate mental boundary between cash needed soon and money intended to remain invested.
What changes after the novelty fades
After the first few weeks, the question becomes whether the app helps you repeat good behavior. A finance app earns long-term space when it makes routine checks quick, keeps important activity understandable, and does not demand attention without a useful reason. Robinhood Banking has a reasonable foundation for that role because banking and investing are connected rather than isolated.
Still, convenience alone is not a complete financial system. If you need detailed household budgeting, extensive bill planning, or a highly specialized banking relationship, you may find the experience narrower than a traditional bank combined with a dedicated budgeting tool. The app makes sense when your priorities are accessibility and consolidation, not when you expect one mobile product to replace every financial service.
I would also avoid measuring its value by how often you open it. In finance, fewer purposeful sessions can be better than constant checking. The lasting benefit comes from a routine such as a weekly activity review and a monthly money check, not from watching balances throughout the day.
Month-to-month value for different kinds of users
For a newer investor, the main monthly benefit is reduced separation between ordinary money and investing decisions. You can develop a consistent review habit without learning several interfaces at once. That is useful if your previous approach was irregularly checking accounts and making decisions whenever something caught your attention.
For someone already comfortable with investing, the value is more conditional. You may appreciate having banking access near your investment activity, but you might also notice the limits of a streamlined experience. Experienced users often care about detailed research, specialized account types, advanced reporting, or highly configurable tools. If those needs dominate your routine, a platform designed specifically around them may be a better choice.
For a person who mainly wants everyday banking, the investment connection may be unnecessary. A conventional bank can be preferable if branch access, a broader range of account services, or an established relationship matters more than having investing nearby. Robinhood Banking is most compelling when the combination is the point, not merely an extra feature you may never use.
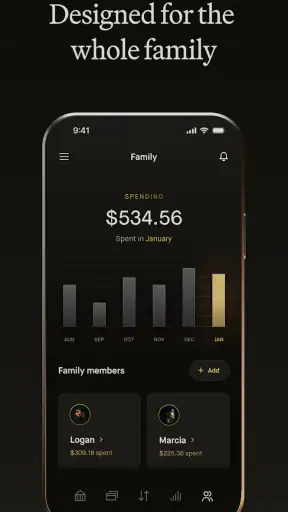
For a couple or household, I would think carefully about visibility and organization before making it the central financial workspace. A simple personal workflow does not automatically translate into a good shared-money workflow. If several people need detailed permissions, coordinated budgeting, or a complete household overview, compare the app with services built around those needs rather than assuming consolidation solves them.
The maintenance burden is low, but not zero
One reason I can see this app surviving beyond the novelty stage is that its basic upkeep should fit into an existing money routine. You do not need to turn it into a daily project. A short review of transactions and balances can be enough for ordinary maintenance, followed by a more deliberate check when your income, expenses, or investment plans change.
The important work happens outside the interface. You still need to recognize your own recurring payments, decide how much cash should remain available, and keep investment choices aligned with your tolerance for loss. A polished mobile screen can make those decisions feel easier than they really are. I would treat the app as a dashboard and execution point, not as a substitute for a personal plan.
Security maintenance also belongs in the routine. Use a strong device lock, keep your phone’s operating system current, and review activity instead of assuming that familiar-looking notifications are automatically harmless. These are not special Robinhood tricks; they are sensible habits whenever an app handles financial information.
The current version is 2.18.7, and the app supports Android 7.0 or later. That makes it accessible to people using older compatible Android devices, although I would still keep the operating system updated whenever the phone allows it. Compatibility is helpful, but financial apps deserve a device environment that is maintained rather than merely supported.
Where recurring value can become fatigue
The first source of fatigue is alertness. When banking and investing appear together, the app can become tempting to revisit even when nothing needs action. That is particularly unhelpful for people who respond emotionally to market changes. I would create a deliberate checking schedule and avoid turning every balance movement into a decision.
The second is the mental blur between spending and investing. A combined experience is convenient, but convenience can hide the fact that these activities have different time horizons. Money needed for rent, food, or near-term emergencies should not be treated like money that can tolerate market volatility. The app may put both within easy reach; your rules need to keep them separate.
The third is the possibility of outgrowing a simplified interface. Beginners often benefit from fewer choices, but those same limits can feel restrictive once their financial life becomes more complicated. If you need deeper analysis, more elaborate planning, or a wider set of banking arrangements, the app may remain useful for a portion of your activity without being the only service you use.
There is also a practical fatigue that comes from duplicated checking. If you keep a traditional bank, a separate card provider, and Robinhood Banking, you may not actually have one financial home; you may have another screen to reconcile. Before moving money or changing providers, list the tasks you perform each month and identify which service handles each one. Consolidation only saves effort when it genuinely removes a step.
How it compares with usual alternatives
Compared with a traditional bank app, Robinhood Banking is more attractive to users who want investing close to everyday money activity. A traditional bank may be the better fit for people who prioritize a broad banking relationship, in-person support, or services that are not centered on a mobile-first investing experience.
Compared with a dedicated investment platform, Robinhood Banking can feel less intimidating and more practical for routine money checks. The trade-off is that dedicated platforms may suit investors who want a more specialized environment and greater depth. I would choose based on the decisions I need to make, not on which interface looks more modern.
Compared with a separate bank plus budgeting app, Robinhood Banking offers less fragmentation but may not provide the same level of detailed spending analysis that a purpose-built budgeting service can offer. If your biggest problem is controlling categories, planning irregular expenses, or coordinating a household budget, a dedicated budgeting tool may deliver more value than combining banking and investing.
Who should use it, and who should skip it
I think Robinhood Banking is a good match for someone who wants a free, approachable route into a combined banking and investing routine. It is especially sensible if you prefer mobile access, want fewer financial apps to check, and are willing to make your own decisions rather than expecting the interface to guide every step.
I would be more cautious if you are prone to frequent trading, anxious about market fluctuations, or likely to interpret easy access as encouragement to act. The app’s convenience is not a reason to increase activity. A calmer, more structured platform—or even a setup that keeps spending and investing physically separate—may be healthier for you.
I would also look elsewhere if your priority is advanced financial planning, complex household management, or a full-service banking relationship. Robinhood Banking can be part of a broader setup, but it does not need to be the answer to every financial problem.
My long-term verdict
Robinhood Banking earns lasting space when it replaces unnecessary switching and supports a repeatable review habit. Its strongest idea is not novelty; it is the practical connection between credit card and banking activity and the wider Robinhood financial experience. For the right user, that connection can make money management feel less scattered.
Its weaknesses appear when simplicity is mistaken for completeness. You still need boundaries between spending and investing, a plan for reviewing activity, and enough financial knowledge to question your own decisions. The app can make those tasks more convenient, but it cannot make them optional.
The app has a 4.9 average from around 25 thousand ratings, with more than two thousand written reviews and over 100 thousand installs. Those figures suggest strong interest and a generally positive reception, but I would not use popularity as a substitute for fit. A person who needs detailed banking services may be happier elsewhere even if the app is well regarded.
My final recommendation is to try it as a focused part of your financial routine. Give it a month, use it for real banking checks rather than casual browsing, and notice whether it removes work or simply adds another place to look. The lasting test is simple: does it help you make fewer, clearer, better-timed money decisions? If the answer is yes, Robinhood Banking is worth keeping. If it encourages constant checking or leaves important planning needs unresolved, choose a more specialized alternative and keep your financial setup intentionally simple.
FAQ
What is Robinhood Banking, and what services does it offer?
Robinhood Banking is the financial-services side of the Robinhood platform, designed to let eligible customers manage spending and cash directly through the Robinhood app. Depending on availability and account eligibility, features may include a spending card, direct deposit, cash management tools, transfers, and access to other Robinhood products. Services, limits, and benefits can vary by location and may change over time.
Is Robinhood Banking a real bank, and is my money protected?
Robinhood is primarily a financial technology company rather than a traditional bank. Banking-related services are generally provided through partner financial institutions, while eligible cash balances may receive applicable protections under the program’s terms. Before depositing money, carefully check the current disclosures in the app, including whether funds qualify for FDIC insurance, the applicable limits, and which institution holds the balance.
Are there fees for using Robinhood Banking?
Many everyday features, such as standard transfers or using an eligible card, may be offered without a monthly maintenance fee, but this does not mean every transaction is free. Fees can apply to expedited transfers, certain ATM usage, international transactions, replacement cards, or other optional services. Review the latest fee schedule before downloading or moving money into the account.
How quickly can I deposit, withdraw, or transfer money with Robinhood Banking?
Transfer speed depends on the method used, the financial institutions involved, verification status, weekends, holidays, and Robinhood’s security reviews. Direct deposits may become available according to the employer or payer’s submission schedule, while standard bank transfers can take several business days. Some users may receive faster access, but availability is not guaranteed for every deposit or account.
What eligibility requirements and limitations should I know about before signing up?
Robinhood Banking availability depends on factors such as age, identity verification, residency, account status, and compliance with applicable regulations. Certain features may be limited to users in supported regions, and Robinhood may restrict transfers, card usage, or withdrawals while reviewing unusual activity. The service is not intended to replace every traditional bank feature, so confirm eligibility and current terms first.


