Quicken: Intelligent Money

- 1.36K Reviews
- 4.6
- Downloads
- 500.00K
- Varies with Device
- Version
Screenshots
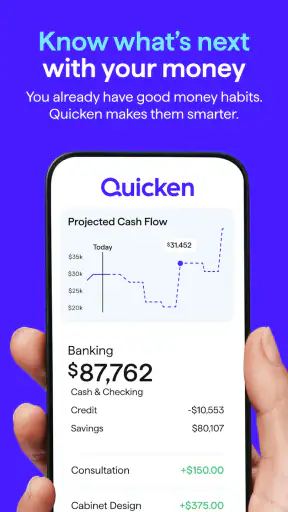
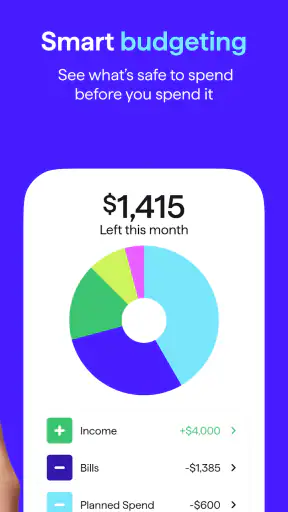
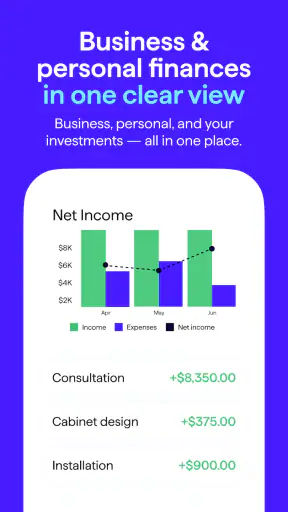
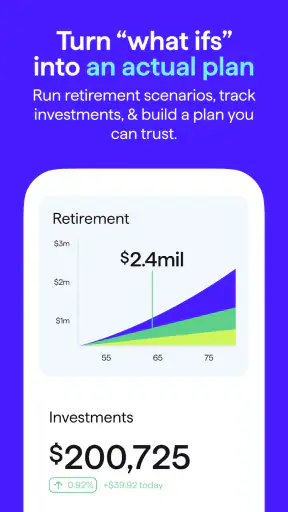
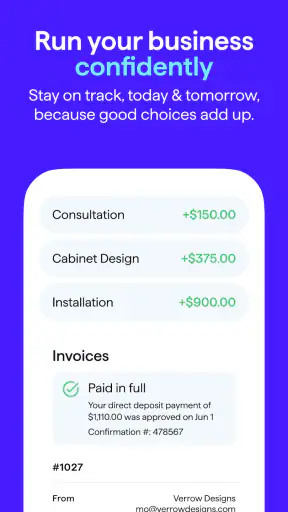
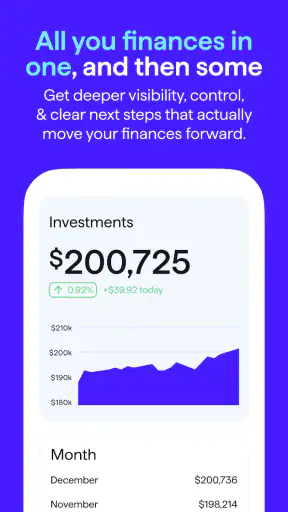
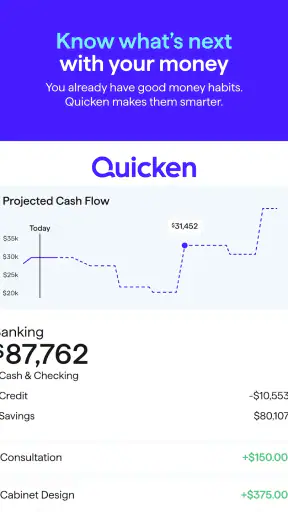
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Clear spending insights help identify where your money goes.
- Useful budgeting tools support better control of monthly expenses.
- Bill reminders can help reduce the risk of missed payments.
- Syncing financial accounts saves time compared with manual tracking.
- Reports make it easier to review progress toward financial goals.
Cons
- Some features may require a paid subscription after the trial period.
- Account syncing can occasionally fail and require reconnection.
- Not every bank or financial institution may be supported.
- The amount of financial data can feel overwhelming for new users.
- Automatic categorization may need manual corrections for accuracy.
Review of Quicken: Intelligent Money Appxis
I approached Quicken: Intelligent Money as a budgeting tool first, not as a magic solution for financial stress. Its job is to give everyday spending, budgets, and personal finances a more organized home, while also offering tools aimed at small-business users. That combination makes it more interesting than a simple expense notebook, but it also means the experience deserves a careful look before you connect important financial information.
In my experience, the appeal is straightforward: instead of checking several accounts, cards, or spreadsheets separately, you get a place to review the money picture and make decisions from there. The app is free to install, rated for Everyone, and comes from Quicken Inc., a developer with a long association with personal-finance software. It has reached over 500 thousand installs and holds a 4.6 average from around 4.9 thousand ratings, so it is clearly not an obscure experiment.
That popularity is useful context, but I would not treat it as proof that the app is right for every household. Finance apps handle information that can reveal routines, obligations, and business activity. My recommendation is to judge Quicken by the control it gives you during setup and daily use, not simply by its download count or rating.
What the app feels like in everyday money management
The main strength is the way it encourages a regular financial review. I found the most useful habit was not opening it constantly, but choosing a consistent moment to check recent transactions, compare spending with the budget, and decide whether the next few days needed adjustment. That is a more realistic workflow than expecting an app to fix overspending automatically.
Imagine a typical week: rent or a mortgage has already gone out, groceries cost more than expected, and a subscription renews earlier than you remembered. A quick review can show whether the problem is one unusually expensive purchase or a category that has quietly grown. The value is in seeing the pattern soon enough to react, perhaps by delaying a nonessential purchase or moving money between planned categories.
Quicken is also positioned for people who mix personal and small-business finances. That can be convenient for a freelancer or a shop owner who wants a broader view without maintaining completely disconnected systems. At the same time, mixing those responsibilities can create confusion if you do not establish clear categories and review them carefully. I would treat the business tools as a reason to explore the app, not as a substitute for professional accounting advice.
The interface is most helpful when you already know what you want to monitor. A beginner may open a finance app expecting a clean answer to “Can I afford this?” In reality, the answer depends on how accurately you record transactions, how sensible your budget is, and whether you account for irregular bills. Quicken can support that process, but it cannot make incomplete financial habits reliable on its own.
Trust starts before the first useful chart
For me, the trust question begins before budgeting. A finance app may become part of a very sensitive routine, so I would read every connection screen, permission request, and account prompt instead of tapping through automatically. The important point is not only what the app can display, but what I am agreeing to share and which choices remain available afterward.
When an app asks to connect an account, I would check the institution name, the type of access described, and whether the connection is necessary for the task I actually want to complete. If I only need a manual view of spending, I would not rush into broader connections. If automatic updates are central to my workflow, I would still review the wording and keep a record of which accounts I chose to include.
This is also where the free price needs a little context. Quicken can be installed without paying, while in-app purchases range from around ten dollars to over one hundred dollars per item. That makes it important to distinguish between trying the app and committing to paid functionality. I would explore the free experience first, then decide whether the extra tools solve a specific problem rather than buying simply because the app looks comprehensive.
One practical trust habit is to begin with a limited financial picture. I would add the accounts needed to test the budgeting workflow, confirm that transactions appear as expected, and see whether the categories make sense before expanding the setup. This staged approach reduces the chance of creating a complicated, hard-to-audit dashboard on the first day.
Account control matters more than convenience
Financial convenience can become a weakness when it removes too much visibility. Automatic categorization saves time, but I would inspect unusual or high-value transactions rather than assuming every label is correct. A restaurant charge, a business purchase, or a transfer between accounts can affect a budget very differently depending on how it is classified.
My preferred workflow would be to review new transactions in batches. First I would confirm that the merchant and amount look familiar. Then I would correct the category, separate personal activity from business activity where appropriate, and only afterward use the resulting totals for decisions. This is slower than accepting everything at a glance, but it makes the budget more trustworthy.
I would also keep an eye on duplicate-looking entries and transfers. A movement of money between two accounts should not feel like new income or spending. If the app presents anything ambiguously, I would resolve it before drawing conclusions from the monthly picture. That small check is one of the less obvious differences between a useful financial review and a misleading one.
Another sensible control is to keep access organized. If you stop using an account, change your banking arrangements, or no longer need a connection, review the app’s account-management screens instead of leaving old links in place indefinitely. The exact options available can depend on the connection and service arrangement, so I would use the visible controls in the app and confirm the result afterward.
Where sensitive data changes the decision
A personal-finance app can reveal more than individual purchases. Over time, transaction history may expose where you shop, when bills arrive, how often you travel, and which expenses belong to a business. That does not make Quicken unsuitable, but it does mean I would be deliberate about the information brought into the account.
I would avoid adding data merely to make the dashboard look complete. If an old account is irrelevant to the decisions I am making now, leaving it out can make the review clearer and reduce unnecessary exposure. The best setup is not always the one with every possible account; it is the one that supports a specific financial routine without creating noise.
Shared finances require extra care. If several people use the same device or household account, I would think about who can open the app and what financial details become visible in notifications, recent screens, or summaries. A budgeting tool can be perfectly useful for a couple while still requiring an agreement about access and privacy.
Small-business use raises a separate issue. A freelancer may want business expenses beside personal spending, but that convenience should not replace careful records, receipts, or advice about tax treatment. I would use the app to organize and review activity, then maintain whatever supporting documentation my local rules or accountant require. The app’s broader scope is helpful, but it does not turn a budgeting workflow into formal compliance.
I would also be cautious on shared or public devices. Even when the app itself offers account controls, the surrounding environment matters: saved credentials, unlocked screens, and device notifications can expose information. A strong financial habit includes protecting the phone or tablet, not just evaluating the app’s menus.
How much control does the user really have?
The app is most rewarding for people willing to participate in the process. I like tools that show me where money went and let me correct the picture, but I do not want to surrender all judgment to automation. Quicken works best when I treat its categories, budgets, and summaries as working tools that deserve occasional review.
A useful monthly routine would be to set the budget around known obligations first, then account for flexible spending, and finally leave room for irregular costs. After that, I would compare the plan with real transactions and adjust the next period based on evidence rather than guilt. If a category is consistently unrealistic, changing it is more helpful than repeatedly “failing” against the same target.
For business users, I would create a simple naming and categorization rule before entering lots of activity. Decide what counts as business-related, how reimbursements will be treated, and how transfers will be recognized. Consistency matters more than a sophisticated-looking structure because later reviews depend on being able to understand why an item was classified a certain way.
I also appreciate that a finance app should allow a user to remain skeptical. If a total looks wrong, I would investigate the underlying transactions instead of trusting the headline number. If a connection behaves unexpectedly, I would pause and review the account settings. The ability to stop, inspect, edit, or remove information is more important to me than having the most automatic experience possible.
Where it beats simpler alternatives, and where it does not
Compared with a basic notes app or spreadsheet, Quicken offers a more finance-focused environment for budgets and transaction review. A spreadsheet can be wonderfully flexible, but it depends on manual upkeep and can become fragile when several accounts or business expenses enter the picture. Quicken is the better fit if you want a dedicated system and are prepared to maintain its categories.
Compared with a lightweight expense tracker, it may feel broader and more involved. That is an advantage when you want personal finances and small-business activity considered together. It is less attractive if all you need is a quick list of cash purchases or a simple weekly spending limit. In that case, the extra structure may feel like work rather than help.
It also differs from a bank’s own app. A bank app is usually the natural place to check balances and transactions for that institution, while Quicken is intended to help organize a wider financial view. I would use the bank’s app as the source for confirming an account event and Quicken as the place for broader budgeting and planning. Neither should automatically replace the other.
For someone who wants detailed accounting, invoicing, payroll, or formal business reporting, I would look at specialized accounting software instead. Quicken’s small-business angle can make it useful for a modest operation, but a growing company may need stronger controls and workflows than a personal-finance-centered app provides. Choosing the narrower tool is not a failure; it is often safer than forcing one app to cover every financial responsibility.
Who should install it, and who should skip it?
I would recommend trying Quicken if you want one place to review budgets and personal finances, especially when your needs extend beyond a single bank account. It is also worth considering if you are self-employed and want personal and small-business money organized within the same general environment, provided you are willing to keep the categories disciplined.
I would be more hesitant for someone who dislikes reviewing transactions or expects automatic budgeting to work without corrections. The app can become cluttered if you connect everything and never clean up categories. It may also be the wrong choice for a person who wants a minimal cash tracker, a strict envelope-budgeting method, or a full professional accounting suite.
Before paying for any in-app option, I would define the missing capability in one sentence. For example, “I need better oversight of recurring household spending” is a useful reason to investigate a feature. “I want the app to feel more complete” is not. The paid range is broad enough that a thoughtful trial matters, particularly for users with modest financial needs.
My cautious verdict after using the workflow
Quicken: Intelligent Money is a capable choice for people who want budgeting and personal-finance organization with room for small-business use. I like its broader purpose more than I would like a bare expense log, and the free entry point makes it reasonable to test. The developer, Quicken Inc., gives the product a clear identity in the finance category, while its Everyone rating keeps it approachable for general household use.
My main reservation is not about the idea of the app; it is about the responsibility that comes with connecting sensitive accounts. I would start small, read each access prompt, inspect categories, and keep personal and business records understandable. Those steps take effort, but they are also what prevent a polished dashboard from giving false confidence.
The app’s 4.6 average from thousands of ratings suggests that many users find the overall experience worthwhile, yet my decision would still depend on the workflow rather than the score. If you want a central budgeting space and are comfortable checking your own data, it is worth exploring. If you want a tiny, manual tracker or formal accounting software, I would choose something more focused.
My final advice is simple: use it as a decision aid, not as an unquestioned financial authority. Keep control of the connections, verify important entries, and pay only when a specific feature earns its place in your routine. With that cautious approach, Quicken can turn scattered money information into a much more manageable review without asking you to give up your own judgment.
FAQ
What is Quicken: Intelligent Money, and who is it designed for?
Quicken: Intelligent Money is a personal finance app designed to help you organize accounts, monitor spending, create budgets, track bills, and understand your overall financial position in one place. It is aimed at users who want more structure than a basic banking app provides, including households managing multiple accounts, recurring expenses, savings goals, and longer-term financial planning.
Can Quicken: Intelligent Money connect to my bank and other financial accounts?
The app can connect with many supported financial institutions, allowing eligible transactions and balances to be imported for easier monitoring. Availability may depend on your bank, account type, region, and the connection method used. Before downloading or subscribing, check whether your institutions are supported, since unsupported accounts may require manual transaction entry or separate tracking.
Does Quicken: Intelligent Money automatically categorize transactions and create budgets?
Quicken can help categorize transactions and organize spending into budget groups, which makes it easier to identify recurring costs and areas where you may be overspending. However, automatic categorization is not always perfect, particularly for unusual merchants, transfers, refunds, or shared purchases. You should review categories regularly and adjust them so reports and budgets accurately reflect your real habits.
Is Quicken: Intelligent Money free to use, or does it require a subscription?
Quicken: Intelligent Money may offer access through a subscription rather than providing every feature completely free of charge. Pricing, trial availability, included tools, and renewal terms can vary by platform, plan, and location. Review the current information in the Google Play Store or Apple App Store before signing up, and pay attention to automatic renewal, cancellation, and refund policies.
Is my financial information safe when using Quicken: Intelligent Money?
Because the app handles sensitive financial information, security should be considered before connecting accounts. Quicken uses account-protection measures and secure connections designed to reduce exposure, but no online service can eliminate every risk. Use a strong, unique password, enable available security features, keep the app updated, and avoid accessing financial data over unsecured public Wi-Fi whenever possible.


