Piere: Budget, Plan, Save

- 188.00 Reviews
- 4.5
- Downloads
- 50.00K
- 6.2.2
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple budgeting tools make it easy to track spending and plan ahead.
- Clear visual summaries help users understand their financial habits quickly.
- Useful savings features encourage consistent progress toward personal goals.
- Clean interface keeps essential money-management tools easy to find.
- Suitable for users who want a lightweight alternative to complex finance apps.
Cons
- Some advanced planning features may require a paid subscription.
- Manual transaction entry can become time-consuming for frequent purchases.
- Limited bank support may prevent automatic syncing for some users.
- The app may feel too basic for users managing complex finances.
- Privacy-conscious users may want more detail about data handling and security.
Review of Piere: Budget, Plan, Save Appxis
Managing money usually fails in the same place: not when you make a budget, but when daily spending slowly pulls you away from it. Piere: Budget, Plan, Save approaches that problem as a finance app built around budgets and automated saving. I found it most useful when I treated it as a routine rather than a one-time setup: define what my money needs to do, check the plan against real spending, and make small corrections before the month gets away from me.
The app is free to download and is developed by UniversTech. It is aimed at Everyone, so the interface and basic idea are accessible even if you have never used a dedicated budgeting tool. At the same time, optional in-app purchases range from $1.99 to $79.99 per item, which is worth remembering before you decide how far you want to take the experience.
Building a money routine that survives real life
Start with a realistic baseline
My first recommendation is not to begin by trying to control every small purchase. The better starting point is to create a simple picture of your regular obligations, flexible spending, and savings intention. Piere works best when the budget reflects the way you actually live. If you set an unrealistically strict limit, every ordinary expense looks like a failure and the plan becomes something you avoid checking.
A practical first session is to identify the payments that must happen, the spending that changes from week to week, and the amount you want to move toward savings. That separation gives the app a useful job. It is not merely recording what happened; it is helping you decide what each part of your available money should accomplish.
I also prefer reviewing a budget after a short period of ordinary use instead of endlessly perfecting it before starting. A budget based on guesses can be adjusted. A budget that never leaves the setup screen cannot teach you anything about your habits.
Use the app before the decision, not only after it
Many people open finance apps after spending, when the only possible action is to feel guilty or move numbers around. A stronger habit is to check the plan before a predictable decision: a grocery trip, a subscription renewal, or a weekend with several social expenses. That turns Piere into a planning tool rather than a digital receipt drawer.
In an everyday scenario, I might look at the month before ordering takeout near the end of a busy week. If flexible spending is already under pressure, the useful answer is not necessarily “do not spend.” It may be to choose a cheaper option, postpone another purchase, or reduce the number of unplanned expenses that follow. The value is in seeing the trade-off while there is still time to act.
Let automation support a decision you already understand
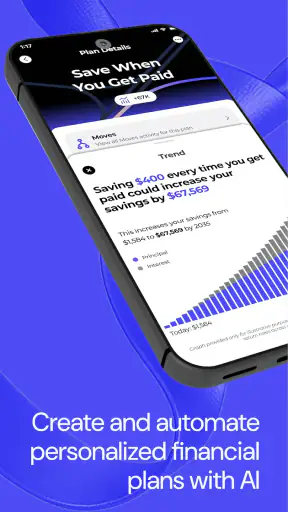
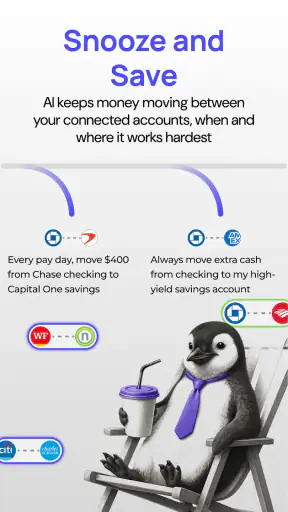
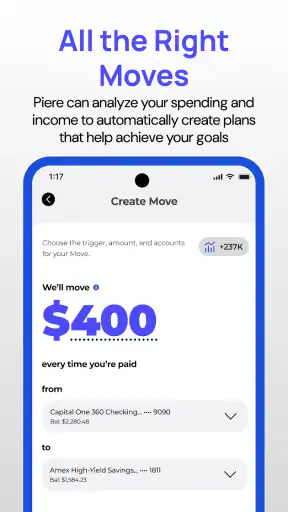
The saving automation is attractive because it can reduce the number of moments when I need to rely on willpower. However, automation should follow a clear plan. I would not switch it on simply because automatic saving sounds convenient. First decide what amount is comfortable, what the money is for, and how often the plan should be checked.
The strongest workflow is “plan first, automate second, review regularly.” That order matters. Automatic movement toward savings can be helpful for someone who spends whatever remains in an account, but it can create friction for someone whose income changes sharply or whose bills arrive irregularly. In those cases, a manual review before committing to a transfer is safer than treating automation as magic.
Settings worth checking before relying on the plan
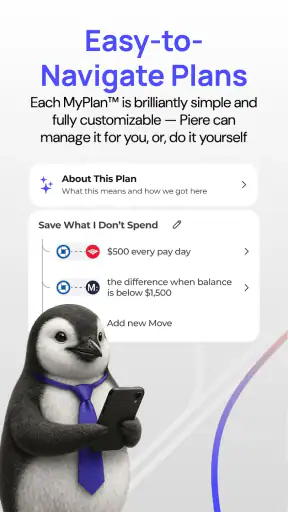
A finance app becomes more useful when its basic setup matches your real situation. I would spend time checking the budget structure, the saving target, and any options connected with recurring financial behavior. The goal is not to create a complicated system. It is to remove ambiguity so that the numbers answer practical questions instead of forcing you to interpret them every time.
Pay particular attention to how you distinguish fixed commitments from adjustable categories. Rent, insurance, and regular debt payments behave differently from dining, entertainment, or shopping. If they are all treated as one undifferentiated pool, the budget may look tidy but offer little guidance. Separating them makes it easier to see which decisions are genuinely available to you.
I would also check the app after your first complete spending cycle. A category that seemed reasonable during setup may be too narrow in practice, while another may be so generous that it hides a problem. This second review is more valuable than repeatedly adjusting the plan based on assumptions.
Keep the saving target connected to a purpose
Saving is easier to maintain when the target has a job. A general “save more” intention is vague, while a reserve for an upcoming bill, a planned purchase, or a cushion for unpredictable months gives the automation context. Piere’s saving focus makes more sense when you use it to reinforce a specific priority rather than treating every saved amount as an abstract victory.
There is also a useful trade-off here. A larger automated amount can make progress visible sooner, but it may leave too little flexibility for ordinary surprises. A smaller amount that remains comfortable can be more sustainable. I would rather keep a modest plan running consistently than create an ambitious one that has to be interrupted whenever life becomes expensive.
Faster patterns for people who dislike constant tracking
You do not need to inspect a finance app after every transaction to benefit from it. A repeatable weekly check can be enough for many users. I like a short review that asks three questions: what changed, which category is under pressure, and what decision should be different next week? This keeps the app connected to behavior without turning budgeting into a second job.
Another efficient pattern is to review upcoming obligations before making discretionary plans. That prevents the common mistake of treating the current balance as spendable money when part of it is already committed. The app is most helpful when it changes the timing of a decision, not merely when it reports that the decision was expensive.
For couples or households, the useful conversation is often about priorities rather than individual purchases. One person may focus on keeping flexible spending predictable while another cares more about building savings. A shared budget discussion can expose that difference early. Piere can support the planning conversation, but it cannot replace agreement about whose goals come first.
Use small corrections instead of dramatic resets
When a month goes wrong, I would avoid deleting the whole plan and starting again. Look for the specific pressure point. Was the problem a single unusual expense, an underestimated category, or a repeated habit? Each cause deserves a different response. A one-off event should not automatically produce a permanent cut, while a recurring overspend should not be dismissed as bad luck.
This is one of the less obvious advantages of a budget-and-saving workflow: it encourages diagnosis. If you only look at the final balance, you see the result but not the pattern. If you use the app to compare your intention with your behavior, you can decide whether to change the target, the category, or the habit itself.
Where the approach can feel limited
Piere is not the right choice for everyone. If you want a highly detailed accounting system with extensive manual controls, complex investment analysis, or deep business bookkeeping, a more specialized finance product may suit you better. This app’s appeal is its focus on planning and saving, not on replacing every financial tool you might use.
It can also feel demanding if you expect automation to remove all responsibility. A budget still depends on sensible categories and regular attention. Automated saving still needs enough room in your finances. If your income is unpredictable, your bills change frequently, or your accounts are already difficult to reconcile, you may prefer a simpler manual method until your financial picture is clearer.
The optional purchase structure is another point to consider. The app is free, but some users may encounter paid items as they explore it. I would begin with the free experience and decide whether additional spending genuinely improves your routine. Paying for more capability is only worthwhile if it saves you time or helps you follow through; it should not become another recurring financial decision you make without checking the value.
What the current release means in practice
The current version is 6.2.2, and the app requires at least OS 10. That makes compatibility an important first check for anyone using an older phone or tablet. On supported devices, the experience is aimed at ordinary personal finance rather than a niche professional audience, which is consistent with its Everyone content rating.
Its adoption is also large enough to suggest that it has moved beyond being an obscure experiment: Piere has over 50 thousand installs, with a 4.5 average from around 473 ratings and 188 written reviews. I would treat that as useful context rather than proof that it will fit every financial situation. A popular budgeting style can still be wrong for someone who needs granular accounting or prefers to manage everything in a spreadsheet.
Who should use it, and who should skip it?
I would recommend Piere to someone who wants a clearer monthly plan, tends to spend whatever is available, or has good intentions about saving but struggles to make them consistent. It is especially suitable for users who appreciate a guided routine: establish limits, connect spending with priorities, and use automation to reduce repeated decisions.
I would be more cautious about recommending it to someone who dislikes financial automation, has highly irregular cash flow, or wants complete control over every entry and calculation. That person may be happier with a spreadsheet, a bank’s basic budgeting tools, or a specialist application designed for detailed manual tracking. The best alternative is not always the most feature-rich one; sometimes it is the system you will actually maintain.
My verdict after using the workflow
What I like about Piere is the connection between budgeting and saving. Many finance apps show spending clearly but leave the user to decide what to do next. Here, the intended experience is more active: make a plan, let a saving routine support it, and return often enough to correct course. That makes it practical for building consistency, provided the initial setup is honest.
My main reservation is that automation can create false confidence. A neatly organized plan does not guarantee that the numbers are comfortable, and an automatic saving action does not make an unstable budget stable. I would use the app as a decision aid, not as a substitute for checking bills, understanding cash flow, or keeping a small margin for surprises.
Overall, I think Piere: Budget, Plan, Save is a good fit for people who want a focused personal finance companion rather than a full accounting suite. Its free entry point makes it easy to try, while its optional purchases mean you should evaluate the added value before paying. If you build a weekly review, keep categories realistic, and automate only what your finances can comfortably support, it can turn vague saving intentions into a repeatable habit.
FAQ
What is Piere: Budget, Plan, Save, and who is it designed for?
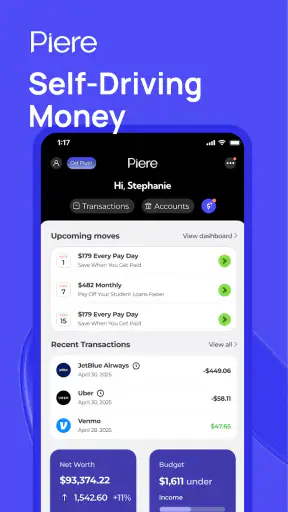
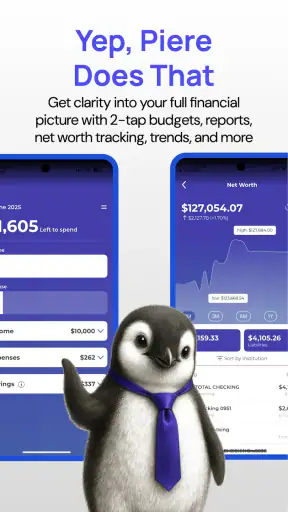
Piere: Budget, Plan, Save is a personal finance app designed to help users organize their money in one place. It can be useful for people who want to track spending, review account balances, create a budget, plan upcoming expenses, and work toward savings goals. The app is especially suitable for users looking for a simpler overview of their finances rather than managing several separate banking and budgeting tools.
How does Piere connect to my bank and financial accounts?
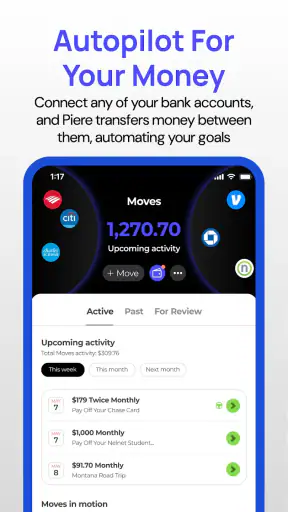
Piere generally works by allowing users to connect eligible financial accounts through a secure account-linking service. After authorization, the app can import information such as transactions, balances, and account details to create a consolidated financial view. Availability may depend on your bank, region, and the connection provider. Before using the app, review the requested permissions and confirm that your financial institution is supported.
Can I create budgets, track expenses, and set savings goals in Piere?
The app is built around budgeting and financial planning, so users can typically categorize spending, monitor where money goes, and compare expenses with planned limits. It may also help organize savings objectives and provide a clearer picture of future finances. However, automatic categorization is not always perfect, and you may need to edit categories or transactions manually to keep your budget accurate.
Is Piere: Budget, Plan, Save free to use?
Piere may offer access to some features at no cost while reserving additional tools or advanced functionality for a paid plan, depending on the current version and your location. Pricing, trial periods, and subscription terms can change, so check the app’s official store listing before downloading. If you start a trial, read the renewal date and cancellation instructions carefully to avoid unexpected charges.
Is my financial information safe when using Piere?
Because Piere handles sensitive financial information, security and privacy should be considered before connecting any accounts. The app may use encrypted connections and third-party financial-data providers, but no online service can guarantee zero risk. Read the privacy policy, understand how data is collected and shared, enable device security such as a passcode or biometrics, and disconnect accounts if you stop using the service.


