Payday Advance Borrow Money

- 194.00 Reviews
- 4.7
- Downloads
- 100.00K
- 1.2.1
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Quick application process with minimal paperwork
- Useful for handling urgent
- unexpected expenses
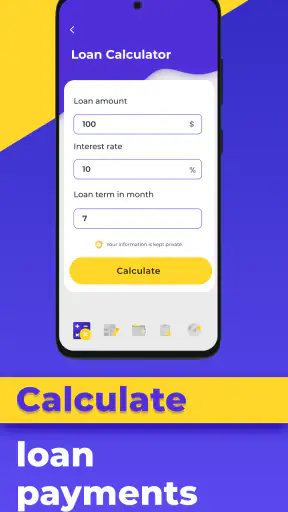
- Clear repayment schedule shown before accepting an offer
- Funds may arrive quickly after approval
- Convenient access from a mobile device
Cons
- Loan availability and terms vary by state and eligibility
- Interest and fees can make borrowing expensive
- Late payments may lead to additional charges
- Not suitable as a long-term financial solution
- Requires access to personal and financial information
Review of Payday Advance Borrow Money Appxis
Payday Advance Borrow Money is a finance app built around one focused task: helping people look for a suitable payday cash advance from a phone. I approached it as a practical borrowing tool rather than a full budgeting platform, and that distinction matters. Its purpose is narrow, so the useful question is not whether it can replace every money app, but whether its loan-search workflow fits the moment when you need to explore short-term borrowing options.
The app is free to install, has an Everyone age rating, and comes from developer Shpuryk Sergii. It has reached over 100 thousand installs and holds a 4.7 average from around 3.2 thousand ratings, which suggests that many people find the basic experience approachable. I would still treat those numbers as a starting point, not as proof that a loan is suitable for every user. Borrowing decisions need more care than downloading an app.
How Payday Advance Borrow Money feels when a connection matters
The most important part of using this app is the network-dependent nature of a loan search. A cash-advance service relies on current information, and that means the experience is naturally tied to connectivity. When I am on a stable mobile or Wi-Fi connection, the app’s purpose is clear: open it when I need to investigate an advance, review what is presented, and decide whether continuing makes sense. It is not the sort of finance tool I would casually browse in airplane mode or in a place where the connection keeps dropping.
This has a practical consequence that is easy to overlook. A slow connection can make a financial decision feel more urgent than it really is. If a page takes time to load, I might be tempted to tap repeatedly, switch screens, or assume that a request failed. My advice is to wait for each screen to finish before trying again. In a borrowing context, duplicate taps and hurried navigation are avoidable sources of confusion.
I also would not begin an application while moving between weak signals, such as on public transport or while walking through a building with unreliable reception. A better workflow is to start in a stable place, keep the phone charged, and leave enough time to read every displayed condition. Connectivity does not change the cost of borrowing, but it can change how calmly and accurately I review the information in front of me.
One useful habit is to separate research from commitment. I can use the app to understand what kind of advance may be available, then pause before proceeding. That pause is especially valuable if the connection has interrupted a screen or if I am unsure whether the last action went through. Rather than treating speed as the main benefit, I see the app as a way to bring the search process into a mobile setting while keeping the final decision deliberate.
Using it in real mobile situations
The strongest use case is a short, planned session on a personal phone. Imagine an unexpected household expense arriving just before payday. I might open the app at home, check the available path for finding an advance, and write down the important repayment details before deciding what to do. The app is convenient in that moment because I do not have to sit at a desktop computer to begin researching short-term borrowing.
That convenience can also become a weakness. Phones encourage quick decisions, especially when I am stressed or distracted. A small screen makes it easier to skim rather than compare. I would avoid using the app while multitasking, during a rushed break, or with someone pressuring me to accept an offer. Finance information deserves the same attention I would give it on a larger screen.
Another realistic situation is using the app while away from home. A stable connection may let me begin the search from a café, workplace, or other familiar location, but public surroundings are not ideal for entering sensitive financial details. Even if the app itself is easy to reach, privacy around the phone still matters. I would use a private setting, lock the device afterward, and avoid leaving the app open where another person can see the screen.
The mobile format is most helpful for access, not for removing the need to compare alternatives. Before using any advance, I would compare the total repayment amount, timing, and consequences of missing a payment with other options available to me. Those alternatives might include delaying a nonessential purchase, asking a bill provider about a different payment date, or using an established bank product whose terms I already understand. The app makes the search more immediate, but it does not make short-term credit automatically affordable.
What to do when a screen stalls or an action is unclear
Connectivity problems deserve a specific recovery plan. If a screen remains incomplete, I would first check whether the phone has a usable connection and then wait rather than repeatedly submitting information. If the app appears to stop responding, I would record mentally which step I reached and reopen it only after the connection is stable. The key point is to avoid assuming that an interrupted screen means nothing happened.
I would also keep a simple note of the stage I was at, without copying sensitive personal information into an unsecured notes app. For example, I might remember that I was reviewing eligibility information rather than submitting anything. This makes it easier to resume carefully instead of starting over in a confused state. If a form resets, I would re-read every field before continuing, because a partially completed process may not preserve what I entered.
There is a second kind of failure that has nothing to do with signal strength: misunderstanding the purpose of the app. Finding a possible advance is not the same as receiving guaranteed money, and reaching a later screen is not a reason to accept terms without reading them. I would treat every step as an information checkpoint. If the wording is unclear, I would stop and seek clarification through the appropriate channel rather than guessing.
This cautious approach is especially important because the app’s store summary describes a search for a suitable payday cash advance, not a promise that every user will qualify or receive funds. That difference should shape expectations. I like that the app has a defined purpose, but I would not use it as an emergency button that removes the need for eligibility checks, repayment planning, or careful reading.
When the connection returns after an interruption, I would review the current screen from the beginning instead of jumping straight to the next button. I would check whether the displayed amount, repayment information, and personal details still look correct. This takes a little longer, but it is a sensible trade-off when the alternative is submitting something twice or overlooking a changed screen.
Keeping the session focused and data-conscious
Because this is a finance app, I approach data use differently from a casual game or a streaming service. A connection is needed for the app’s central purpose, but I do not need to keep it open continuously. I would open it for a specific task, review the information, and close it when I am finished. That reduces distraction and makes it easier to remember what I actually reviewed.
I would also avoid conducting the process on an unsecured public network when possible. A private connection is a more sensible choice for financial activity, especially if the session involves personal information. The app being free does not mean the financial decision is free of consequences. I would keep the phone’s operating system protected, use a screen lock, and avoid sharing the device during the session.
One non-obvious advantage of a focused app is that it can help me avoid mixing loan research with unrelated browsing. I can set a short checklist before opening it: why I need the money, how much I can realistically repay, and what alternative I have already considered. If I cannot answer those questions, I would postpone the search. This turns the app from a reflexive borrowing shortcut into a controlled research step.
I would be careful with screenshots as well. Saving a screen may seem convenient when comparing information later, but financial details can remain in a photo gallery or cloud backup longer than expected. If I need a reminder, I prefer writing down general figures and deadlines without storing unnecessary personal data. The goal is to preserve the decision-making information while limiting the amount of sensitive material on the phone.
Another useful trade-off concerns convenience versus concentration. A phone lets me check an advance from almost anywhere, but that does not mean every location is appropriate. If I am in a noisy place, sharing a screen, or dealing with an immediate emotional reaction to an expense, I would wait until I can think clearly. The app’s accessibility is valuable, yet accessibility should not be confused with suitability.
Who will benefit, and who should choose another route
I think Payday Advance Borrow Money is best for someone who wants a straightforward mobile starting point for researching payday advances and understands that the research still requires personal judgment. It may suit a user who is comfortable reading financial conditions on a phone, has a stable connection, and needs to explore options without committing immediately to the first possibility shown.
I would not recommend making it the only tool for someone who needs broader money management. It is not the app I would choose for tracking spending, building a long-term budget, organizing savings, or comparing every type of credit in one place. A budgeting app or a bank’s own financial tools may be better for understanding whether the shortfall is temporary or part of a recurring pattern.
It is also not the right first choice for someone who already knows that repayment will be difficult. In that situation, searching for another short-term advance can move the problem forward rather than solve it. I would first look at lower-cost alternatives, speak with the company connected to the bill, or seek trustworthy financial guidance. The app can support a search, but it cannot make an unaffordable repayment plan safe.
Compared with visiting a lender’s website in a desktop browser, the app’s main advantage is convenience and mobility. Compared with a banking app, its focus is narrower and more centered on finding a payday advance rather than managing an existing account. Compared with a general loan-comparison service, I would expect this app to feel more direct, but I would still do my own comparison because a focused interface can make one path feel more attractive than it deserves.
That is the central trade-off I noticed: the app reduces friction at the beginning of the search, while responsible borrowing requires adding friction before acceptance. I would deliberately slow down, read the complete repayment information, and compare the result with alternatives. The best experience is not the fastest one; it is the one that leaves me certain about what I am agreeing to.
Version, accessibility, and everyday practicality
The current version is 1.2.1, and the app supports devices running Android 5.0 or later. That makes it relevant to people using older Android phones, although a compatible operating system does not guarantee that every device will feel equally comfortable for financial tasks. On a smaller or older handset, I would pay extra attention to text, scrolling, and whether a page has fully loaded before moving on.
The Everyone rating makes the app broadly accessible from an age-label perspective, but I would not interpret that as a recommendation for every person to borrow. Financial responsibility depends on income, repayment capacity, and the specific circumstances behind the request. Younger users in particular should involve a trusted adult where appropriate and avoid treating the age rating as evidence that payday borrowing is harmless.
The free download is helpful for trying the app’s interface without paying an installation fee. Still, the absence of a download charge should never be confused with the cost of a cash advance. I would focus on the complete financial terms presented during the process, not on the fact that the app itself costs nothing to install.
In daily use, I would keep the workflow simple: choose a private, well-connected place; decide what information I need before opening the app; read each screen fully; stop if the connection makes the outcome unclear; and leave enough time to compare alternatives. Those steps are more important than tapping through quickly, and they make the mobile format work in my favor rather than against me.
My connectivity verdict
After looking at the app through the lens of real mobile use, I see Payday Advance Borrow Money as a focused gateway to payday-advance research rather than a complete financial safety net. Its free access, clear purpose, broad device compatibility, and strong 4.7 average make it easy to consider when I need a mobile starting point. The developer, Shpuryk Sergii, has kept the concept centered on a specific borrowing need instead of presenting it as an all-purpose money manager.
My recommendation comes with a firm condition: use it as a research step, not as permission to borrow impulsively. A stable connection, a private setting, and a deliberate review process make a meaningful difference. If a page fails, I would pause and verify rather than resubmit. If the repayment plan looks uncomfortable, I would choose a different solution rather than letting the app’s convenience decide for me.
The app is most useful when it helps me investigate a short-term option without replacing my judgment. I would recommend it to a careful adult who understands the risks of payday advances and wants a phone-based place to begin. I would steer someone seeking budgeting, long-term financial planning, or relief from repeated debt toward a different kind of service. In that role, Payday Advance Borrow Money is practical and accessible, but its value depends heavily on how thoughtfully I use it.
FAQ
What is Payday Advance Borrow Money?
Payday Advance Borrow Money is a financial app designed to help eligible users explore short-term borrowing options through a mobile device. It may allow you to review potential loan offers, submit personal and financial information, and manage repayment details digitally. Available services, approval decisions, loan amounts, fees, and interest rates can vary depending on your location, credit profile, income, and the specific lender involved.
Is Payday Advance Borrow Money a direct lender?
Before applying, check whether Payday Advance Borrow Money provides loans directly or operates as a connection service that matches applicants with third-party lenders. This distinction is important because the app itself may not determine your final terms. If you are connected with a lender, carefully review that company’s identity, licensing, privacy policy, annual percentage rate, fees, repayment schedule, and customer support information before accepting an offer.
How much does borrowing through the app cost?
The total cost depends on the lender, the amount borrowed, the repayment period, and your individual application details. A short-term loan can include interest, origination charges, late fees, or other costs, and its annual percentage rate may be significantly higher than traditional credit products. Read the complete agreement carefully and confirm the total repayment amount before submitting your acceptance.
What information is required to apply?
Applicants may be asked to provide identifying details, contact information, employment or income information, banking details, and permission for certain verification or credit checks. Only submit information through the official app or a secure, verified website. Review the privacy policy to understand how your data may be collected, shared, stored, and used by the app or any participating lending partners.
What should I consider before taking a payday advance?
A payday advance should generally be considered only after reviewing less expensive alternatives, such as negotiating bills, using savings, contacting creditors, or exploring a credit-union product. Make sure you can repay the full balance on time without needing another loan. Missing a payment may lead to additional charges, collection activity, or damage to your financial situation, so compare terms carefully and borrow only what you can realistically afford.


