

ONE@Work (formerly Even)
ONE Finance, Inc.Finance
Scanned and Safe · Free
- Rating
- 4.8Out of 5
- Downloads
- 1.00M
- Android
- 7.0
Screenshots
Analysis by Appxis
I judge a finance app partly by how much it asks me to read and remember while I am already trying to sort out money. ONE@Work (formerly Even) is aimed at workers who want a clearer view of pay and a way to manage the gap between earning money and receiving payday. Its focus is practical rather than investment-heavy, which makes it a different kind of tool from a bank app or a full budgeting platform.
Finding your way through money information
Readability is not only about font size; it is also about whether the important information is easy to locate when I need it. The published experience is described as straightforward, with a clean interface, and that sounds well suited to quick checks such as reviewing earnings or looking over a spending snapshot. I would use that kind of layout for short visits rather than expecting to do all my financial planning in one sitting.
ONE@Work is a finance app from ONE Finance, Inc. It is free, has an Everyone content rating, and its current version is 10.106.1. It has a 4.8 average from around 78,000 ratings, with more than a million installs. Those figures suggest that many people have tried it, but they cannot tell me whether it fits a particular employer’s payroll setup or whether its tools match an individual’s needs.
One useful habit is to check the earnings view against a pay statement when one becomes available, rather than treating an in-app estimate as a substitute for payroll records. If the amounts do not line up, I would pause before making a spending decision based on the difference. That small cross-check matters most when a person is planning around a tight balance.
Different ways of using the app
For motor and sensory needs, I would look at the actual screens on the device I plan to use. A clean interface can reduce visual clutter, but it does not by itself establish that every control is easy to reach, that text can be enlarged comfortably, or that the app works with a particular assistive setup. Someone who relies on a screen reader, voice control, captions, or reduced motion should test the key tasks directly before depending on them.
There are also practical differences between checking an app at home and trying to use it during a noisy commute or a rushed break. I would avoid making a sensitive money decision while distracted; instead, check the relevant information when there is time to read it and confirm the details. For someone with limited data access, an older device, or inconsistent connectivity, it is sensible to find out whether the screens they need remain usable in those conditions before making the app part of a payday routine.
The app’s payroll connection is central to its appeal, but it also means the experience depends on the relationship between the user’s work and the app. Before building a budget around early access to pay, I would check whether my employer’s setup supports the features I want and what steps are required to connect payroll. That is a more important first question than deciding whether the interface looks appealing.
More Stories While You Read






What Sets ONE@Work Apart?
When I first stumbled upon ONE@Work, I was intrigued by its promise of financial wellness. Unlike typical payday loan apps, this one offers a unique blend of features. Its primary draw is the ability to access earned wages before payday, but there's so much more under the hood.
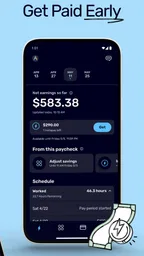
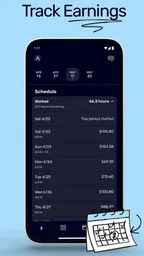
The app integrates seamlessly with your work's payroll systems, allowing you to see how much you've earned in real-time. This transparency is incredibly empowering as it puts you in control of your financial health. No more guessing games about your earnings!
Features That Make a Difference
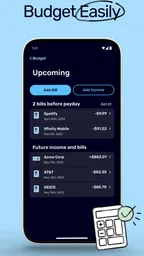
One feature that immediately caught my eye is the budgeting tool. Instead of simply giving you access to your wages, it encourages smart spending. The app provides a snapshot of your financial landscape, breaking down your spending habits. This feature is like having your own financial advisor on your phone 24/7.
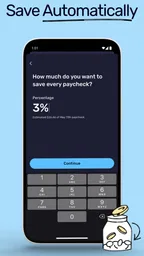
Moreover, ONE@Work offers an automatic savings option. As someone who's struggled with saving consistently, this feature is a game-changer. You can set aside a portion of your earnings automatically, ensuring that your savings grow without you even noticing.
And let's not forget the cash advance feature. Unlike traditional payday loans that come with hefty interest rates, ONE@Work offers this service with minimal fees, making it a much more affordable option in times of need.
Experience and Usability
I found the app pretty straightforward to navigate. The user interface is clean and intuitive, ensuring that even those who aren't tech-savvy won't have a hard time getting the hang of it. From signing up to linking your payroll, the process is seamless.
Customer support is another area where ONE@Work shines. Any questions I had were promptly answered by their support team, making the overall experience quite pleasant. It's evident that they value customer satisfaction.
Making it work in everyday life
The most convincing use case for me is an expense that arrives before payday: a grocery trip, a transit pass, or a bill that cannot sensibly wait. I would first check what I have earned, then compare the amount I need with the rest of my planned spending. If early wage access is available, I would treat it as a timing tool, not extra income. Taking money early can leave less to cover later bills, so the next payday deserves the same attention as the immediate problem.
For example, imagine a worker whose usual grocery budget is nearly used up while payday is still several days away. A quick earnings check can help distinguish a genuinely temporary timing gap from a wider shortfall. If the person chooses an advance, writing down the amount and the expense it covers makes the effect on the next pay period easier to see. If the numbers show that the same gap appears every month, changing the budget or seeking a steadier plan may help more than repeatedly moving pay forward.
The budgeting and savings tools are most useful when they support a simple routine. I would review spending at a regular point in the week, pick one category that is running higher than expected, and decide whether an automatic transfer still leaves enough for necessities. Automatic saving can reduce the effort of remembering, but the setting should be modest enough that it does not force a user to reach for early wages to cover ordinary costs. Convenience is valuable only when it fits the real cash flow.
Where it sits among finance options
Compared with a regular banking app, ONE@Work is more centered on the connection between work, earned pay, and day-to-day money management. A bank app may be the better place to see account balances, pay bills, and manage the account where wages ultimately land. Compared with a standalone budgeting app, ONE@Work’s distinctive angle is its workplace-pay context rather than purely manual planning. These tools can complement one another, but I would not assume one replaces the other.
It also differs from a conventional payday loan in the way it frames access to money: the appeal is access to wages already earned, rather than borrowing against a future paycheck. Still, I would read the terms for any advance carefully, including any fees and the effect on the next deposit. “Affordable” is relative to the alternatives a person actually has, and a small cost can matter when a budget is already stretched. If a user needs a longer-term loan or debt advice, this app is not a substitute for those services.
ONE@Work may suit someone whose employer supports its payroll connection and who wants a compact place to review pay, spending, and saving habits. It is less compelling for a person who wants investment research, detailed household forecasting, or a budget that combines many accounts in one view. Those needs are better served by tools built specifically for them. I would also skip relying on it as a source of emergency cash until I had confirmed which features are available in my own work setup.
Limits worth checking before relying on it
Payroll-linked convenience comes with a trade-off: eligibility and usefulness are tied to work arrangements, so a new job, irregular hours, or a change in payroll details may affect the routine. I would verify the connection before making plans, and keep a separate way to check pay and balances in case the app is unavailable or a detail needs confirmation. A finance app is most helpful when it adds clarity without becoming the only place a person can understand their money.
Accessibility deserves the same practical test. A user can try the core path—opening an earnings view, reading a spending summary, and changing a savings choice—using their usual device settings and assistive tools. If a control is difficult to reach or information is hard to distinguish, that is a meaningful barrier, not a minor inconvenience in a money app. Asking for help through support may clarify a task, but it does not guarantee that every screen will work well for every person.
Context matters too. Someone may prefer not to review pay details on a shared screen or in a public place, especially when they are under time pressure. I would choose a private moment, check the amount carefully, and avoid rushing through a decision just because a break is short. For anyone who shares financial responsibilities, agreeing on how early access or automatic saving fits the household budget can prevent a helpful individual feature from creating confusion later.
Final Thoughts
Overall, ONE@Work is more than just a financial app; it's like having a personal finance assistant in your pocket. It offers a suite of tools that not only provide immediate financial relief but also promote long-term financial health. If you're looking to take charge of your financial future, this app is certainly worth a shot. Plus, with its focus on transparency and affordability, it's a breath of fresh air in the world of financial apps.
In a nutshell, whether you're living paycheck to paycheck or just looking for a better way to manage your money, ONE@Work has got your back. It's time to say goodbye to those financial worries and embrace a more secure financial future.
Who I would recommend it to
My recommendation is strongest for a worker who wants to understand the pay cycle more clearly and will use the budgeting or savings tools as part of a steady routine. The app’s 4.8 average reflects a positive reception, but ratings cannot promise that payroll access, advance availability, or navigation will work the same way for every person. I would start with the basic pay and spending checks, then decide whether the extra tools genuinely make daily decisions easier.
ONE@Work was released on September 6, 2016, and its long-running presence gives it some history as a finance product, though that alone should not be treated as proof that it suits every employer or user. If you need a place to manage a bank account, compare investments, or build a detailed plan across a household’s finances, I would choose a dedicated tool for that job. If your main question is how your work earnings relate to the days before payday, this is the more relevant place to begin.
A practical inclusive verdict
For accessibility and everyday fit, I would describe ONE@Work as promising in its straightforward approach, but something to evaluate through the tasks that matter to you. Try it when you have enough time to read the pay information, use your preferred display and assistive settings, and check the payroll connection before counting on any particular function. That is especially important for anyone who processes information differently, uses a nonstandard input method, or needs a predictable, low-friction routine.
I like the idea of putting earned-pay awareness beside spending and saving tools, because it can turn an anxious guess into a more informed choice. I would not treat an early-access option as a fix for recurring income shortfalls, and I would not recommend depending on the app without confirming that its core tasks work for your setup. Used with those boundaries in mind, it can be a practical companion for workers who want a clearer view of their pay and a little more structure around everyday money decisions.
Pros
- Simplifies financial planning.
- Real-time pay access.
- User-friendly interface.
- Secure data handling.
- Integrates with payroll systems.
Cons
- Limited features for freelancers.
- Subscription fee required.
- Occasional app crashes.
- Limited customer support.
- Only available in certain regions.
ONE@Work (formerly Even) FAQ
What is ONE@Work and how does it function?
ONE@Work is a financial wellness app designed to help employees manage their paychecks and expenses more efficiently. The app offers features like earned wage access, budgeting tools, and savings options. Users can track their earnings in real-time and access a portion of their earned wages before payday, providing flexibility and control over their finances.
Is ONE@Work available for both Android and iOS devices?
Yes, ONE@Work is available for download on both Android and iOS platforms. Users can find the app on the Google Play Store for Android devices and the Apple App Store for iOS devices. This accessibility ensures that employees with different smartphone operating systems can benefit from the app's financial management tools.
How secure is my financial information on ONE@Work?
Security is a top priority for ONE@Work. The app uses advanced encryption technologies to protect users' personal and financial information. Additionally, it complies with industry-standard privacy regulations to ensure data protection. Users can trust that their sensitive information remains confidential and secure while using the app's services.
Are there any fees associated with using ONE@Work?
ONE@Work offers a range of features that may be free or require a fee, depending on the employer's plan. Some employers cover the cost of the app for their employees, while others might charge a minimal fee for certain services. It's advisable for users to check with their employer or the app's terms to understand any applicable charges.
Can ONE@Work help with budgeting and saving money?
Yes, ONE@Work includes budgeting tools that help users track their spending and manage their finances effectively. The app provides insights into spending habits and offers suggestions to improve financial health. Additionally, it features savings options that encourage users to set aside money for future goals, promoting better financial stability and planning.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- ONE Finance, Inc.
- Package Name
- com.even.harmony
- Version
- 10.106.1
- Android
- 7.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@oneatwork.app, visit http://one.app/atwork, or view the https://hello.one.app/e/one-privacy-policy.