

OneMain Financial
OneMain FinancialFinance
Scanned and Safe · Free
- Rating
- 4.7Out of 5
- Downloads
- 1.00M
- Android
- 7.0
Screenshots
Analysis by Appxis
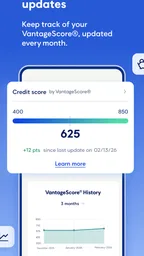
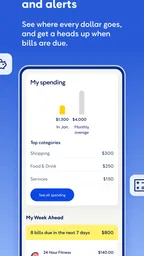
I find a loan app most useful when it makes a specific task easier without turning a sensitive account into a shared household tool. That distinction matters with OneMain Financial: it is a finance app from OneMain Financial for managing a OneMain loan, making payments and keeping an eye on credit. It is free to install, but the account and loan activity belong to the borrower. If you share a phone or tablet, I would treat it as a personal finance app first and a household planning aid only in carefully limited ways.
One borrower, one shared household
Picture a couple planning the month at the kitchen table. One person has a OneMain loan, while both are looking at upcoming bills and deciding which expenses can wait. The app can help the borrower check loan details or handle a payment without opening a laptop, then share only the information the other person needs for that conversation. That is more useful than passing a phone back and forth with the account left open.
I would not use it as a substitute for a joint budget, a shared bill calendar or a general-purpose banking dashboard. Its value is narrower: it puts the borrower’s OneMain loan tasks in one place. For a household, that can make coordination easier, but it does not turn separate accounts into a shared financial record. Agreeing on what to share outside the app is still part of the routine.
Keep the account boundary clear
Before using it on a shared device, I would check whose profile is signed in and make sure the borrower is the person completing account actions. A loan balance, due date or payment is personal financial information, even when the payment affects a household budget. If another person needs to help with planning, the account holder can communicate the relevant detail rather than handing over ongoing access.
This boundary is especially practical when a device is used by several people. Avoid leaving a financial session open for the next person, and be deliberate about where account information appears on screen. I would also keep the phone’s normal screen lock in place and use any sign-in protections the app offers. Those are sensible habits for a finance app, not a reason to assume that a shared device is automatically private.
Coordinate payments without losing track
A useful household workflow is to review the loan alongside other monthly obligations, then decide who is responsible for each action. The borrower can check the account and make a payment through the app, while a partner helps keep the wider budget organized elsewhere. That division keeps the payment decision with the person who owns the account and avoids confusing a reminder with confirmation that a payment has been completed.
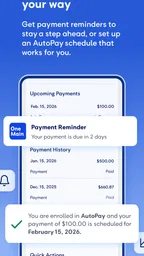
Payment reminders can help when a due date is easy to overlook, but I would still build a personal routine around them: check the account, confirm what action is needed and make sure the payment has actually gone through. A notification is a prompt, not a budget plan. If several adults coordinate household bills, a shared calendar can complement the app without requiring everyone to log in to the borrower’s loan account.
More Stories While You Read






Age, trust and sensible expectations
The app is rated for Everyone, but that rating is about its content, not a recommendation that children manage a loan account. I would keep financial decisions and account access with the adult borrower. A younger household member can learn about budgeting in an age-appropriate conversation without being given access to private loan details or payment controls.
OneMain Financial is listed at a 4.7 average from around 15,000 ratings, with more than a million installs. That level of adoption may reassure someone who wants an established lender’s mobile account tool, but popularity is not a substitute for checking whether the app fits your own loan and privacy needs. It is free, and the current version is 10.18.0; it was released in 2014 and supports Android 7.0 or later. OneMain Financial is the developer.
Easy Navigation and User-Friendly Design
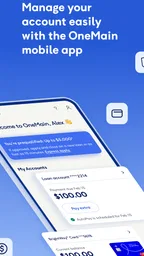
Let's dive right into the interface. The first thing that caught my eye was how simple and easy it is to navigate through the app. Whether you're tech-savvy or someone who's just getting the hang of smartphones, OneMain Financial makes sure you won't get lost in a sea of confusing menus. The design is clean and intuitive, with everything just a tap away.
Loan Management Made Simple
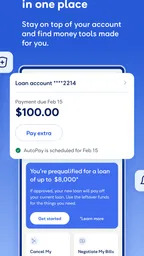
For those of you juggling multiple loans, this app is a godsend. You can easily track your loan balances, payment due dates, and even make payments directly through the app. No need to log in to a computer or call customer service. It’s like having a personal financial assistant right in your pocket.
One feature I found particularly helpful is the payment reminder. It’s a gentle nudge that ensures you never miss a payment. After all, life gets busy, and it's easy to forget those pesky due dates.
Personalized Customer Support
Now, we all know how frustrating it can be to deal with customer support. But with this app, you actually get personalized support tailored to your needs. You can chat directly with a support representative, who can help answer any questions or concerns you might have about your loans. It's like having a friend in the financial world who has your back.
Security You Can Trust
In today's digital age, security is everything. Rest assured, this app takes your security seriously. With advanced encryption and security protocols, you can manage your finances confidently, knowing that your personal information is well-protected.
What it does well—and where I’d look elsewhere
The practical strength here is convenience for an existing OneMain borrower. If you mainly need to check loan information, keep due dates in view, make payments and track credit, a lender-specific app can be quicker than navigating a general banking app or signing in through a browser every time. It keeps those account tasks close together rather than asking you to recreate them in a household spreadsheet.
That focus is also the trade-off. This is not the tool I would choose to compare loans from several lenders, manage every bank account in one overview or build a full household budget. A budgeting app or spreadsheet is better for seeing income and spending across providers; a bank’s app is a better fit for its own deposit and card activity. I would use OneMain’s app for the OneMain relationship and another tool for the broader picture, rather than expecting one app to do both jobs.
If you are considering a loan rather than already managing one, I would separate the app’s usefulness from the borrowing decision. A convenient payment screen does not tell you whether a loan suits your budget. Compare the terms and total cost through the appropriate channels, and decide based on what you can repay. The app’s role is account management, not a replacement for carefully weighing a financial commitment.
A routine that makes reminders more useful
Here is the kind of ordinary situation where I see the app helping: payday arrives, several household bills are due soon, and the borrower wants to check the loan before deciding how much money is available for groceries and other costs. They open the account, review the loan information and due date, then make the payment if that is the plan. Afterward, they update the household budget separately so the other person can see the remaining shared spending amount.
The small but important step is to distinguish “I saw the reminder” from “I handled the payment.” I would make the payment, then verify the account reflects the action before treating that money as settled in the household plan. If a payment looks different from what was expected, it is better to pause and contact support than to make a second payment in a rush. This simple check helps avoid a common coordination mistake: two people each believing the other has taken care of the same bill.
For a borrower who prefers predictable routines, checking the app at the same point in the monthly bill review can be more reliable than relying on a notification alone. If the borrower travels, changes phones or shares a device temporarily, it is worth making sure they can still access their own account before a payment is due. The app is most helpful when it is part of a routine, not the only place where a household remembers its obligations.
Questions I would settle before relying on it
Can another household member use the app to manage the borrower’s account? I would not assume so. Treat the account as belonging to the borrower, and use the app under that person’s own access. If someone else needs to help, agree on a safe way to coordinate rather than sharing a login or leaving a session open.
Does a reminder itself make a payment? No: I would treat a reminder as a prompt to review and act, not proof that money has moved. After making a payment, check the account and keep the household’s separate records aligned. That distinction is particularly important when multiple people are handling bills.
Is it useful if I have loans with several lenders? It can still serve its purpose for the OneMain loan, but it should not be mistaken for a consolidated view of every lender. If comparing several balances or due dates is your main need, a separate budget or bill-tracking method may be more convenient. The app is strongest when your task is specifically tied to OneMain.
Is it right for a household that wants fully shared financial management? Probably not on its own. It can support a conversation about one borrower’s loan, but it does not replace a shared budget or give everyone a common account view. I would choose a broader tool for joint planning and keep this one focused on the borrower’s account.
My household verdict
In summary, OneMain Financial is a fantastic tool for anyone looking to simplify their financial life. From managing loans to receiving personalized support, it covers all the bases. So, if you’re looking for a reliable and user-friendly finance app, give this one a try. You might just find it’s exactly what you’ve been looking for!
My recommendation is more specific: I would try it if I were a OneMain borrower who wants a straightforward way to keep up with loan tasks on a phone. It makes less sense for someone seeking a complete money-management system, a shared household account or a way to compare unrelated lenders. For a shared household, its best role is a private account tool that supports clear conversations—not a replacement for trust, boundaries or a joint plan.
Pros
- User-friendly interface for easy navigation.
- Quick loan approval process.
- Wide range of loan options available.
- No prepayment penalties.
- Online account management available.
Cons
- High interest rates compared to competitors.
- Limited to the U.S. market.
- Requires a hard credit check.
- No mobile app for loan applications.
- Limited customer service hours.
OneMain Financial FAQ
What is OneMain Financial, and how does it work?
OneMain Financial is a personal lending platform that offers loans to individuals with varying credit scores. The app allows users to apply for loans, manage their accounts, and make payments directly from their mobile devices. It provides easy navigation and a user-friendly interface to track loan progress and access customer support.
What are the interest rates and terms offered by OneMain Financial?
OneMain Financial provides personal loans with interest rates that vary based on creditworthiness, loan amount, and repayment terms. Typically, the APR ranges from 18% to 35.99%. Loan terms can range from 24 to 60 months. It's essential to review the specific terms offered during the application process to understand the total cost of borrowing.
Is OneMain Financial safe to use for personal loans?
Yes, OneMain Financial is a reputable lender with a long-standing history in the financial industry. It uses encryption and security protocols to protect users' data and financial information. However, potential borrowers should always review the terms and conditions, and ensure they are comfortable with the lending agreement before proceeding.
Can I apply for a loan with OneMain Financial if I have bad credit?
OneMain Financial does consider loan applications from individuals with less-than-perfect credit. They focus on a variety of factors beyond just the credit score, such as income and financial history, to determine loan eligibility. This makes it a viable option for those who may not qualify for loans from traditional banks.
How can I contact OneMain Financial’s customer service?
OneMain Financial’s customer service can be reached through multiple channels. Users can contact them via phone, email, or through the in-app chat feature for assistance with their accounts or loan inquiries. Customer support is available during regular business hours, and the website also provides additional resources and FAQs for self-service.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- OneMain Financial
- Package Name
- com.springleaf.mobile
- Version
- 10.31.0
- Android
- 7.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at appfeedback@onemainfinancial.com, visit https://www.onemainfinancial.com, or view the https://www.onemainfinancial.com/legal/privacy-policy.