OneBlinc - Financial tools

- 672.00 Reviews
- 4.6
- Downloads
- 100.00K
- 7.12.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Builds credit history through eligible reported payments.
- Offers flexible repayment options for managing short-term cash needs.
- Provides spending insights that can help improve budgeting habits.
- Application process is handled conveniently from a mobile device.
- Useful financial tools are gathered in one app.
Cons
- Availability and features may depend on your location and eligibility.
- Some services may include membership
- transfer
- or other applicable fees.
- Cash advances can encourage borrowing for recurring expenses.
- Credit-building results are not guaranteed and may take time.
- Late or missed repayments could lead to extra costs or credit impact.
Review of OneBlinc - Financial tools Appxis
When an unexpected expense arrives between paydays, the most useful financial tool is often the one that solves a very specific problem without asking you to reorganize your entire life. That is the angle I found most interesting with OneBlinc: it focuses on giving users access to part of their earned wages through a linked account. Rather than presenting itself as a broad budgeting suite, it is built around short-term access to money you have already worked for.
That distinction matters. I would not approach this as a replacement for a bank account, a full budgeting app, or long-term savings plan. I see it as a finance app for a narrow but familiar moment: a bill, transport cost, grocery purchase, or other necessary payment appears before payday. The app is free to install, is rated for Everyone, and comes from OneBlinc, a developer focused on this wage-access experience.
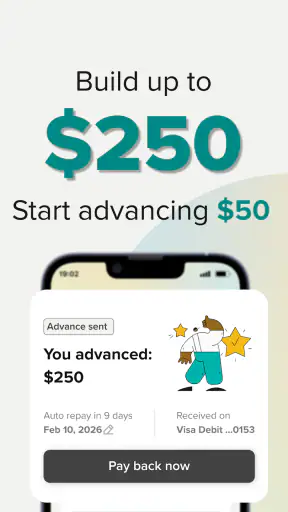
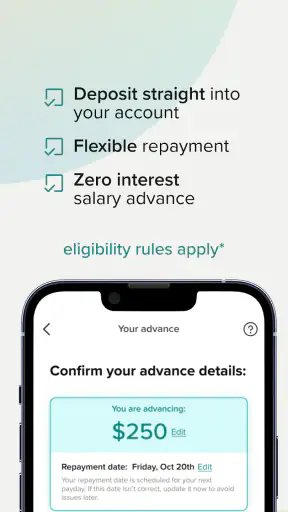
The central promise is access to wages up to 250 dollars directly to a linked account. In everyday terms, the appeal is not simply “getting money quickly”; it is having another way to manage the awkward gap between when an expense is due and when regular pay arrives. That can be genuinely helpful, but only when I use it deliberately and understand the difference between solving a timing issue and solving an income problem.
How wage access feels in real use
A focused tool rather than a complete money manager
My first impression is that the app’s value depends on the user’s situation. Someone looking for spending charts, investment tracking, bill negotiation, or a detailed household budget may find the experience too narrow. The important action here is connecting an account and using the available wage-access option when a shortfall appears. That focused design can be a strength because it keeps the purpose clear.
The store summary describes access to wages through a linked account, and that wording gives the right expectation: the linked account is central to the workflow. I would prepare the account details carefully before starting, use an account that I check regularly, and read every confirmation screen rather than treating the process like a casual transfer. Financial apps deserve that extra pause, especially when timing and account information are involved.
One practical tip is to decide the reason for the withdrawal before opening the app. If I need money for a specific bill, I can request only what addresses that bill instead of treating the available amount as extra spending money. This small habit changes the app from an impulse button into a controlled cash-flow tool. It also makes it easier to judge whether the service actually helped or merely moved the same problem closer to payday.
What the linked-account model changes
Using a linked account makes the experience more direct than asking a friend for money or moving funds between several personal accounts. The benefit is convenience: the money is intended to reach an account I already use. The trade-off is that the user must be comfortable with the connection and attentive to where the funds will arrive.
I would also check the destination before confirming a request, particularly if I maintain separate accounts for bills and everyday spending. Sending money to the wrong account could create a second chore at exactly the moment I am trying to simplify things. This is one of those small workflow details that a short store description cannot communicate but that matters in real life.
The app is available as a free finance application, which lowers the barrier to trying it. Free access should not be confused with free money, though. The useful question is not only whether I can open the app without paying for the download, but also how the wage-access arrangement fits my own repayment or payday cycle and any terms shown during use. I would read those details in the app before relying on the service for a recurring need.
Keeping the request tied to a real need
The strongest way to use this kind of tool is to define a ceiling before requesting anything. For example, if a utility payment is short by a modest amount, I would request enough to cover that gap and stop there. If the request becomes a way to fund restaurant meals, shopping, or several unrelated purchases, the convenience can hide the fact that the next payday has already been partly allocated.
That is the main behavioral trade-off: wage access can reduce stress today while reducing flexibility later. I appreciate that the app addresses a real timing problem, but I would not use it as a routine substitute for an emergency fund. A small reserve, a revised bill date, or a conversation with a service provider may be better for a repeated shortfall.
One realistic payday-gap scenario
Imagine I am paid at the end of the week, but my car needs fuel and I have a necessary grocery trip before then. I could use OneBlinc to access a limited portion of wages through my linked account, handle those immediate needs, and then return to my normal spending plan once payday arrives. In that situation, the app has a clear job: it helps bridge a short interval.
The important part is what happens next. Before requesting the money, I would look at the balance that will remain available after payday-related obligations. If the amount I access today means rent, utilities, or food will be harder to cover later, the request is not really solving the problem. It is only rearranging it. This is why I consider the app most useful for a contained, necessary expense rather than an open-ended cash boost.
For someone paid on an irregular schedule, the same idea may be more complicated. I would be especially cautious if income varies widely, because a request based on an optimistic expectation can leave less room when the actual payment arrives. The app may be convenient, but it cannot remove the uncertainty of an unstable budget.
Where it compares well with usual alternatives
Compared with asking a friend or relative for a small advance, the app offers a more private and structured route. Compared with using a credit card, it keeps the decision tied to wage access instead of encouraging a revolving balance. Compared with a traditional personal loan, it is aimed at a much smaller, shorter-term cash-flow gap rather than a large planned expense.
Those comparisons do not make it universally better. A credit card may be more suitable for someone who already has a controlled repayment plan and needs purchase protection. A savings account is clearly preferable when the money is available there, because using savings does not create the same payday squeeze. A bank transfer between my own accounts is simpler when the funds already exist. And for a large expense, I would look at a proper loan or payment arrangement rather than forcing a wage-access product to do a job it was not designed for.
The app’s advantage is its narrowness. It is most compelling when the amount needed is limited, the expense is immediate, and I know exactly how the next pay cycle will absorb the advance. That is a more useful way to compare it than calling it a universal alternative to borrowing.
Trade-offs I would consider before using it
The first trade-off is timing. Accessing wages early can be reassuring, but it means part of future income is no longer available for future decisions. I would avoid making a request on the same day I am already unsure how to cover the next round of essential bills.
The second is dependence. If I use the app every pay cycle, the feature may become part of my normal income rather than an occasional bridge. That pattern is a warning sign. In that case, I would step back and examine fixed expenses, bill dates, subscriptions, and the amount left after necessities. The app can provide breathing room, but it cannot increase the total income available over time.
The third is account management. A linked-account workflow is convenient only when the destination is correct and accessible. I would keep my account information current, review the details shown before confirming a transaction, and avoid rushing through the process while distracted. These are simple precautions, but financial convenience is safest when paired with attention.
The fourth is expectation. The headline amount is up to 250 dollars, not a promise that every user will receive that full amount whenever they open the app. I would treat the displayed availability and the terms presented in my own account as the deciding information. Planning a bill around the maximum possible amount would be poor budgeting.
Who benefits most from the app
I think the best fit is someone with regular wages, a linked account they actively monitor, and a temporary mismatch between payday and a necessary expense. That person can use the app with a defined purpose and a clear plan for the next pay cycle. The free download also makes it easy to consider without committing to a purchase simply to explore the experience.
It may also suit a user who dislikes relying on family or friends for small emergencies and wants a dedicated place to manage this particular type of request. The app’s finance category is appropriate because its usefulness is tied to cash-flow decisions, not entertainment or general productivity.
I would be more hesitant to recommend it to someone who is already borrowing every month to cover basic living costs. In that situation, early wage access could make the underlying gap less visible. I would also suggest caution for anyone who does not regularly check their linked account, has highly unpredictable income, or needs a large amount for a major purchase. A savings plan, creditor arrangement, bank service, or professional financial guidance may be more suitable depending on the problem.
What I noticed about its maturity and reach
The app was released on February 18, 2025, and the current version is 7.12.0. It supports devices running Android 7.0 or later, which gives it a broad compatibility range for Android users who keep an older phone in service. I would still update the app through the normal store process and make sure the device itself is protected with a lock screen, since the application deals with sensitive financial activity.
Its audience is not tiny: the app has passed 100K installs, with an average rating of 4.6 from around 4.8K ratings. Those figures suggest that many people find the concept useful, while the rating gives me reasonable confidence that the basic experience works well for a substantial group. They do not remove the need to judge the product against my own finances, however. A well-rated cash-flow tool can still be the wrong choice for someone whose issue is persistent debt rather than a short delay in receiving pay.
The Everyone age rating is also consistent with the app’s straightforward financial purpose, though I would still treat any finance application as an adult responsibility in practice. The age label describes content suitability; it does not replace careful reading of account and transaction details.
Small habits that make the feature safer
I would use three habits every time. First, I would name the expense mentally before requesting access: “groceries until payday” is better than “extra money.” Second, I would check the linked destination and the amount twice. Third, I would note how the next payday will be affected, even if that means writing the figure in a basic notes app.
A fourth habit is to review frequency. If I have needed the service once for an unusual expense, that is very different from needing it repeatedly. Repeated use tells me to investigate the budget rather than simply becoming more efficient at requesting early wages. This is a non-obvious but important distinction: the app can be used responsibly while still revealing that my broader financial plan needs attention.
I would also avoid opening the app while shopping online or making nonessential decisions. A tool designed for a shortfall can feel like permission to spend, especially when the process is convenient. Keeping it associated with planned necessities helps preserve its original purpose.
My overall recommendation
OneBlinc is a focused financial app with a clear use case: accessing part of earned wages through a linked account when the timing of an expense does not match the timing of payday. I like that its purpose is easy to understand, and I can see real value in the short-term scenario described above. The free app, broad Android compatibility, and strong average rating make it a reasonable option to investigate for eligible users who need this kind of flexibility.
My recommendation comes with a firm condition: use it as a bridge, not as a second paycheck. The best experience is likely to come from a small, planned request tied to a necessary expense and followed by a realistic look at the next pay cycle. If I needed budgeting tools, long-term borrowing, or help with ongoing financial strain, I would choose a different solution instead.
In the end, the app’s strength is also its limitation. It does one important job rather than trying to manage every part of personal finance. For the right user, that focus can make an awkward payday gap easier to handle. For anyone facing a deeper income-versus-expenses problem, the same convenience may only postpone the decision that really needs attention. Used with a clear limit and a specific purpose, it can be a practical short-term financial tool rather than a habit-forming shortcut.
FAQ
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a financial services app designed to help users manage short-term cash needs and everyday money matters from a mobile device. Depending on eligibility and location, its tools may include paycheck advances, a spending account, budgeting features, credit-building services, and other financial products. Available features, limits, fees, and requirements can vary, so review the current terms carefully before applying.
How does the OneBlinc paycheck advance work?
OneBlinc may allow eligible members to access part of their expected income before payday, which can be useful for handling an unexpected bill or temporary cash shortage. Approval is not guaranteed, and the amount offered may depend on factors such as income, account activity, employment information, and repayment history. Read the advance agreement carefully to understand repayment timing and any applicable costs.
Are there fees or subscription costs when using OneBlinc?
OneBlinc’s pricing can depend on the specific service you choose and your membership status. Some features may involve a recurring membership charge, transaction fees, expedited funding costs, or other charges, while certain options may be free under particular conditions. Before connecting an account or requesting funds, check the app’s fee schedule and confirmation screen so there are no surprises.
Is OneBlinc safe to use with my personal and bank information?
OneBlinc requires sensitive information to provide financial services, which may include identity details, income information, and a connection to a bank account. The app uses security and verification processes, but no online service can eliminate every risk. Download it only from an official app store, use a strong password, enable available security controls, and review permissions and privacy disclosures before proceeding.
Who can use OneBlinc, and what should I know before downloading it?
Eligibility for OneBlinc may depend on your age, residence, employment or income, banking situation, identity verification, and other underwriting or membership requirements. The service may not be available in every country or state, and approval can vary between users. It is also important to remember that financial advances are not free money and should be used only when you understand the repayment obligations.


