Navy Federal Credit Union

- 43.19K Reviews
- 3.7
- Downloads
- 10.00M
- 2026.8.1
- Version
Screenshots
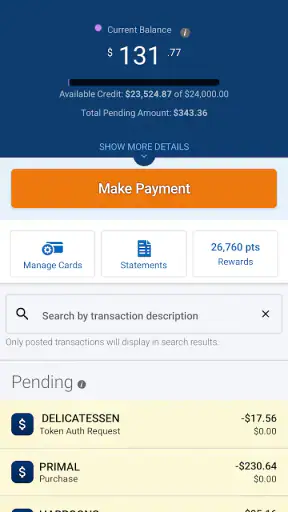
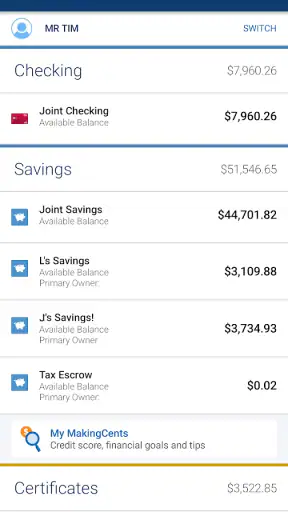
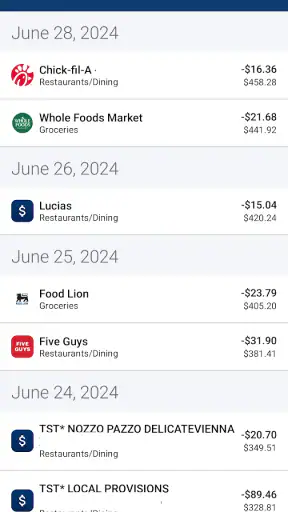
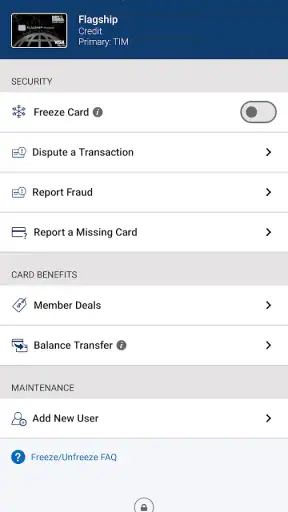
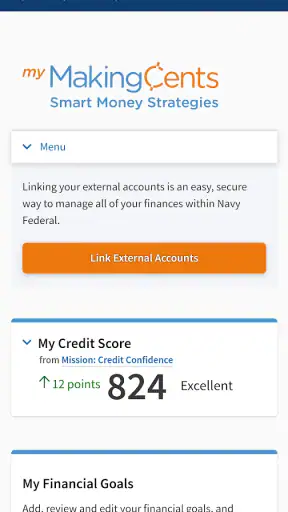
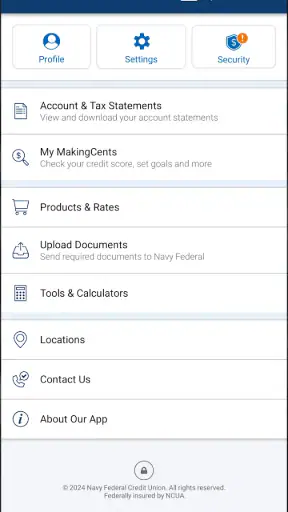
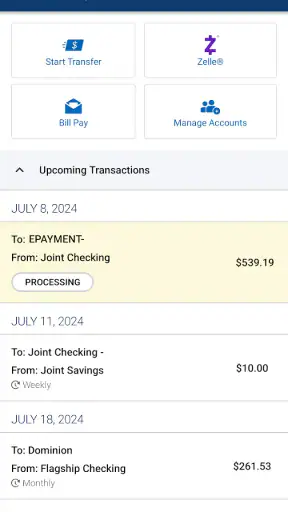
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- No monthly maintenance fees on many checking accounts.
- Strong mobile banking tools for transfers
- deposits
- and bill payments.
- Wide ATM access through Navy Federal and partner networks.
- Competitive rates on select savings
- certificates
- and loan products.
- Helpful membership benefits for military families and eligible relatives.
Cons
- Membership is limited to eligible military groups
- veterans
- and relatives.
- Some features may require additional verification or supporting documents.
- Branch availability is concentrated near military installations.
- Savings rates may vary and can be less competitive than online banks.
- International transactions and certain services may involve extra fees.
Review of Navy Federal Credit Union Appxis
I find finance apps most useful when they reduce small moments of uncertainty: checking whether a payment went through, confirming a balance before a purchase, or spotting a transaction that needs attention. Navy Federal Credit Union is built for that kind of everyday banking, with Navy Federal as its developer and a clear focus on members rather than general-purpose money management. I reviewed it as a mobile banking tool, and my overall impression is practical: it can make routine account tasks convenient, but the first login and any security-related interruption can feel less straightforward than the simple screen design suggests.
The app is free and available to Everyone, which makes it easy to try without adding another subscription to a household budget. It has been available since Jul 29, 2011, and its current version is 2026.8.1 for devices running iOS or Android 11 and newer. Its 3.7 average from around 110 thousand ratings shows a mixed but substantial user experience rather than a universally smooth one. With over 10 million installs, it is clearly used at a large scale, so I would judge it as an established banking companion, not an experimental download.
Where the first session can become frustrating
The biggest difference between installing a banking app and installing an ordinary utility is that installation is only the beginning. You still need to identify yourself, connect the app to your Navy Federal relationship, and pass whatever security checks appear during sign-in. That is where I would expect most new users to slow down. A person who assumes the app will behave like a basic balance widget may be surprised that account access depends on accurate credentials and a reliable verification path.
I recommend starting when you have time to finish the process rather than while standing in a checkout line. Keep your usual Navy Federal sign-in details available, make sure the phone has a stable internet connection, and avoid repeatedly guessing if a password or security answer is uncertain. Banking access is not the place to experiment with multiple combinations. A careful first attempt is usually less stressful than creating a lockout and then trying to solve it under pressure.
Another common point of friction is confusion between the app and the account itself. If a balance looks different from what you expected, the cause may be a pending transaction, a recent transfer, or normal posting timing rather than a display failure. I would first refresh the account view, then compare the transaction list with the receipt or confirmation you have. The useful habit is to treat the app as a current account window, not as an instant replacement for every stage of bank processing.
The most important setup rule is simple: complete identity and sign-in checks before you need the app urgently. That one step changes the experience considerably. Once access works, a quick balance check or transaction review feels routine; when access has never been tested, a late-night payment question becomes much more difficult.
Checks worth making before you blame the app
Before troubleshooting, I would check the basics in a deliberate order. Confirm that the device meets the minimum operating-system requirement, that the app is updated through the normal app store, and that the phone has enough connectivity to load account information. If you are using a weak public Wi-Fi connection, switching to a trusted mobile connection can help distinguish a network problem from an account problem.
I would also look at the phone's date and time settings. Secure sign-in systems can behave strangely when a device clock is badly out of sync, and correcting the automatic time setting is a harmless first check. If the app opens but a particular page does not load, close it fully and reopen it once rather than repeatedly tapping the same control. Repeated attempts rarely improve a stalled session and can make it harder to tell what actually happened.
Storage is another overlooked detail. A phone that is nearly full may update apps poorly or behave unpredictably when opening a secure session. Freeing a little space and restarting the device is a sensible general step. I would not immediately uninstall the app, though, because removing it can erase local convenience settings and force another sign-in without fixing an account-side issue.
For privacy, I prefer testing the app on a personal device rather than a shared phone. I would avoid saving credentials in places other people can see, and I would not use an unfamiliar device for sensitive banking unless there is a clear reason. These are not glamorous tips, but they matter more than repeatedly reinstalling the application.
What to do when sign-in or loading fails
If sign-in fails once, I would pause and verify the details instead of assuming the service is down. Check capitalization, keyboard substitutions, and whether the phone has inserted an unwanted space. If a verification message is expected, give the process a moment and confirm that the contact method being checked is still accessible. Do not share a one-time code with anyone who contacts you unexpectedly while you are trying to log in.
If the app opens normally but account information remains unavailable, compare the result with another trusted way of reaching Navy Federal, such as the institution's official support route. The point is not to bypass security; it is to establish whether the issue follows your account or only this device. If other official access works, the problem may be local to the app, network, or phone. If every official route has trouble, contacting Navy Federal is more appropriate than continuing to reset the app.
I would be especially cautious with an unfamiliar warning, a request for unusual personal information, or a message directing me away from the normal sign-in process. A banking app should never be treated casually just because it is installed on a familiar phone. If something looks suspicious, stop, close the screen, and use a known official support channel rather than following a link from a message.
Recovering a normal banking workflow
Once I can sign in, I use a banking app in short, repeatable sessions. I check the available balance, review recent activity, and then leave. That workflow is safer and easier to audit than opening the app whenever I feel anxious and repeatedly refreshing the same screen. For a planned purchase, I check the balance before paying and then review the transaction later, when there has been enough time for the account activity to appear.
A realistic example is a grocery trip after work. I open the app before entering the store, confirm that the account has enough room for the planned spending, and avoid treating that number as permission to spend every available dollar. After paying, I check the transaction later rather than assuming an immediate change proves that the final amount is settled. This distinction is useful when a merchant's displayed amount and the eventual posted amount do not appear at the same moment.
For recurring bills, I find the app more valuable as a verification tool than as a replacement for a household budget. I can use it to confirm that a payment appears in account activity, but I still keep a separate list of due dates and expected amounts. That separation prevents a common mistake: seeing one successful transaction and assuming every future payment is already covered.
When something looks wrong, I write down the useful details before contacting support: the date, merchant name, amount shown, and whether the item is pending or posted. I avoid making a second payment merely because the first one is not visible immediately. This small record makes support conversations clearer and reduces the chance of duplicating a payment while trying to solve a timing issue.
Small habits that make the app more useful
I would use the app for focused checks, not as my only financial record. Exporting or recording important information elsewhere, where appropriate, gives me a longer view than a quick mobile session. It also helps when comparing monthly spending or preparing a question about an older transaction. The app is strongest at immediate account awareness; a separate budget system is usually better for planning several months ahead.
I also recommend checking the transaction details rather than relying only on the headline balance. A balance can answer “how much appears available?” while the activity list answers “what changed?” Those are different questions. Looking at both is a useful safeguard after transfers, card purchases, or any situation where timing matters.
Another practical trade-off is convenience versus device security. Keeping access easy can save time, but the phone itself becomes an important part of account protection. I would use a strong device lock, avoid lending the unlocked phone to others, and sign out or secure the device before handing it to a repair shop. These precautions are especially important for a finance app because the consequences of casual access are greater than with a weather or shopping application.
If the app becomes unstable after an update, I would first restart the phone and confirm that the operating system still meets the requirement. Then I would try the connection check and a fresh launch. Only after those steps would I consider reinstalling, and I would do that knowing I may need to authenticate again. This order preserves effort and avoids turning a minor display issue into a full setup task.
When the app is not the cause
Some banking frustrations originate outside the application. A merchant may not have completed a transaction, a transfer may still be moving through normal processing, or an account restriction may require direct attention from Navy Federal. The app can show the state of that process without being able to change it. Understanding that boundary prevents a lot of unproductive tapping.
Network conditions can also create misleading symptoms. If the home screen loads but a detail page fails, or if the app works on one connection and not another, I would investigate connectivity before changing account settings. A temporary service interruption can look identical to a broken installation from the user's perspective. Waiting briefly and checking again through an official channel is often more sensible than repeatedly deleting and reinstalling.
There is also a human factor. If a transaction is unfamiliar, the right response is not automatically to label the app inaccurate. I would compare the merchant name, receipt, household purchases, and timing first. Merchant descriptors can be less recognizable than the brand seen at the checkout counter. If the activity still cannot be explained, I would report it promptly through Navy Federal's official process rather than trying to resolve it by editing or ignoring the entry.
For account questions that require a person, a mobile app is not always the best tool. Someone dealing with a disputed transaction, a locked account, a complicated transfer, or a change in personal details may save time by contacting Navy Federal directly. The app remains useful for gathering the relevant transaction information before that conversation, but it should not be expected to replace every service route.
Who should choose it, and who should look elsewhere
I think this is a good fit for Navy Federal members who want a convenient mobile view of their banking relationship and who are comfortable completing secure sign-in steps. It suits people who check balances before spending, review activity after purchases, and prefer handling routine questions from a phone. The free price also makes it an easy companion to an existing Navy Federal account rather than a separate financial product to evaluate.
I would be more cautious if you want one app to combine banking from many institutions, build an elaborate investment dashboard, or replace a dedicated budgeting service. Navy Federal Credit Union is centered on Navy Federal access, so a multi-bank aggregator may be a better choice for someone managing several unrelated institutions. Likewise, a spreadsheet or budgeting app can offer a clearer long-term spending plan, while this app is more naturally suited to current account awareness.
People who dislike identity checks, need access from an older device, or expect every account change to appear instantly may find the experience frustrating. The minimum operating-system requirement matters before installation, and the security process can feel like extra work when all you want is a quick balance. I would not choose it solely because the store summary says “Our Members Are the Mission”; I would choose it because the Navy Federal relationship makes the mobile access relevant.
The rating of 3.7 from around 110 thousand ratings is a useful reminder to keep expectations realistic. That number does not tell me exactly which problem each person experienced, but it does suggest that smoothness is not universal across every device, account situation, or update. The large install base shows broad adoption, while the mixed average encourages a practical approach: test your own sign-in and most important workflow before depending on it during travel or an urgent payment.
My practical verdict
After using Navy Federal Credit Union as a mobile banking companion, I see its value in the ordinary moments: checking whether money is available, reviewing recent activity, and gathering clear details before asking for help. It is not a replacement for financial planning, and it cannot solve a delayed merchant transaction or account issue simply because the screen is open. Its usefulness depends on pairing the app with sensible habits and knowing when to move from troubleshooting to official support.
My advice is to install it on a supported device, complete the first sign-in while you are calm, and test a simple balance-and-activity check before you need it urgently. Keep your device secure, avoid repeated guesses when authentication fails, and distinguish pending activity from a completed result. Those steps address the most likely friction without inventing complicated fixes.
For an eligible Navy Federal member, I would recommend trying it, especially if quick mobile access matters more than advanced budgeting tools. I would keep a separate record for bills and longer-term goals, and I would contact Navy Federal directly when the issue concerns account access, a disputed transaction, or processing that the app cannot control. My final view is that it is a useful, established banking app when treated as a secure account window—not as the entire financial system.
FAQ
What is Navy Federal Credit Union, and who can join it?
Navy Federal Credit Union is a member-owned financial institution that provides checking and savings accounts, credit cards, loans, mortgages, investments, and other banking services. Membership is generally available to active-duty, retired, and veteran members of the U.S. military, certain Department of Defense personnel, their family members, and household members. Eligibility should be confirmed before downloading or applying.
What can I do with the Navy Federal mobile app?
The Navy Federal mobile app allows eligible members to manage many everyday banking tasks from an Android or iOS device. After signing in, users can review balances and transactions, transfer money, pay bills, deposit eligible checks, manage cards, locate branches or ATMs, and receive account alerts. Available features may vary depending on the account type, device, and current app version.
Is the Navy Federal app safe for mobile banking?
The application is designed with security features intended to protect account access and personal information, including login authentication, device-related security controls, alerts, and options such as biometric sign-in when supported. However, no banking app eliminates every risk. Download it only from the official app store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and never share login or verification codes.
Are there fees for using Navy Federal Credit Union or its mobile app?
Downloading and using the Navy Federal mobile app is generally not the same as paying a separate app subscription fee, but individual banking services can have their own terms and charges. Possible costs may involve certain transfers, overdrafts, wire services, loan products, or other optional transactions. Fees, eligibility requirements, and account minimums can change, so review the official disclosures before opening or using an account.
What should I do if I cannot log in or a mobile deposit does not work?
If you cannot access your account, first check your internet connection, confirm that the app is updated, and use the official password or username recovery options rather than repeatedly guessing credentials. For mobile deposits, make sure the check is properly endorsed, readable, and meets Navy Federal’s current requirements. If the issue continues, contact Navy Federal through an official support channel and avoid sharing sensitive information with unofficial contacts.


