

myFICO - Credit Score Tracking
FICOFinance
Scanned and Safe · Free
- Rating
- 4.3Out of 5
- Downloads
- 1.00M
- Android
- 12
Screenshots
Analysis by Appxis
When I decide whether a finance app deserves access to my attention, I start with a practical question: what will I use it to understand, and what choices will I have when sensitive information is involved? Credit details can affect decisions that matter for years, so I prefer a tool that helps me read them carefully rather than treat a score as a complete verdict. myFICO is built around that kind of credit check, and I find it most useful when I have a specific reason to review my file, not simply because checking an app has become a habit.
It is a finance app from FICO, and its focus is FICO-based credit information. That distinction matters: a score can differ depending on the scoring model and the bureau information being used. The app has a 4.3 average from around 11,000 ratings, with more than a million installs, but those figures tell me only that many people have tried it. They do not tell me whether its particular approach fits my needs. I would judge that by the detail I want and how often I expect to check.
What trust means when reviewing credit
Credit information is personal, so I would not install a credit-monitoring app casually or assume that a familiar name answers every privacy question. FICO develops this app, but that alone is not a substitute for reading the permission prompts and account terms shown on the device. I look at each request when it appears, ask whether it makes sense for the task I am trying to do, and avoid granting access I do not understand. That is a sensible habit with any finance tool, including one focused on a credit report.
There is also a useful difference between seeing credit information and acting on it. A score can help me spot a change worth investigating, but it cannot tell me by itself whether a lender will approve an application or what terms I will receive. I treat the app as a way to review and interpret credit details, not as a promise about a financial outcome. That keeps the score in proportion and helps me avoid making a rushed decision based on one number.
Exploring the Features
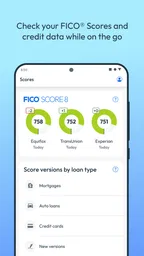
Right off the bat, myFICO: FICO Credit Check offers a comprehensive view of your credit score. The app provides access to multiple FICO scores, which is super handy because, let’s face it, the world of credit scores can be as confusing as a jigsaw puzzle with missing pieces. With this app, you can check your scores from all three major credit bureaus – Experian, Equifax, and TransUnion.
One feature that I found particularly useful is the credit score simulator. It lets you play around with different scenarios, like paying off a credit card or taking out a new loan, to see how these actions might impact your score. It’s like having a crystal ball for your financial decisions!
Using the information without overreacting
A practical use for bureau comparisons is checking whether the same account information appears consistently across reports. If one file looks different, I would note what differs and inspect the underlying report rather than assume that a score gap means an error. This is especially useful before a major application: I can review what is on file, identify questions to follow up on, and give myself time to address a possible reporting issue instead of discovering it in the middle of a lender’s process.
More Stories While You Read






The simulator is best treated as a planning aid, not a forecast. I would use it to compare the direction of possible choices—such as paying down a balance versus opening new credit—then make the real decision based on my budget, timing, and borrowing needs. A modeled result cannot account for every future change to a credit file, so I would not make a purchase or application solely because a scenario appears favorable. Its value is in making trade-offs easier to think through before I act.
For a routine, low-pressure check, I would choose one deliberate moment rather than repeatedly refreshing scores. For example, before applying for a mortgage, I could review the available bureau information, write down any unfamiliar account or balance, and contact the relevant company or bureau through an appropriate channel if something needs clarification. That workflow turns a score check into useful preparation. It also reduces the temptation to interpret ordinary movement as an emergency.
Getting into the Nitty-Gritty
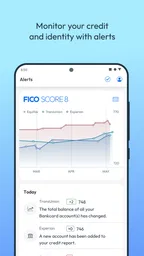
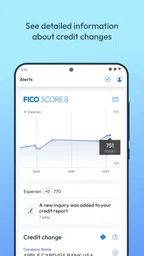
Now, let’s talk about the user experience. The interface is clean and intuitive, which makes navigating through your credit reports and scores a breeze. The app also sends you alerts if there are any significant changes to your credit report. This is a lifesaver for staying on top of your financial health and catching any potential fraud early.
An alert is a prompt to investigate, not proof of fraud. I would open the relevant report, check whether the change is recognizable, and then decide what follow-up is appropriate. This small distinction matters because a legitimate account update and suspicious activity can both deserve attention, while only one may call for a fraud response. Alerts are most helpful when I am willing to verify them calmly instead of treating every notification as a conclusion.
Before relying on any monitoring tool, I would also check the account settings and the choices available inside the app, especially if I later decide I no longer need it. I prefer to know how to manage an account and notifications before a stressful credit issue arises. The app’s visible prompts and controls are the right place to make those decisions; I would not assume that installing it automatically settles how information is handled or what account options are available.
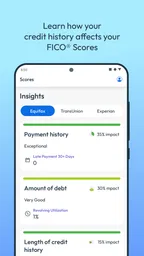
Another noteworthy aspect is the educational resources available within the app. There are plenty of articles and tips that help demystify the credit scoring process. Whether you’re a credit newbie or a seasoned pro, you’ll find something new to learn here.
That guidance is most valuable when I connect it to a real report detail rather than browse it as general reading. If I see a balance or account status I do not understand, I can use an explanation to frame the right question, then verify the underlying information before taking action. For someone building credit for the first time, this can make terminology less intimidating. For an experienced borrower, the benefit is more modest: the educational material can provide context, but it does not replace checking the actual report.
Who benefits, and when another option makes more sense
I see the strongest case for this app when someone is preparing for a consequential borrowing decision, wants to compare FICO information across bureaus, or prefers a dedicated credit-focused tool. A person who has noticed an unexpected report change may also value having scores, reports, alerts, and explanations together. The app is less compelling for someone who only wants a rough, occasional snapshot and does not need this depth. In that situation, a basic score view from a bank or a free credit-monitoring service may be enough, depending on what that provider actually offers.
Compared with checking a report directly through a bureau, an app can make repeat reviews and alerts more convenient, while a bureau’s own process may be the more direct route when I need to deal with a particular file or dispute information. Compared with a general budgeting app, myFICO is more focused on credit scoring and report monitoring; it is not the tool I would choose to organize everyday spending. These options serve different jobs, so I would pick based on whether I need an ongoing credit view, a direct report task, or a broader household budget.
One small but useful habit is to keep a private note of the date and reason for each review, along with any item I intend to follow up on. I would not copy sensitive report details into an unsecured note, but recording a simple reminder such as “check unfamiliar inquiry” helps me avoid repeating the same investigation or forgetting a question. The app can surface information; I still need a careful process for deciding what deserves action.
Cost, access, and the decision to keep it
The app itself is free to download, and it is rated for Everyone. That should not be confused with every service inside it being free: I would check the current in-app offer and terms before signing up for any paid access. Subscription value depends on how often I need the deeper information and whether alerts or ongoing monitoring matter to me. If I only need a one-time review, paying for continuing access may not make sense; if I am actively preparing for a large loan, a limited period of closer attention could be easier to justify.
It is available on devices running iOS 12 or later, and version 4.0.13.1 is the current version noted here. I would still check compatibility on my own device before planning around it. The app has been available since August 18, 2015, which gives it a longer history than a new finance tool, but age alone does not answer whether its current terms or features suit me. I would make that call by reviewing the screens and choices presented at signup.
People often ask whether checking a score through an app can hurt it. A score check for personal review is different from a lender’s application review, but I would pay attention to the wording on the specific screen and distinguish monitoring from applying for credit. Another common question is whether a single score represents every lender’s decision: it does not, because lenders may use different scoring approaches and information. I would use the app to understand my credit picture, not to predict an exact approval result.
If I found information that looked wrong, I would not assume an in-app alert fixes it automatically. I would save enough context to identify the item, verify it against the report, and follow the relevant bureau or creditor’s correction process. Likewise, I would not treat educational articles as personalized financial advice. Those steps preserve my agency: the app can help me notice and understand, while the decision about what to do remains mine.
The app is free to install and has an Everyone content rating, but neither point changes the need to handle financial details thoughtfully. I would review permissions and account choices as they appear, use a device lock, and avoid checking a report on a shared device. Those are ordinary precautions rather than claims about a particular security feature. For a finance app, that distinction is important: I want to make choices based on what I can actually see and control, not on assumptions.
Is It Worth the Investment?
Okay, let’s address the elephant in the room – the cost. myFICO: FICO Credit Check isn’t a free app, and the subscription fees can add up. However, if you’re someone who’s serious about maintaining a healthy credit score or planning a big financial move, the insights provided could be worth every penny.
In conclusion, myFICO: FICO Credit Check is a powerhouse of an app for anyone looking to keep their credit score in check and make informed financial decisions. It’s easy to use, packed with valuable features, and offers a level of insight you won’t get from free apps. So, if you’re ready to take control of your financial future, this app might just be your new best friend.
My more cautious recommendation is to decide on a job for it before downloading: compare credit information, prepare for a borrowing decision, or keep an eye on changes that you are ready to investigate. For those purposes, the combination of score views, reports, alerts, and learning material can be useful. If your need is only a casual glance, or you want budgeting and bill management in the same place, another option may fit better. I would use it deliberately, check the cost and account choices before committing, and treat every score as one helpful piece of a larger financial picture.
Pros
- Comprehensive credit report access.
- User-friendly interface for easy navigation.
- Timely alerts on credit changes.
- Detailed credit score analysis.
- Secure and reliable data protection.
Cons
- Subscription fee required.
- Limited free features.
- Occasional app crashes.
- Slow customer support response.
- Requires personal information.
myFICO - Credit Score Tracking FAQ
What is the primary purpose of the myFICO: FICO Credit Check app?
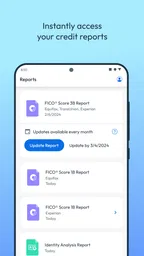
The myFICO: FICO Credit Check app is designed to help users monitor and understand their credit scores. It provides real-time access to your FICO scores and credit reports from all three major credit bureaus. The app aims to empower users to make informed financial decisions by providing insights into their credit health.
How often are credit scores updated in the myFICO app?
In the myFICO app, credit scores are typically updated as soon as new data is received from the credit bureaus. This can vary depending on the frequency of data updates from each bureau, but users can generally expect regular updates to ensure they have the most current view of their credit status. The app is designed to provide timely and accurate credit information.
Does the myFICO app offer any credit monitoring alerts?
Yes, the myFICO app offers credit monitoring alerts to help users stay informed about changes to their credit reports. These alerts notify users of significant changes, such as new accounts, inquiries, or changes in account status. This feature is crucial for detecting potential fraud or identity theft, allowing users to take swift action to protect their credit.
Is there a fee for using the myFICO app?
The myFICO app offers various subscription plans, each with different levels of service and features. While the app itself can be downloaded for free, accessing detailed credit reports and scores usually requires a paid subscription. Users should review the available plans to determine which option best suits their needs and budget.
How secure is my personal information on the myFICO app?
The myFICO app prioritizes the security of users' personal information with robust encryption and security measures. The app complies with industry standards to protect data, ensuring that users' sensitive information, such as credit reports and scores, is kept confidential. Regular updates and security protocols are in place to safeguard against unauthorized access.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- FICO
- Package Name
- com.myfico
- Version
- 4.0.23.4
- Android
- 12
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at myfico_android@fico.com, visit http://www.myfico.com, or view the https://www.myfico.com/policy/privacy-policy/.