myEquifax

- 985.00 Reviews
- 4.6
- Downloads
- 500.00K
- 1.11.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
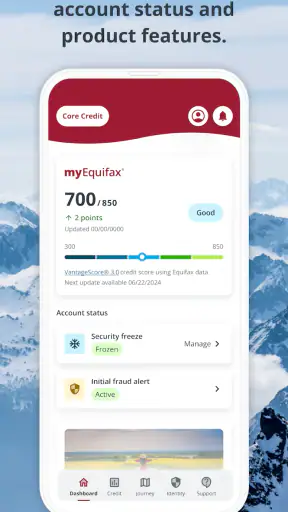
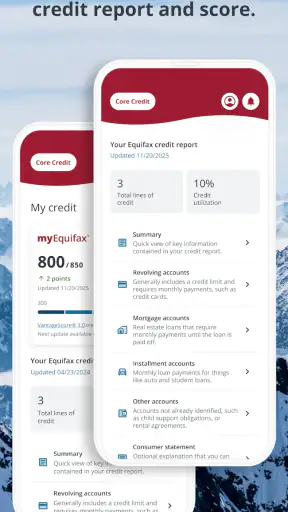
- Free access to your Equifax credit report and score
- Credit monitoring alerts can flag changes or suspicious activity
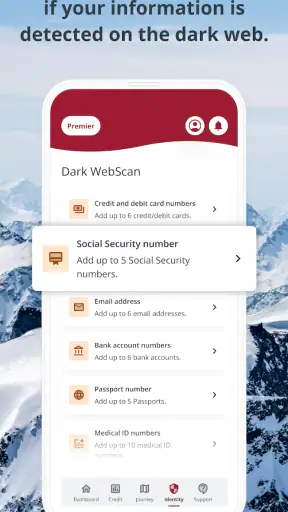
- Identity protection tools help detect potential fraud
- Secure login supports biometric authentication on compatible devices
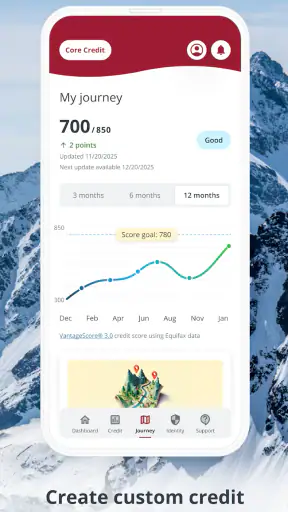
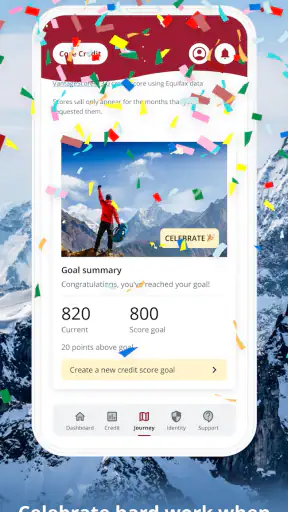
- Useful financial insights help users track credit progress
Cons
- Some features require a paid Equifax plan or separate subscription
- Credit score updates may not be available in real time
- App usefulness depends on Equifax coverage in your country
- Users may receive promotional offers for additional services
- Occasional login or verification issues can interrupt access
Review of myEquifax Appxis
Managing credit can feel unnecessarily complicated when information is scattered across websites, emails, and paper notices. I found myEquifax more useful when I treated it as a regular checkpoint rather than an app I would open only during a financial emergency. It is a free finance app from Equifax Incorporated, designed to help people start and maintain a clearer credit routine. That focus makes it approachable, but it also means it works best when you already know what you want to monitor.
The app has a 4.6 average from around 10K ratings, with more than 500K installs. Those figures suggest that it has found an audience among people who want a direct connection to their Equifax credit information. I would not describe it as a complete personal-finance command center. Instead, I see it as a focused companion for checking credit-related information, building a repeatable habit, and preparing yourself before applying for important financial products.
How I built a practical credit-checking routine
My first useful step was deciding what I wanted from the app before opening it. If I simply browse without a purpose, credit information can become a stream of numbers that does not lead to any action. A better routine is to use myEquifax when I have a specific reason: reviewing my position before a loan application, checking whether recent account activity is reflected, or confirming that my general credit picture still looks familiar.
That approach matters because a credit app is not the same as a budgeting app. Budgeting tools help me plan spending and track cash flow. myEquifax is more relevant to the credit side of financial life. I would use a budget app to ask, “Can I afford this payment?” I would use this app to ask, “What does my credit situation look like before I make the next move?” Keeping those questions separate prevents unrealistic expectations.
The most dependable workflow is simple. I open the app, review the main information without rushing, compare it with what I remember about my recent activity, and make a note of anything that deserves a closer look. I do not immediately apply for a new product just because I have checked my credit. The value comes from turning the review into a decision-making step rather than treating it as entertainment.
A realistic example is preparing to replace a car. I might check my credit position several weeks before visiting a dealership, then review my budget separately and decide what monthly payment is comfortable. If something looks unfamiliar, I have time to investigate instead of discovering the issue while negotiating under pressure. The app cannot make the purchase decision for me, but it can help me arrive better prepared.
What I check during an ordinary review
I begin with the broad picture before focusing on details. That keeps one unfamiliar item from dominating my interpretation too early. I then think about recent events that could reasonably affect my credit record, such as opening an account, changing a balance, paying off a loan, or moving through an application process. This mental timeline is surprisingly helpful because it turns a passive glance into a comparison.
I also avoid checking repeatedly throughout the day. Credit information is not a live spending dashboard, and constant refreshing can encourage anxiety without improving understanding. A scheduled review is more useful: I choose a recurring moment, open the app with a clear purpose, and record any question that needs follow-up. The exact schedule can vary, but consistency is more valuable than frequency.
One useful habit is separating “information” from “action.” Seeing a change does not automatically mean I should close an account, apply for another card, or move money around. I first ask what changed, whether the timing makes sense, and whether another source needs to be consulted. That pause is one of the best ways to avoid making a rushed financial decision based on a single screen.
Settings and account details worth checking
Before relying on the app regularly, I would review the account and notification choices available inside it. I prefer alerts that help me remember a meaningful review rather than notifications that tempt me to open the app without a reason. If notification controls are available on the device, I would use them deliberately and keep only the reminders that support my routine.
I also pay attention to sign-in behavior and device security. A finance app deserves the same care as a banking app, even when I am using it mainly for credit information. I keep my phone protected, avoid signing in on shared devices, and do not treat a saved session as permission to ignore basic security. These are ordinary precautions, but they matter more than squeezing a few extra seconds out of the login process.
Another setting-related habit is checking that my contact and account details remain current. If an app uses account information to connect me with my credit profile, outdated details can create unnecessary friction. I would rather correct a small profile issue during a calm review than discover it when I urgently need access. This is not a glamorous feature, but it is the sort of maintenance that makes a finance app dependable.
The current version is 1.11.0 and the app supports Android 8.0 or later. I would check compatibility before planning to use it on an older phone, especially if that device is no longer receiving regular system updates. Keeping the operating system and app current is also a sensible part of the routine, because financial tools should not be left unattended for long periods.
Shortcuts that make repeat checks less tiring
The fastest workflow is not necessarily opening the app as often as possible. It is reducing the number of decisions I need to make each time. I keep a short note with the date of my last review and the one question I want answered next time. That prevents me from starting from zero and helps me notice patterns instead of isolated changes.
I also connect the review to an existing habit, such as checking household finances at the end of a billing cycle. This is more reliable than depending on motivation. When the app becomes part of a broader money routine, I am less likely to forget it and less likely to overuse it. The goal is a calm, repeatable check, not constant supervision.
For important decisions, I use a two-stage process. First I review myEquifax for orientation. Then I verify the practical consequences through the relevant lender, creditor, or financial institution before acting. This is a key trade-off: the app can help me understand my starting point, but it should not be the only source I use for a contract, approval decision, or account dispute.
I find it helpful to write down questions in plain language. Instead of noting “credit issue,” I might write “Why does this account appear different from last month?” or “Does this recent payment appear as expected?” Specific questions lead to better follow-up. They also stop me from confusing a temporary display difference with a serious problem.
People who share financial responsibilities can use the app as part of a conversation, but I would be careful about sharing screenshots or login details. Credit information is personal. Discussing a general result with a partner may be useful, yet handing over account access is a different matter. I prefer to explain what I learned while keeping credentials private.
Where the app is helpful, and where its limits become clear
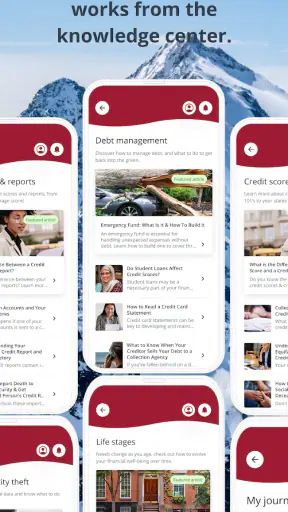
myEquifax is strongest when I want a focused view connected to Equifax rather than a broad dashboard that combines every financial account. That focus can make the experience easier for someone who is beginning to pay attention to credit. The store summary, “Start your credit journey,” fits that role: I see it as an entry point for building awareness, not as a promise to solve every financial concern.
It is less suitable for someone who wants detailed spending categories, bill automation, investment tracking, or a complete household budget. In those situations, a dedicated budgeting or banking app will usually be a better primary tool. I would not replace those tools with myEquifax because credit monitoring and cash-flow management answer different questions.
There is also a limit to what any single credit-focused app can tell me. A credit view is useful, but financial decisions often depend on information held by lenders, application rules, income, existing obligations, and timing. I would never assume that a screen in the app guarantees approval or a particular offer. The responsible use is to treat it as preparation, not prediction.
Another point of friction is emotional rather than technical. Credit information can make users overreact to ordinary movement. I have found it better to look for meaningful explanations and longer-term direction than to judge myself by one change. If I notice something I do not recognize, I investigate carefully. If I recognize it, I avoid turning a normal update into a crisis.
The app is rated for Everyone, which makes it broadly approachable from an age-rating perspective, but that should not be confused with financial simplicity. Younger users or people new to credit may still need help understanding what they see and what action is appropriate. A clear interface can reduce confusion, but it cannot replace financial education or professional advice for complicated situations.
Who should use it and who should choose another tool
I would recommend myEquifax to someone who wants a straightforward way to begin checking their Equifax credit information and who is willing to create a regular habit. It is particularly practical before a major financial step, after a period of account changes, or when someone wants to become more familiar with credit without committing to a complicated financial-management platform.
I would be more cautious about recommending it as the only finance app. If the main problem is overspending, missed bills, irregular income, or difficulty comparing monthly expenses, a budgeting tool addresses the root problem more directly. If the main concern is identity misuse or a disputed account, the app may be a useful starting point for noticing something unusual, but the user should be prepared to follow the appropriate resolution process outside the app as well.
I would also skip it as a primary solution if I need a unified view across several credit sources or a detailed analysis of multiple household accounts. A focused Equifax experience has value, but it is not the same as a full financial dashboard. Choosing the narrower tool is sensible when its scope matches the question; choosing it for everything creates disappointment.
My final assessment after using it as a habit
What I like most about myEquifax is its clear purpose. It gives credit awareness a place in my routine without asking me to turn the app into a daily obsession. The strongest results come from combining it with a calendar reminder, a short written question, and a second verification step before making a serious financial decision.
My main reservation is that beginners may expect a credit app to explain every consequence or provide a complete financial plan. It does not remove the need to understand the information or contact the appropriate institution when something requires action. Users who want budgeting, spending analysis, or broad account aggregation should look elsewhere for those functions.
Equifax Incorporated has positioned this free app as a starting point, and that is how I would use it. With a current release of 1.11.0, support for Android 8.0 and later, and an Everyone content rating, it is accessible to a wide range of users. Its value is not in replacing every money tool; it is in making one important part of financial awareness easier to revisit.
My recommendation is simple: use myEquifax when you want a focused credit check and a repeatable preparation habit, especially before a major application or financial conversation. Keep a budget app for spending decisions, verify important details with the relevant institution, and resist the urge to treat every change as an emergency. Used with those boundaries, it is a useful, practical companion for starting a more informed credit journey.
FAQ
What is myEquifax, and what can I use it for?
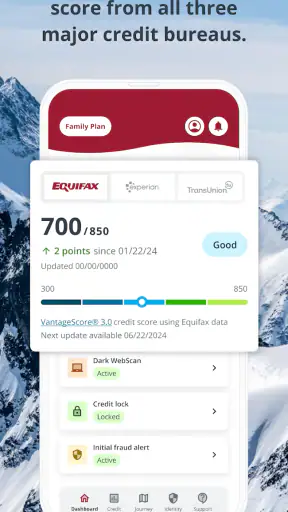
myEquifax is Equifax’s mobile and online service for viewing and managing personal credit information. Depending on your country and account, it may let you review credit-report details, monitor changes, access available credit scores or alerts, and manage identity-protection features. The exact tools, reports, and subscription options can vary by region, so check the official listing before downloading.
Is myEquifax free to download and use?
Downloading myEquifax is generally free, but not every feature is necessarily included at no cost. Some users may receive basic access to account information, while enhanced monitoring, additional reports, identity-restoration services, or other tools can require a paid plan. Review the current pricing, trial terms, renewal conditions, and cancellation policy before entering payment details.
What personal information does myEquifax require?
Because myEquifax provides access to sensitive credit and identity information, registration normally requires personal details used to verify your identity. You may be asked for information such as your name, address, date of birth, government-issued identification details, or financial account information. Only use the official app or website, avoid sharing login codes, and enable available security protections.
Can myEquifax help me detect identity theft or credit-report problems?
myEquifax can help you review information associated with your credit profile and, where available, receive alerts about certain changes or suspicious activity. It may also provide instructions for disputing inaccurate information or responding to possible identity theft. However, monitoring is not a guarantee that every fraudulent transaction will be detected, so regularly check statements and report concerns promptly.
Is myEquifax available on both Android and iPhone?
myEquifax availability depends on your country and the specific Equifax service offered in that market. In supported regions, an official version may be available through Google Play for Android and the App Store for iPhone, although features can differ between platforms. Confirm the publisher, ratings, permissions, and supported operating-system version before downloading to avoid unofficial applications.


