

MyCard - Contactless Payment
Road DogsFinance
Scanned and Safe · $17.99
- Rating
- 4.0Out of 5
- Downloads
- 10.00K
- Android
- 5.0
Screenshots
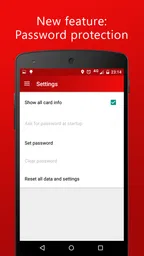
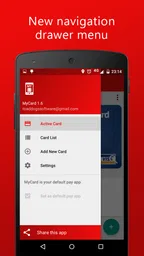
Analysis by Appxis
When I first look at a payment app, I want to know one thing before anything else: can it make a routine checkout easier without adding a new puzzle to my day? MyCard is built around that simple idea. It is a finance app from Road Dogs, and its purpose is to let a phone take the place of a contactless bank card. That is a focused promise, so I’d judge it by how smoothly it fits into the moment when you are actually paying.
What to expect from a phone-based card
MyCard is not a general-purpose banking hub that happens to include payments. The useful question is whether you want to reach for your phone instead of a physical card at a contactless checkout. If you already carry your phone everywhere, that can make a quick purchase feel more streamlined. If you prefer to keep payment separate from your phone, or you often shop where contactless payment is not available, the benefit is naturally smaller.
I would approach MyCard as a practical payment option, not as a reason to leave every other way of paying behind. Keeping a physical card available is sensible for a first outing and for places where tapping a phone does not work. That small backup habit takes the pressure off the first attempt: you can try paying with the app without turning a minor technical snag into a problem at the till.
Before you make it your everyday option
It helps to treat a contactless app as one part of a payment routine rather than a replacement for every financial tool you use. A conventional bank card is familiar and works without asking you to think about your phone’s battery or whether you have it with you. A phone payment can be handier when your wallet is tucked away, but it depends on having the device ready. Which one feels easier will depend on your habits, not just the app.
That trade-off matters most when you are in a hurry. If you are heading out with only your phone, check that it is charged and accessible before you reach the checkout. If you are carrying a bag or juggling shopping, it can be useful to decide beforehand where you keep the phone, rather than searching for it while a queue forms. Those are ordinary details, but they often determine whether a tap-to-pay routine feels genuinely convenient.
Why MyCard?
Let's face it, we live in a fast-paced world where convenience is king. MyCard brings that convenience right to your fingertips. Imagine never having to dig through your bag again; instead, just a simple tap and you're done. It's like magic, but real!
Getting Started with Ease
Setting up MyCard is as easy as pie. Trust me, if I can do it, anyone can. Simply download the app from your app store, follow the prompts to link your bank account, and voila! You're ready to go. The interface is sleek and user-friendly, ensuring even the least tech-savvy among us can navigate it without a hitch.
More Stories While You Read
For a first-time user, I’d make the setup a deliberate, unhurried task rather than something to do while standing in line. The app is a paid download at $17.99, so it is worth checking that its specific contactless-payment role is what you want before committing. It is rated for Everyone, and it runs on Android starting with version 5.0; those details help you check basic fit, but they do not replace making sure the app suits your own device and payment routine.
My practical next step after installation would be to follow the app’s own prompts carefully and complete any required setup before relying on it outside. I would not assume that installing an app alone means a payment method is ready. Once you have finished what the app asks, take a moment to understand how it indicates readiness, and keep your normal card handy for the first real purchase. That way, you can learn the flow without holding up a checkout if something needs attention.
Security First
Now, I know what you're thinking – "Is my money safe?" Absolutely! MyCard employs top-notch security measures to ensure your details are protected. With features like biometric authentication and real-time notifications, you can rest easy knowing your transactions are secure.
Payment security is also a reason to slow down and read the prompts rather than tapping through them automatically. I’d use the authentication options presented by the app and pay attention to any transaction alerts it provides, so a purchase does not go unnoticed. If you share a device or let someone else use your phone, consider whether a phone-based payment method fits that arrangement. Convenience is valuable, but it should not come at the cost of losing track of who can access the device.
A useful habit is to check the phone’s readiness before leaving home, especially if you expect to rely on it for transport, food, or a small errand. The phone is now part of the payment chain, so a low battery or a device left behind can matter more than it would when you carry a physical card. I would keep a backup payment option for situations where the phone is unavailable, rather than assuming a contactless setup removes every point of failure.
The Contactless Revolution
One of the standout features of MyCard is, of course, its contactless payment system. The joy of just tapping your phone and walking away can't be overstated. It's quick, it's efficient, and it's just plain cool. Plus, with the added bonus of reducing physical contact, it's a win-win for hygiene-conscious shoppers.
The first successful payment is the moment that tells you whether this setup fits your day. For example, imagine stopping at a shop for a drink on your way to work: rather than opening your wallet, you bring out your phone, follow the payment flow shown by MyCard, and wait for the checkout to confirm the purchase. I’d choose a low-pressure purchase for that first try, with a physical card available as a fallback. Once you know what the phone needs to do and what confirmation looks like, later taps feel less uncertain.
There is a small but important distinction between a smooth payment and a payment you can confidently repeat. At a new checkout, look for the usual contactless payment point and give the phone a moment to register the action instead of moving it away immediately. If the first attempt does not complete, pause and check the app and the terminal before trying again, so you do not accidentally create confusion about whether the purchase went through. That patient approach is more useful than assuming every failed-looking tap means the same thing.
MyCard is most appealing to someone who already reaches for a phone throughout the day and wants one less item to dig out at checkout. It is less compelling for a person who rarely uses contactless payments, dislikes relying on a charged device, or is satisfied with a physical card. A standard bank card is the simpler choice when you want a familiar, standalone payment method; a broader banking app may be a better fit if your priority is managing several financial tasks in one place. MyCard’s appeal is its narrower focus on phone-based contactless payment.
A Few Extra Perks
Beyond just payments, MyCard offers nifty features like transaction tracking and budget planning. It's like having a financial advisor right in your pocket! You can easily monitor your spending, set limits, and even get insights into your purchasing habits. It's personal finance management made simple.
If you use its spending tools, I’d make them part of a small routine rather than expecting them to manage your finances automatically. For instance, after a few everyday purchases, review the recorded activity and see whether the app’s view helps you spot a pattern you care about. That can be more useful than checking every transaction in the moment. A budget limit is most helpful when it reflects a real decision you want to make, such as keeping an eye on casual purchases, rather than being set and then ignored.
There is also a practical trade-off between convenience and adding another place to review spending. If you already track purchases through your bank, compare what you gain from checking a second app with the effort of maintaining another habit. MyCard’s payment-centered approach may suit someone who wants phone payments and a quick spending overview together. If you need detailed financial planning or want all accounts and bills in one consolidated view, it is sensible to keep using a dedicated tool for that broader job.
MyCard has been available since March 22, 2016, and its current version is 1.21. It has a 4.0 average from around 285 ratings, with more than 10,000 installs. I take those figures as useful context, not a guarantee that the app will behave identically on every setup. The most reliable test for your own needs is still a careful first payment and a quick review of how the app fits your normal routine.
Who will get the most from it?
I’d recommend trying MyCard if the idea of paying with your phone appeals to you, you are comfortable following an app’s setup prompts, and you want a focused way to handle contactless purchases. It makes particular sense for short errands where pulling out a phone feels easier than opening a wallet. It may also be useful if you like checking spending after a handful of small purchases, provided that the app’s budgeting tools match the level of oversight you want.
I would skip it if you are looking for a full banking service, if you strongly prefer not to connect payment activity to your phone, or if you need a payment method that does not depend on having your device with you. The $17.99 price is another straightforward consideration: because the purpose is quite specific, I’d weigh how often you expect to use phone-based contactless payments before deciding it is worth paying for. If your physical card already feels effortless, a dedicated app may not change enough to justify the cost.
For a cautious first run, complete setup at home, keep your usual card with you, and try the app at a checkout where you have time to respond if the payment does not go as expected. Afterward, check the transaction record and decide whether the process was clear enough to repeat. That gives you a concrete answer to the questions that matter most: whether setup made sense, whether the first tap worked for you, and whether the convenience is worth building into your routine.
In conclusion, MyCard isn't just an app – it's a lifestyle upgrade. Whether you're tech-savvy or a complete newbie, this app caters to all, making payment a breeze. So, if you haven't already jumped on the contactless bandwagon, now's the time. Trust me, once you go contactless with MyCard, you'll wonder how you ever lived without it!
Pros
- Seamless contactless payments.
- User-friendly interface.
- Supports multiple currencies.
- Fast transaction processing.
- Secure encryption for data protection.
Cons
- Limited customer support.
- Requires stable internet connection.
- Not available in all regions.
- Occasional app freezes.
- No integration with all banks.
MyCard - Contactless Payment FAQ
What is MyCard and how does it work?
MyCard is a cutting-edge contactless payment app that allows users to make secure transactions using their smartphones. By linking your bank account or credit card, you can tap your phone on compatible payment terminals to pay for goods and services. The app uses NFC (Near Field Communication) technology, ensuring quick and seamless payment experiences.
Is MyCard secure for online transactions?
Yes, MyCard is designed with top-notch security features to protect your financial information. It incorporates advanced encryption and tokenization technologies, ensuring that your card details are never shared with merchants. Additionally, it offers biometric authentication options like fingerprint or facial recognition, adding an extra layer of security to your transactions.
Can I use MyCard internationally?
MyCard supports international payments, making it a convenient choice for travelers. However, availability might depend on the country and the participating merchants. It's advisable to check with your bank or MyCard's customer support to confirm international usage and any associated fees before traveling.
What are the device requirements for using MyCard?
To use MyCard, you need a smartphone with NFC capabilities running on Android or iOS. Ensure your device's operating system is updated to the latest version for optimal performance. Additionally, your phone must have a secure lock screen enabled, such as a PIN, pattern, or biometric lock, to use the app.
Are there any fees associated with using MyCard?
MyCard itself doesn't charge users for making transactions; however, fees might be applied by your bank or card issuer. These could include foreign transaction fees when used internationally or charges for exceeding transaction limits. It's best to consult your bank's fee schedule or MyCard's terms of service for detailed information.
Read This Page in Another Language
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Road Dogs
- Package Name
- com.roaddogssoftware.cardapp
- Version
- 1.21
- Android
- 5.0
- Price
- $17.99