MoodWallet: Money Management

- 41.00 Reviews
- 4.3
- Downloads
- 10.00K
- 2.12.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Clear overview of income
- expenses
- and account balances
- Useful budgeting tools for tracking spending habits
- Simple interface suitable for users new to finance apps
- Helps organize financial goals in one convenient place
- Can encourage more consistent and mindful money management
Cons
- May require manual entry if bank synchronization is unavailable
- Advanced financial reports may be limited for experienced users
- Some features could depend on a premium subscription
- Handling sensitive financial data may raise privacy concerns
- Budget accuracy depends on keeping transactions updated
Review of MoodWallet: Money Management Appxis
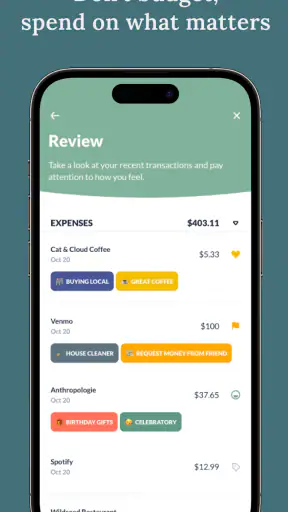
I came to MoodWallet: Money Management expecting another finance app built around categories, limits, and constant manual checking. Instead, its central idea is gentler: it tries to connect spending with how a purchase makes you feel, while avoiding the pressure of a traditional budget. That makes it interesting for people who understand the basics of personal finance but still find ordinary budgeting tiring or discouraging.
Jomo Labs presents it as a free finance app for everyone, and that matters when deciding whether it is worth trying. The app has a 4.3 average from around 150 ratings, with more than 10 thousand installs. Those figures suggest a small but positive audience rather than a universally established money-management tool. I would treat it as a focused experiment in spending awareness, not as a complete replacement for banking or accounting software.
How MoodWallet approaches everyday spending
The most useful way to understand MoodWallet is to see it as a reflection tool. Many finance apps ask, “How much did you spend?” This one is more interested in the personal side of that question: did the purchase feel worthwhile, stressful, impulsive, comforting, or disappointing? That shift can be valuable because the problem is not always a lack of arithmetic. Often, I already know that I spent too much; what I do not know is why I keep repeating the same decision.
This approach makes the app especially relevant to people who dislike strict budget systems. A conventional tracker can turn every purchase into a pass-or-fail result. MoodWallet’s promise is less rigid. Rather than forcing me to plan every category in advance, it encourages me to notice patterns in my emotional response to spending. That can make the first step easier for someone who has abandoned spreadsheets or budgeting apps several times.
I would not confuse that softer approach with a full financial plan. A mood-based view can help me understand behavior, but it does not automatically replace account reconciliation, bill planning, debt calculations, or detailed cash-flow forecasting. If I need precise control over several accounts, household finances, or complicated income, I would look toward a more traditional finance application as well.
The cost of trying it
The app itself is free to download, so the initial decision is straightforward: there is no purchase required simply to test whether its method suits me. That lowers the risk for someone who wants to explore a different relationship with spending without committing to a subscription or a paid download at the outset.
There are in-app purchases ranging from $6.99 to $89.99 per item. I would therefore avoid assuming that every part of the experience is included in the free access. The sensible approach is to install it, understand what is available without paying, and only consider an upgrade after deciding that the app’s particular method is helping me make better choices. The prices establish a paid range, but they do not by themselves prove that a purchase will be worthwhile for every user.
This distinction is important because the app’s value is personal rather than purely technical. Someone who uses it briefly to recognize a spending trigger may gain enough from the free experience. Another person who wants to build a longer-term habit may find paid access more appealing, provided the additional value is clear inside the app before buying. I would not pay simply because the topic is important; I would pay only if the extra access supports a routine I am actually maintaining.
A realistic way to use it during a normal week
Imagine that I finish a demanding workday and order food, buy a small online item, and later notice that I feel more irritated than satisfied. A normal expense tracker would record the transactions, but I might never connect them with the moment I was trying to escape. With MoodWallet, the useful exercise is to pause after the purchase and record the emotional reaction while it is still fresh.
After several similar moments, I may notice that convenience spending is not the real issue. Perhaps the purchases happen when I am tired, lonely, or avoiding an unpleasant task. That insight gives me something practical to change: I can prepare an easier meal, delay nonessential shopping until the next morning, or set a short pause before checking out. The app’s strongest contribution is not telling me that a purchase happened. It is helping me attach context to the purchase so that the next decision has more information behind it.
A useful habit is to review feelings rather than totals first. Looking only at the amount can trigger guilt and make me stop using a finance tool. Looking at repeated emotions can reveal a pattern without turning the review into self-criticism. I would then compare that pattern with my actual spending elsewhere, because emotional awareness is most useful when it leads to a concrete adjustment.
Where the app can deliver more value than a spreadsheet
A spreadsheet is excellent when I need control, formulas, custom categories, and a complete record. It is much less effective at capturing the moment behind a purchase unless I deliberately design a system for that. MoodWallet’s advantage is the lower psychological barrier. It frames money as a behavior I can observe, not merely a ledger I must maintain.
That difference is not cosmetic. A person who repeatedly quits budgeting may be more likely to keep using a tool that feels reflective instead of punitive. In my view, the app is most valuable during the early stage of changing habits, when the main challenge is noticing the trigger before trying to optimize every dollar.
There is also a useful trade-off here. The less demanding the system feels, the less comprehensive it may be. A spreadsheet can show exactly where money went across a long period. MoodWallet’s appeal comes from making spending emotionally understandable, but that focus means I should not rely on it alone when accuracy, documentation, or detailed planning is the priority.
What I would want to understand before paying
The free entry point makes experimentation easy, but I would still inspect the purchase screen carefully. The presence of several in-app purchase levels means the paid value should be judged by what each option adds, not by the existence of a premium tier. I would ask myself whether I am using the app consistently, whether its reflections have changed a real decision, and whether the paid access removes a limitation that actually affects my routine.
This is also where expectations matter. If I want a banking dashboard, automatic financial administration, or a professional accounting workflow, MoodWallet is probably not the right purchase regardless of price. If I want help understanding why certain spending choices keep happening, the same paid decision may feel more reasonable. The value depends on the problem I am trying to solve.
I would also avoid treating an upgrade as motivation by itself. Paying for a finance app does not create a habit. A simple free routine that I follow after meaningful purchases can be more useful than an expensive feature set I open only once. The best test is behavioral: does the app make me pause, notice, and act differently?
Trade-offs that are easy to overlook
The first trade-off is emotional honesty versus convenience. Recording a purchase is easy; recording how I felt about it can be uncomfortable, especially when the answer is embarrassment or regret. That extra honesty is where the insight comes from, but it also creates friction. Users who want a completely automatic experience may find the reflective element demanding.
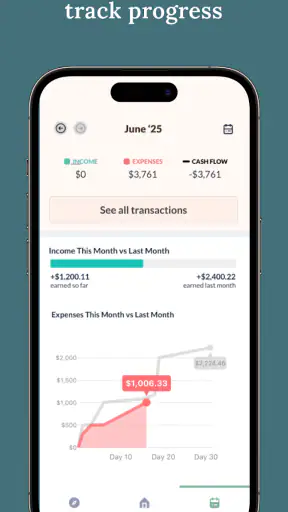
The second is flexibility versus comparability. Traditional categories let me compare groceries this month with groceries last month. A mood-centered approach can reveal a different kind of pattern, such as repeated spending during stressful evenings, but those observations may be less tidy. I gain context and lose some of the clean structure that makes conventional reports satisfying.
The third is self-awareness versus self-blame. Mood tracking can help me identify triggers, but it should not become a way to label every comfort purchase as bad. A purchase can be emotionally useful and financially sensible, or financially unnecessary but still informative. I would use the app to ask better questions, not to punish myself for having ordinary needs.
A fourth trade-off concerns scope. MoodWallet is appealing precisely because it does not lead with complex budgeting. That makes it approachable, but users who need strict limits may feel that it leaves too much responsibility with them. If overspending is creating immediate financial danger, I would pair this kind of reflection with a concrete spending plan rather than expecting emotional insight alone to solve the problem.
Who is likely to benefit most
I think the best match is someone who has tried standard budgeting and found it too rigid, too time-consuming, or too easy to abandon. The app may also suit a person who can identify individual purchases but cannot see the emotional situations that lead to them. In both cases, the goal is not to become an accountant. It is to create enough awareness to make the next choice more deliberate.
It could be useful for someone beginning a financial reset after a period of impulsive spending. Instead of attempting a perfect plan on the first day, I would use it to collect observations for a while: what kinds of purchases feel rewarding, which ones create regret, and what circumstances appear repeatedly. That information can then guide a more practical budget if I decide to build one later.
It may also help people who are financially organized on paper but still feel anxious about money. A complete ledger does not always explain why spending produces stress. Reflecting on the emotional side can show whether the anxiety comes from uncertainty, guilt, social pressure, or a particular type of purchase. That is a different problem from missing totals, and a different kind of tool can be appropriate.
Who should choose something else
I would skip it as my main finance tool if I need automatic account management, detailed investment tracking, shared household controls, formal reports, or strict envelope-style planning. Those needs call for an application designed around transactions and financial structure rather than mood and behavior.
I would also be cautious if I know that manual reflection will become another abandoned task. The app’s concept depends on my willingness to engage with purchases personally. If I want to connect a bank account and let software handle most of the work, a conventional tracker will probably provide more immediate utility.
People dealing with urgent debt, missed bills, or unstable income should treat MoodWallet as a supplementary aid at most. Emotional patterns can explain spending, but they do not replace a repayment schedule, a bill calendar, or professional guidance when the situation is serious. The app is better suited to awareness and habit change than crisis management.
Practical setup advice
When I start using it, I would keep the first routine deliberately small. Rather than attempting to document every transaction perfectly, I would focus on purchases that feel unusually satisfying, stressful, impulsive, or confusing. These are the entries most likely to teach me something. After a few days, I would look for repeated situations instead of judging individual choices.
I would also write a short action beside a repeated pattern. If late-night shopping appears often, the action might be waiting until morning before buying. If social spending creates anxiety, I might decide on a comfortable amount before meeting friends. The reflection becomes valuable when it leads to a specific experiment, and the next review can show whether that experiment helped.
Another useful boundary is to keep factual money tracking separate when necessary. I would use MoodWallet for the emotional and behavioral layer, while keeping bills, balances, and obligations in a system suited to those details. This two-tool approach may sound less convenient, but it prevents the app from being judged unfairly for not serving a purpose it was not built to prioritize.
The app is available for devices running Android 7.0 or later, and its current version is 2.12.0. It has an Everyone content rating, which fits its broad subject matter. Jomo Labs released it on September 13, 2021, so it is not a brand-new experiment, yet its audience remains relatively modest compared with the biggest finance products. I would see that as a reason to evaluate the experience personally rather than assuming it has the depth or ecosystem of a market leader.
My buying verdict
My recommendation is conditional but positive. Because the app is free to start, I think it is worth trying for anyone who feels that ordinary budgeting records expenses without changing behavior. The concept is specific enough to be useful: it asks me to examine the emotional reason behind spending, not just the amount. That can uncover triggers that a category chart never shows.
I would not recommend paying immediately. First, I would use the free access long enough to see whether I return voluntarily and whether the reflections lead to a real change, such as delaying an impulse purchase or planning around a recurring trigger. If that happens and a paid option clearly supports the routine, an upgrade may have value. If not, there is little reason to spend simply to own another finance tool.
In the end, MoodWallet: Money Management is best understood as a companion for better spending awareness, not a complete financial command center. Its free starting point is attractive, its emotional angle is more approachable than strict budgeting for some people, and its limitations become clear when detailed financial administration is required. The best reason to try it is not to track more numbers, but to understand the moments that make you spend.
FAQ
What is MoodWallet: Money Management used for?
MoodWallet is designed to help you organize and understand your personal finances in a more approachable way. You can use it to record income and expenses, review spending patterns, monitor budgets, and keep an eye on your financial habits. Its mood-oriented approach may also encourage you to reflect on how purchases affect your feelings, rather than focusing only on numbers and totals.
Is MoodWallet suitable for beginners who have never used a budgeting app?
Yes, MoodWallet can be useful for beginners because its main purpose is to make everyday money tracking easier to understand. New users can start by adding regular income, entering expenses, and grouping transactions into categories. However, the usefulness of the app depends on consistent updates, so users who want accurate reports should make a habit of recording purchases promptly.
Does MoodWallet connect directly to my bank account?
Before downloading, users should check the app’s current store description and privacy information to confirm whether bank synchronization is available in their country and on their device. Some versions of money-management apps rely entirely on manual entries, while others may support financial connections through third-party services. Do not assume that automatic transaction importing is included without verifying the latest details.
Is my financial information safe when using MoodWallet?
Because MoodWallet may contain sensitive information about your income, spending, and financial routines, privacy should be considered before use. Review the app’s privacy policy, requested permissions, data-storage practices, and any available security features such as passcode or biometric protection. Avoid entering bank passwords, card PINs, or other credentials unless the app clearly explains a trusted and secure connection method.
Is MoodWallet free to download, or does it require a subscription?
The download model and available features can vary between Android and iOS and may change with future updates. MoodWallet may offer a free version with optional premium tools, in-app purchases, or a subscription for additional reports and customization. Check the relevant app store page before installing, paying particular attention to trial periods, renewal terms, and whether deleting the app automatically cancels a subscription.


