MoneyPilot : Class Action

- 202.00 Reviews
- 4.6
- Downloads
- 50.00K
- 1.0.55
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
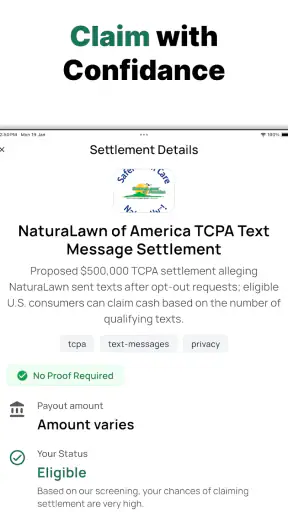
- Simple interface makes case and payment information easy to review.
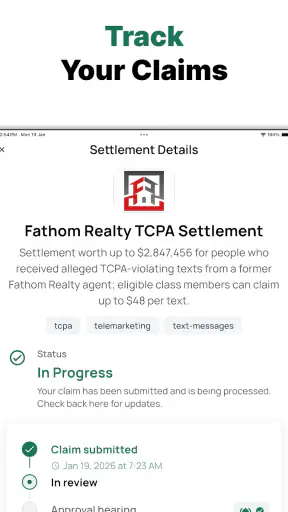
- Useful notifications can help users track important claim updates.
- Supports digital document access without relying entirely on paper mail.
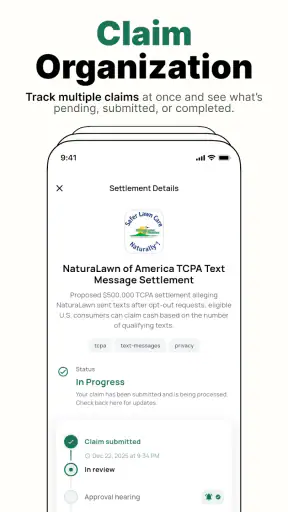
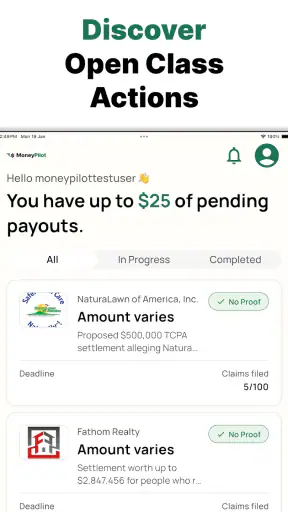
- May help organize multiple class-action claims in one place.
- Free to download
- with no upfront cost for basic access.
Cons
- Eligibility checks may require personal and sensitive information.
- Not every listed settlement will be available in every state or region.
- Payout amounts and payment dates can change without much notice.
- Some claims may require extra documents or lengthy verification steps.
- The app cannot guarantee approval or payment for submitted claims.
Review of MoneyPilot : Class Action Appxis
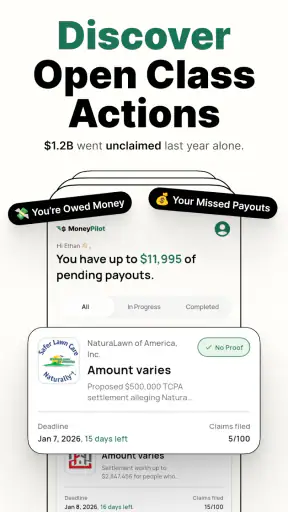
MoneyPilot: Class Action is a finance app from Bloom Processing that I found most useful as a focused place to look for possible class-action payouts and keep track of claims. Its appeal is easy to understand: instead of relying on memory, scattered emails, or occasional web searches, I can put this kind of task in one app and return to it when I have time. The central experience revolves around finding and tracking claims and submitting payout claims, rather than managing a bank account or building a budget.
That distinction matters. I would not treat it as a replacement for a banking app, investment service, tax tool, or full personal-finance dashboard. It is narrower, and that narrow purpose is also its main strength. If I regularly forget to check whether I qualify for settlements, the app gives that habit a clear home. If I rarely care about class actions or expect an all-in-one money manager, the novelty may wear off quickly.
What the first week feels like
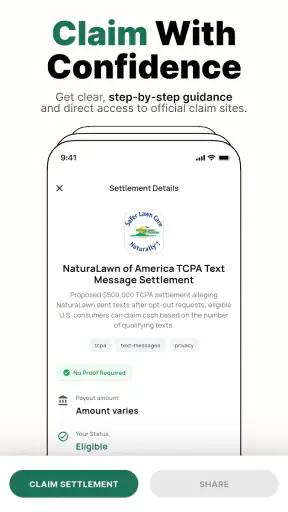
During the first week, the most attractive part is the sense of organization. The idea of finding relevant claims, reviewing them, and submitting a payout claim from one finance-focused app is more practical than keeping browser tabs open or trying to remember which settlement pages I saw previously. The workflow feels suited to short sessions: open the app, inspect what is available, decide whether a claim is worth pursuing, and leave.
I especially like that this format encourages a decision rather than passive browsing. A claim is not automatically valuable simply because it appears in a list. I would want to read the eligibility wording, check the submission requirements, note any deadlines, and decide whether the expected effort makes sense. MoneyPilot can help me maintain that process, but it does not remove the need for judgment. The app is a finder and tracker, not a substitute for reading the terms of a settlement.
A realistic use case is a Sunday evening money check-in. I might already be reviewing receipts and upcoming bills, so I can spend a few minutes checking newly available claims and revisiting anything I saved earlier. If a submission needs information I do not have nearby, I can avoid rushing and return later. That is a better habit than filling out forms casually while distracted, particularly when a claim asks for dates, purchase details, or other supporting information.
The app is free to install, which makes trying that routine relatively easy. It is rated for Everyone, so its presentation is accessible to a broad audience. I would still approach every financial claim carefully, because an age rating describes who can use the app, not whether every opportunity is equally worthwhile or every form deserves an immediate submission.
Its early reception is encouraging: MoneyPilot: Class Action holds a 4.6 average from around 1.9 thousand ratings, with more than 50 thousand installs. Those figures suggest that the basic idea is resonating with a meaningful group of users. They do not guarantee that every claim will apply to me, but they make the app feel established enough to test rather than merely curious.
Where the early value comes from
The first-week benefit is not that the app magically produces money. The useful part is reducing the friction between hearing about a settlement and doing something sensible with it. I can use the app as a checkpoint: identify an opportunity, inspect its conditions, record its status, and avoid repeating the same research later.
One non-obvious advantage is the separation between discovery and submission. I do not have to complete every claim the moment I find it. That makes it possible to gather the information I need first, then return when I can concentrate. For people who tend to abandon forms halfway through, this two-step approach can be more valuable than a faster but less organized search.
Another practical tip is to treat the tracker as a review queue, not a collection of guaranteed payments. I would keep only claims I genuinely intend to investigate, and I would remove or disregard anything that no longer seems relevant. A crowded list can create the same stress as an overflowing email inbox. The app works best when it supports a small, deliberate routine.
What remains useful from month to month
The long-term question is whether MoneyPilot becomes part of my financial maintenance or simply provides an interesting first impression. In my experience, its recurring value depends on how often I encounter potential class-action opportunities and how disciplined I am about revisiting them. This is not the kind of app I would open several times a day. Its natural rhythm is occasional and purposeful.
For a user who wants a monthly money review, that can be enough. A recurring check lets me look for new claims, revisit submissions, and confirm that I have not left a promising opportunity unfinished. The app’s value compounds through consistency: one ignored claim is easy to forget, while a short monthly review keeps the process visible.
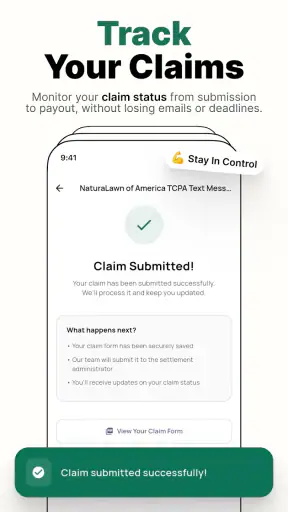
I would pair it with a simple personal note containing the claim name, the date I submitted, and any follow-up action I still need to take. That is not a criticism of the app; it is a sensible safeguard for any process involving deadlines and delayed payouts. The tracker can be the working location, while a separate calendar reminder helps prevent the common mistake of assuming that submission means the process is complete.
This is also where expectations need to stay realistic. A settlement may take time, may require eligibility that I cannot prove, or may produce a payment that is not worth the effort for my particular circumstances. MoneyPilot helps me find and manage the opportunity, but the recurring value comes from making good decisions about which claims deserve attention.
The app’s current version is 1.0.55, and the minimum operating-system requirement is Android 7.0. That makes it approachable for people using older Android devices, although I would still keep the app updated when updates are available. Finance-related tools benefit from predictable maintenance, and an outdated installation is not ideal for a routine involving forms and personal information.
Who gets lasting value
I think the best fit is someone who has heard about class actions before but rarely follows through. The app gives that person a repeatable workflow without requiring a large financial system. It may also suit users who want a dedicated place for settlement-related activity instead of mixing it with banking notifications, shopping apps, or a general notes application.
It is less compelling for someone who expects detailed budgeting, spending categories, credit monitoring, bill negotiation, or investment tracking. Those are different jobs. A conventional personal-finance app is a better choice when the goal is to understand monthly cash flow. A browser and a spreadsheet may be better for a user who wants complete control over research and record-keeping. MoneyPilot earns its place only when its focused convenience is more useful than that flexibility.
There is a further trade-off for people who are very selective about financial apps. The free entry point lowers the barrier to trying it, but in-app purchases range from $3.99 to $99.99 per item. I would not assume that installing the app requires a purchase, and I would review any paid option carefully before accepting it. The important question is whether a paid feature saves enough time or adds enough practical value for my own claim-tracking habits.
How much maintenance it demands
The maintenance burden is fairly manageable if I use the app as a scheduled tool rather than an always-open feed. A short monthly review is a sensible starting point. I would check new opportunities, inspect any saved items, update the status of submitted claims, and remove tasks that no longer deserve attention. That routine should remain small; if it grows into a second administrative job, the app has stopped helping.
The most important maintenance step is verification. Before submitting, I would read the eligibility conditions and the instructions attached to the claim. I would also check that the information I enter is accurate and keep a personal record of what I submitted. These steps take time, but skipping them can turn a convenient finder into a source of confusion.
A useful workflow is to divide claims into three groups: investigate, ready to submit, and submitted. Even if the app does not present those exact labels as a built-in system, thinking this way makes the process clearer. “Investigate” means I still need to decide whether I qualify. “Ready” means I have the necessary details and can complete the form carefully. “Submitted” means I should record the action and watch for any next step.
This approach exposes one of the app’s limitations: tracking is only as reliable as my own follow-through. A notification, list, or status indicator cannot replace a decision. If I never return to the app, the discovery feature has little lasting value. That is why I would set a recurring reminder outside the app rather than expecting the app alone to create a habit.
Privacy-minded users should also apply normal caution to any finance-related service. I would avoid entering information that is not needed for a specific claim, read each form before sending it, and keep sensitive documents organized separately. The convenience of centralizing claim activity should not encourage careless sharing.
Where fatigue can set in
The biggest source of fatigue is the gap between finding a claim and receiving a payout. Discovery feels immediate, while results may be distant or uncertain. If I open the app expecting quick money every time, I will probably become disappointed. The healthier mindset is to view it as a screening and organization tool, with possible financial benefit rather than a dependable income source.
Relevance can also affect motivation. Not every claim will fit my purchases, location, dates, or circumstances. Repeatedly opening an app and finding nothing worth submitting can make the routine feel unrewarding, even when the app is functioning as intended. I would therefore use it on a schedule instead of checking constantly. Occasional review protects the app from becoming another source of notification fatigue.
There is also a judgment cost. Each opportunity may require reading conditions and deciding whether the effort is justified. Users who prefer one-tap automation may find that process tedious. In contrast, someone who already enjoys keeping careful records may appreciate the control. This is a genuine trade-off: the app can make the work easier to organize without making the underlying legal and administrative details disappear.
Paid options may create another point of friction. Since individual in-app purchases can reach $99.99, I would be particularly cautious about upgrading simply because a feature sounds convenient. I would first use the free experience long enough to understand my actual routine, then compare the cost with the time I realistically save. For occasional users, paying may not make sense; for frequent claim researchers, it could be more reasonable if the benefit is clear.
The app is also not the right choice for anyone looking for certainty, personalized legal advice, or a complete financial command center. A lawyer, official settlement administrator, bank, or dedicated budgeting service may be more appropriate depending on the question. MoneyPilot’s role is narrower, and respecting that boundary prevents most of the frustration I can imagine a new user having.
Does it earn a permanent place?
My long-term verdict is cautiously positive. MoneyPilot: Class Action earns a place on my device when I treat it as a low-frequency financial maintenance tool: check it periodically, investigate carefully, submit only when eligible, and keep my own record of important actions. Its lasting value comes from preventing opportunities from disappearing into memory, not from turning every visit into a payout.
I would recommend it to friends who routinely miss settlement deadlines or dislike searching through scattered sources. The focused design makes sense for that problem, and the free starting point makes experimentation straightforward. Bloom Processing has chosen a specific use case rather than trying to imitate a full banking suite, and that focus is what makes the app potentially useful.
I would skip it if I want budgeting, account aggregation, investment analysis, or a guaranteed return on my time. I would also avoid paying for extras until I had established a regular habit and could name the exact problem the purchase solves. For an occasional user, the free experience may be all that is needed; for others, the recurring workflow may justify keeping it installed.
Ultimately, the app survives the novelty test only when I give it a modest, repeatable job. A monthly review, careful eligibility checks, and an external reminder are enough to turn it from a curiosity into a practical part of my money routine. Its real strength is making forgotten claim research easier to revisit, while its real weakness is that it cannot replace the patience and judgment required to complete the process.
FAQ
What is MoneyPilot: Class Action, and what does the app do?
MoneyPilot: Class Action is designed to help users discover and review potential class action settlement opportunities that may apply to them. The app may provide information about eligible cases, estimated compensation, deadlines, and claim instructions. It should be viewed as an informational tool rather than a law firm or a guarantee that you will receive money from any settlement.
Is MoneyPilot: Class Action free to download and use?
The app may be available to download without an upfront charge, but users should carefully review its current terms, privacy policy, and any optional paid features before using it. Some services may involve advertisements, subscriptions, or other costs depending on the version and region. Always check the payment details shown in the app store and during registration.
Can MoneyPilot guarantee that I will receive class action settlement money?
No. MoneyPilot cannot guarantee eligibility, approval, or payment for any class action settlement. Each case has its own requirements, deadlines, proof-of-purchase rules, and distribution process, which are controlled by the court-appointed administrator or legal representatives. The app can help you find information, but you remain responsible for submitting accurate claims and following official instructions.
What personal information does MoneyPilot: Class Action require?
Depending on the features you use, MoneyPilot may request details such as your name, email address, location, purchase history, or information needed to determine whether you could qualify for a settlement. Before entering sensitive data, read the app’s privacy policy and understand how information is collected, stored, shared, and deleted. Avoid providing unnecessary financial or identity documents unless an official process clearly requires them.
Are the settlement listings and claim deadlines in MoneyPilot reliable?
The app can be useful for discovering potential settlements, but users should independently verify important details through the official settlement website, court documents, or notices from the settlement administrator. Deadlines, eligibility requirements, and payment estimates can change, and information may not always be complete or current. Never rely solely on an app notification when a claim deadline is approaching.


