Money App - Cash Advance

- 2.44K Reviews
- 4.2
- Downloads
- 500.00K
- 2.47.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Quick application process with minimal paperwork
- Clear repayment terms shown before accepting an advance
- Useful budgeting tools for tracking everyday spending
- Funds can help cover unexpected short-term expenses
- Simple interface that is easy for first-time users
Cons
- Eligibility and advance limits vary by user
- Some features may require access to banking information
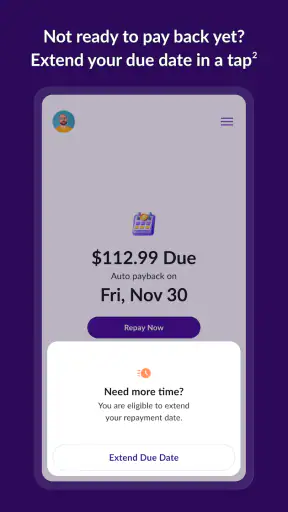
- Repayment dates may be difficult to change
- Not available in every state or country
- Late repayment could lead to fees or financial pressure
Review of Money App - Cash Advance Appxis
I approached Money App - Cash Advance as a practical finance tool rather than as a complete money-management system. Its purpose is straightforward: help people look for emergency cash through a mobile app. That narrow focus can be useful when an unexpected expense arrives and visiting a branch is inconvenient, but it also means I would not treat it as a replacement for budgeting, banking, or careful comparison shopping.
The app is free to install, is aimed at Everyone, and comes from PRG Ventures. It belongs to the finance category and has built a sizeable audience, with more than 500 thousand installs and an average rating of 4.2 from around 10 thousand ratings. Those figures suggest that many people find the basic idea useful, although popularity alone is not a reason to accept an advance without reading the terms attached to it.
How Money App feels to use in real situations
Readable enough for a quick financial decision
My first impression is that an emergency-cash app needs to reduce mental effort. When someone is dealing with a broken appliance, an overdue bill, or an unexpected travel problem, they are rarely in the mood to explore a complicated financial dashboard. Money App works best when approached with one question: can it help me understand my available cash options clearly enough to decide what to do next?
The short store description, “Money App,” is deliberately simple, while the broader promise is centered on emergency cash. That simplicity can make the app feel approachable to someone who has never used a cash-advance service before. At the same time, a simple entry point should not be confused with a simple financial decision. I would slow down as soon as the app presents eligibility questions, repayment information, fees, or any request to continue elsewhere.
For readability, I recommend using the phone’s normal text and display settings rather than shrinking everything to fit more content on the screen. A person with reduced vision may find dense financial wording tiring, especially if several conditions appear close together. The most important information is not the promotional wording; it is the amount involved, the timing, and the total obligation. I would look for those details before entering personal information or moving forward.
Navigation is most helpful when each screen has one obvious purpose. In practice, I would avoid rushing through a form simply because the buttons are easy to find. A clear path through an application can still lead to a poor choice if the user does not pause to check what is being requested. My useful rule here is to read every screen that changes the financial commitment, even if the earlier screens felt effortless.
What the app can and cannot replace
Money App is more focused than a traditional banking app. A bank application usually gives me account balances, transfers, statements, card controls, and a longer record of my finances. A budgeting app helps me understand whether an emergency expense will create a larger problem later. This app is better understood as a possible route toward short-term cash, not as a place to organize an entire financial life.
That distinction matters because the fastest option is not always the cheapest option. If I already have savings, a trusted bank facility, or a payment arrangement with the bill provider, those alternatives may be easier to understand and less expensive. I would compare them before treating an advance as the default answer. Money App is most relevant when speed and mobile convenience matter, but convenience should come after checking the full repayment picture.
The app’s current version is 2.47.0, and it requires Android 7.0 or later. That makes the operating-system requirement relatively approachable for people using older compatible Android phones, although the experience will still depend on the device, display, and system settings. People on unsupported hardware may need another route to emergency funds, such as a browser-based service, a bank, or in-person help.
A realistic everyday scenario
Imagine that my washing machine stops working just before payday. I open the app because I want to investigate whether an emergency-cash option is available, not because I have already decided to borrow. I would first make a note of the repair cost, check my bank balance, and ask whether the repair company offers a short payment arrangement. Only then would I use Money App to explore the next possibility.
During that process, I would keep a written record of the amount requested, the expected repayment date, and any additional cost shown on screen. I would also check whether repayment would collide with rent, utilities, food, or transport expenses. This workflow is more important than simply completing the application quickly. The app can help me investigate a short-term option, but it cannot decide whether that option fits my budget.
For someone who has difficulty remembering spoken instructions or processing information under pressure, writing down each obligation can make the experience safer. A trusted person can also review the final terms, provided the user protects passwords, verification codes, and other private details. That is a practical accessibility measure even when the phone itself is easy to operate.
Motor and sensory considerations
Touchscreen finance apps can be challenging for people with tremors, limited dexterity, or difficulty maintaining a precise finger position. I would use the app when seated, with the phone supported on a stable surface, rather than while walking or handling several objects. This reduces accidental taps and gives me time to inspect each action before confirming it.
People who rely on screen readers, magnification, high-contrast settings, or larger text should test the early screens carefully. I would pay attention to whether labels remain understandable when text is enlarged and whether important instructions are still connected to the fields they describe. I cannot assume that every screen will behave perfectly with every Android accessibility setting, so a user who depends on a particular assistive setup should verify the key steps before an urgent situation occurs.
Visual access is only one part of the experience. Some users may need extra time to distinguish buttons, notices, and confirmation areas. Others may find bright screens or long reading sessions uncomfortable. Lowering screen brightness, enabling a preferred display mode, and taking breaks can help with the physical side of the task, but the financial content still deserves full attention. No display adjustment can make unclear repayment wording acceptable.
For users with hearing loss, a mobile application is potentially more convenient than a process that depends on phone calls, but the app should still be judged by how much information is available in text. I would want essential instructions, status messages, and next steps to be readable rather than dependent on audio alone. If a later stage sends the user outside the app, I would make sure that any communication channel is workable for the person’s needs before proceeding.
Access when time, location, or connectivity is limited
The strongest situational advantage is mobility. A person may be at home, at work, or away from a branch when an urgent expense appears. A free app can be easier to try than arranging an appointment, especially for someone with limited transport, caring responsibilities, or an unpredictable schedule. That convenience is meaningful, but it does not remove the need for privacy and concentration.
I would avoid completing a financial application on a shared phone, an open public network, or in a crowded place where another person can see the screen. Someone with limited private space may need to wait until they can review the information safely. This is particularly important for users who rely on another person for transport or technical help, because assistance should not turn into pressure to disclose private financial details.
Situational access also includes language and comprehension. Financial terms can be difficult even for confident readers, and stress makes them harder to process. If a user is unfamiliar with the wording, I would recommend pausing and asking a qualified, trusted adviser to explain it in plain language. A friend can help read the screen, but should not guess at the meaning of a fee or repayment condition.
The app is available at no purchase cost, which lowers the barrier to trying it. That does not mean the financial service reached through it is cost-free. I would separate the cost of downloading the app from the cost of accepting an advance. This is one of the most important distinctions for a first-time user, particularly someone who sees “free” and assumes there will be no associated expense.
Privacy, pressure, and remaining barriers
Emergency-cash services naturally involve sensitive information. I would treat every request for personal, employment, banking, or identity details as something to inspect carefully. Before continuing, I would check why the information is needed, whether the screen explains the next step, and whether I am comfortable with the process. If the wording feels rushed or unclear, leaving the application is a reasonable choice.
Another barrier is financial stress itself. A person seeking emergency cash may focus on receiving money today and underweight what happens on the repayment date. I think the app should be used with a cooling-off routine: calculate the amount that can genuinely be repaid, list essential bills due before then, and compare the result with other available options. If the numbers only work by borrowing again, this is probably not the right solution.
People who need a large, long-term loan may also find the app unsuitable. Its identity is built around emergency cash, so I would look elsewhere for structured borrowing, debt advice, or a detailed repayment plan. Likewise, someone who wants investment tracking, spending categories, or full account aggregation should choose a dedicated finance app. Using one tool for a job it was not designed to do creates unnecessary confusion.
There is also a practical support barrier for users who cannot complete digital forms independently. A person with cognitive disabilities, limited literacy, or unfamiliarity with financial applications may need a support worker or trusted helper. The helper should explain each step without taking control of the decision. I would never hand over a phone unlocked or share security codes merely to make the process faster.
Who should consider it, and who should skip it
I can see Money App being useful for an Android user who wants to investigate an emergency-cash option from a phone, understands that approval and terms require careful review, and can compare the result with other choices. Its free entry point and focused purpose make it approachable when time is limited.
I would skip it if I were looking for a complete budget, a regular banking replacement, investment tools, or a long-term borrowing plan. I would also avoid relying on it if I could not comfortably read the terms, protect my private information, or work out how repayment would affect essential expenses. In those situations, a bank, credit union, debt adviser, or direct arrangement with the bill provider may offer a better fit.
My most useful tip is to prepare before an emergency happens. Install the app only if it suits your device, review how its screens work when you are calm, and decide what information you would need to compare an offer responsibly. Do not wait until a bill is overdue to discover that the process is difficult with your display settings or assistive technology.
A second tip is to keep the app’s role narrow. Use it to explore a possible cash solution, then return to your own budget or written notes to make the decision. A third is to treat every confirmation as a financial commitment, not as a routine tap. These habits reduce the chance that speed will replace understanding.
My inclusive verdict
After looking at Money App through the lens of readability, physical interaction, sensory needs, and stressful real-world situations, I see a useful but limited tool. It makes emergency-cash research more mobile and may suit people who prefer handling the first steps digitally. The Everyone age rating and broad Android compatibility also make it approachable for a wide range of users.
Still, inclusive access is not only about opening an app. It is about being able to understand the wording, operate the controls, protect personal information, and make a free decision without pressure. Users who depend on larger text, screen readers, magnification, or help from another person should test the process carefully and keep control of the final choice.
PRG Ventures has built an app with a clear financial purpose, and its audience reflects genuine interest in that purpose. My recommendation is conditional: consider it when you need to explore short-term emergency cash and can evaluate the repayment consequences, but do not mistake a convenient mobile route for an automatically suitable loan. The best use of Money App is as one carefully checked option, not the only option.
FAQ
What is Money App – Cash Advance, and how does it work?
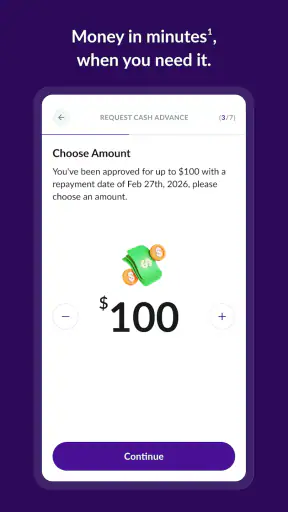
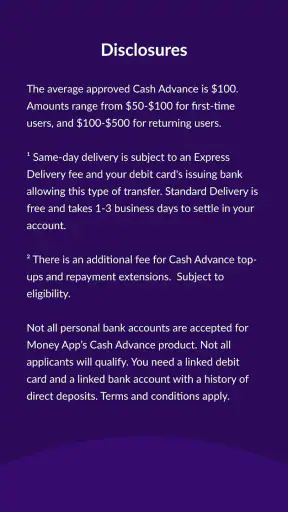
Money App – Cash Advance is designed to help eligible users request a small amount of money before their next payday. After creating an account, you generally provide personal and financial information, connect a qualifying bank account, and review the available advance terms. Approval, funding speed, limits, and eligibility can vary, so the app should not be treated as a guaranteed source of emergency money.
Does Money App – Cash Advance charge fees or interest?
Before requesting an advance, carefully review the complete cost shown in the app. Depending on the service and your location, charges may include optional express-transfer fees, membership or subscription costs, late-related fees, or other service charges. A cash advance may not use traditional interest, but that does not necessarily make it free. Always confirm the total repayment amount, billing schedule, and cancellation terms.
How quickly can I receive money through the app?
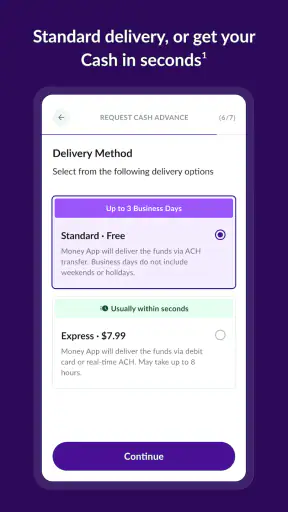
Funding time depends on your eligibility, bank verification, approval process, transfer method, weekends, holidays, and whether you select a standard or expedited delivery option. Some users may receive funds quickly, while others may experience delays if additional information is required. The app’s estimated delivery time should be considered an estimate rather than a guarantee, especially when money is needed for an urgent expense.
What information and permissions does the app require?
To evaluate eligibility and deliver funds, Money App – Cash Advance may request details such as your name, contact information, identification, income, employment information, and bank-account data. It may also require permission to connect with a financial institution or verify transactions. Review the privacy policy and permission requests before continuing, and only provide information through the official app or a trusted download source.
What happens if I cannot repay the cash advance on time?
Repayment is usually scheduled automatically from the linked bank account on the date displayed during the request process. If the account does not have enough money, the payment could fail and may lead to additional charges, repeated debit attempts, account restrictions, or other collection activity depending on the provider’s terms. Contact customer support as soon as possible if repayment may be difficult, and avoid taking another advance to cover the first one.


