Monarch: Budget & Track Money

- 2.32K Reviews
- 4.8
- Downloads
- 500.00K
- 2.0.112
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
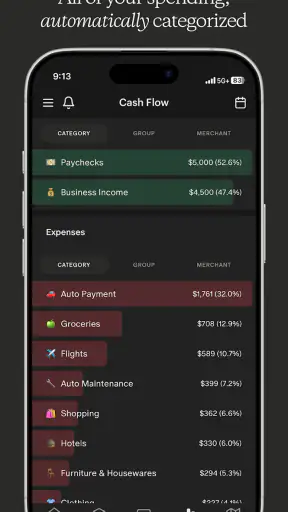
- Clear spending categories make it easy to understand where your money goes.
- Recurring transactions reduce the effort needed for regular bills and income.
- Useful charts help identify spending patterns over time.
- Budget progress indicators make overspending easier to spot early.
- Clean interface keeps everyday money tracking approachable for beginners.
Cons
- Some advanced features may require a paid subscription.
- Manual transaction entry can become tedious for frequent purchases.
- Limited bank support may affect automatic account syncing.
- Currency and regional options may vary by country.
- Detailed financial insights depend on consistent
- accurate data entry.
Review of Monarch: Budget & Track Money Appxis
I approached Monarch: Budget & Track Money as a practical finance app rather than a place to admire charts. Its real value appears when it becomes part of a repeatable routine: checking recent spending, assigning transactions to the right purpose, watching progress toward goals, and reviewing the bigger picture before making another purchase. I found it most useful as a single view of everyday money, especially for someone who has accounts, investments, and recurring expenses spread across several places.
Developed by Monarch Money, this free finance app is available to Everyone and has built a strong reputation, with a 4.8 average from around 24 thousand ratings and more than 500 thousand installs. Those figures suggest a mature audience without making the app feel intimidating. It is available for Android devices running version 7.0 or later, and the current version is 2.0.112. Optional in-app purchases range from $14.99 to $199.99 per item, so I would check the purchase screen carefully before assuming every feature is included at no cost.
Building a dependable money routine
Start with the daily view, not the perfect budget
My first recommendation is to avoid trying to create a flawless financial system on the first day. The better starting point is to connect the accounts you actually use, inspect how transactions appear, and learn whether the categories match the way you think about money. An app can show a beautiful monthly summary, but that summary is only useful when the underlying transactions make sense.
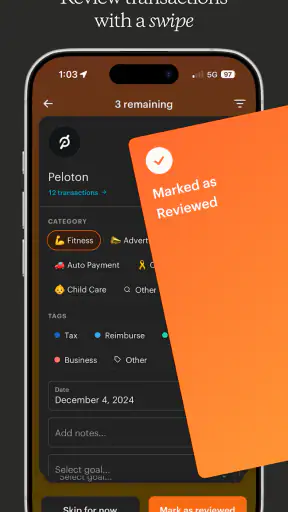
A realistic routine might begin with a quick check after groceries, transport, or a subscription payment. I would review the new entries, correct an obviously misplaced category, and move on. This takes less effort than waiting until the end of the month and trying to remember why several similar purchases were made. Over time, those small corrections make the spending view more trustworthy.
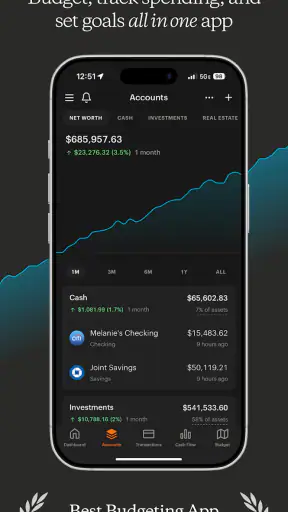
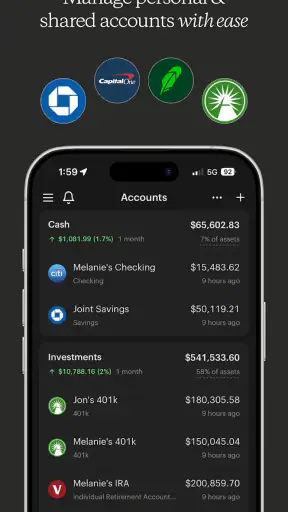
The app’s focus on spending, net worth, and investments makes it broader than a simple envelope-style budget. I can look at immediate cash flow while also keeping an eye on assets and liabilities. That combination is helpful when a person is saving for a major goal but also needs to understand whether their overall financial position is improving.
There is a trade-off, though. A broad dashboard can tempt users to check everything constantly. I think the healthiest approach is to separate quick maintenance from deeper reviews. A short transaction check can happen several times a week, while net worth and investment information deserve a calmer review less often. Mixing those activities together can turn a useful tool into a source of unnecessary worry.
A practical weekly workflow
For a household budget, I would use a simple weekly sequence. First, scan recent transactions for duplicates, unusual amounts, or entries that need a different category. Second, compare spending with the plan for the current month. Third, look at upcoming obligations and confirm that the available cash still supports them. Finally, review one goal instead of opening every available chart.
This order matters because it keeps the app grounded in decisions. If the transaction data is messy, a budget comparison may be misleading. If the budget is current but upcoming bills are ignored, a positive balance can create false confidence. Monarch works best when I treat it as a decision aid, not an automatic financial adviser.
One useful habit is to give shared expenses a consistent treatment. If two people in a household categorize similar purchases differently, the monthly totals become harder to interpret. Agreeing on a small set of categories before entering a busy month is more valuable than creating an elaborate structure that nobody maintains.
Using the app in an everyday situation
Imagine I am paid near the start of the month and have rent, utilities, groceries, commuting, and a planned savings contribution. During the first week, the app can help me see whether the routine purchases are behaving as expected. Midway through the month, an unexpected repair arrives. Rather than looking only at the repair as an isolated expense, I can consider its effect on the month’s remaining plan and on a related goal.
That is where the combined view becomes more useful than a basic bank balance. A bank app tells me what is in one account at this moment. Monarch can help me place that balance beside spending patterns, broader net worth information, and progress toward longer-term intentions. It does not remove the need for judgment, but it reduces the amount of mental arithmetic involved.
Settings worth checking early
The most important setup work is not visual customization. It is deciding how much detail I am willing to maintain. Categories should be specific enough to answer real questions, but not so narrow that every transaction becomes a chore. For example, separating groceries from restaurant spending is usually useful; creating many tiny food categories may not be.
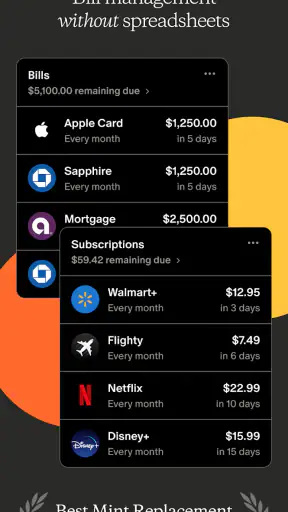
I would also inspect how recurring obligations are represented and whether the planned amounts still reflect reality. A forgotten subscription can distort a monthly plan for weeks. Reviewing those commitments during setup gives the budget a better foundation than simply accepting every automatically imported label.
Investment and net worth sections deserve their own attention. They are valuable for seeing the larger direction of finances, but they should not be treated like a daily spending limit. Market movements or account changes can make the overall picture fluctuate even when my household behavior has not changed. I prefer to use those areas for trend awareness rather than reacting to every short-term movement.
Another setting decision is how often to review and correct information. People who enjoy detailed tracking may want frequent checks, while others will stick with the app only if maintenance stays lightweight. I would rather use a modest system consistently than build an impressive budget that becomes abandoned after an unusually busy week.
Where shortcuts and repeatable habits help
Experienced use is less about discovering a secret button and more about reducing repeated decisions. I try to handle similar transactions in the same way each time, review them in batches, and keep a short mental note of categories that regularly need correction. That creates a personal shortcut: when a familiar merchant appears, I already know what to inspect.
A good monthly reset can also be faster than constant tinkering. At the beginning of a new month, I would review the previous month’s unusual expenses, adjust planned amounts where necessary, and check whether goals still match current priorities. This avoids changing the entire budget because of one exceptional purchase.
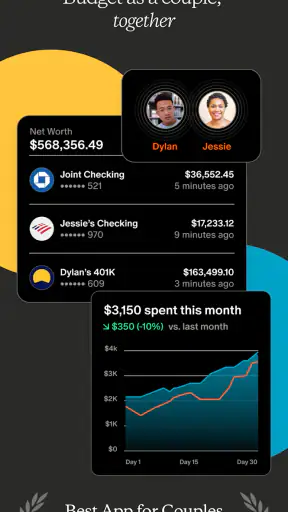
For couples or families, the faster pattern is agreement rather than speed. Decide who checks transactions, how shared purchases are categorized, and when the household reviews the numbers. Without that agreement, the app may show plenty of information while still failing to produce a shared understanding.
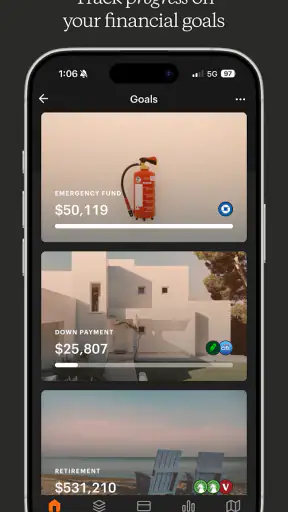
I also recommend using goals as prompts for action, not decorations on a dashboard. A goal becomes more useful when it is connected to a concrete behavior, such as reducing a flexible category or setting aside money after income arrives. If it is only viewed occasionally, it may feel encouraging without changing anything.
What the broader dashboard does well
Many budgeting apps concentrate almost entirely on monthly spending. Monarch’s wider scope is its clearest distinction. Seeing spending alongside net worth and investment tracking can help answer questions that a standard expense tracker leaves open: am I spending less but also taking on more debt, or is my overall position improving even during an expensive month?
I find that especially useful during transitions. A move, a change in income, a large purchase, or a new savings target can make a narrow monthly budget feel incomplete. The broader view gives context, although the user still needs to interpret it carefully. A rising net worth does not automatically mean cash flow is comfortable, and a temporary decline does not necessarily mean the household is making poor choices.
The app is also a better fit for people who want one place to review several financial dimensions. Someone who only needs a quick list of recent bank transactions may find this scope unnecessary. In that case, the bank’s own app or a lightweight expense tracker could be simpler and faster.
Advanced use without overcomplicating the system
The advanced advantage comes from combining views rather than staring at one metric. I might notice that a category is under control while a recurring obligation has quietly grown, or that investment progress looks positive while accessible cash is tighter than expected. Looking at these pieces together can reveal trade-offs that a single budget number hides.
One non-obvious use is to treat category corrections as a form of personal data cleanup. If the same type of transaction repeatedly lands in the wrong place, the problem is not just cosmetic. It can make future comparisons unreliable and lead to poor decisions. Spending a few minutes identifying those patterns improves the usefulness of every later review.
Another is to compare planned behavior with actual behavior before changing the plan. If I consistently exceed a category, I should first ask whether the amount is unrealistic, whether purchases are being classified incorrectly, or whether a temporary event caused the difference. Immediately cutting the category may create a budget that looks disciplined but does not match real life.
A third is to use net worth as a slower feedback loop. Spending categories can change from week to week, while net worth is better suited to observing the effect of saving, debt reduction, and investment changes over time. Keeping those time scales separate helps prevent emotional reactions to short-term noise.
Limits and points of friction
No financial dashboard can make imported information perfect. Transactions may require review, categories may need adjustment, and account information can demand attention before it becomes genuinely useful. That maintenance is not a flaw unique to this app, but it is an important cost to consider. People who want a completely hands-off experience may become frustrated.
The broad feature set can also feel like too much for a newcomer. Spending, goals, net worth, and investments each answer different questions. If I open all of them at once, the amount of information can obscure the next practical action. I would begin with spending and one goal, then add the other areas only after the basic routine feels comfortable.
There is also a difference between tracking and planning. The app can organize financial information and make patterns visible, but it cannot decide whether a purchase is wise for my circumstances. A polished chart may create a sense of control without changing habits. The user still has to make the difficult choices, especially when income is irregular or expenses are unpredictable.
The free label deserves a careful reading as well. The app itself is listed as free, while in-app purchases are available from $14.99 to $199.99 per item. I would explore the available experience first and confirm which tools require payment before building a workflow around them. That is particularly important for someone comparing it with a completely free spreadsheet or a bank-provided budgeting feature.
Who should use it, and who should choose something else?
I would recommend Monarch to someone who wants a connected view of daily spending and longer-term financial progress, and who is willing to spend a little time keeping categories and plans accurate. It is especially appealing to users who have outgrown a simple bank balance but do not want to manage several separate spreadsheets for budgets, assets, and investments.
It may also suit a household that needs a shared financial language. The value is not merely in seeing numbers; it is in discussing what those numbers mean and agreeing on the next step. A weekly review can turn scattered account activity into a more coherent plan.
I would skip it if my only requirement were recording cash purchases manually, or if I strongly prefer a minimalist tool with almost no setup. A spreadsheet may be better for someone who wants total control over formulas and layout. A bank app may be better for quick balance checks. A specialized investment tool may be preferable for someone focused almost entirely on portfolio analysis rather than household spending.
It is also not the right choice for someone who expects financial guidance to replace personal decisions. The app can organize information, but it cannot understand every obligation, emotional trigger, or unusual circumstance behind a transaction. Its strongest role is helping me notice and evaluate patterns.
My verdict after settling into the workflow
After looking beyond the first dashboard impression, I see Monarch as a finance app that rewards consistency more than enthusiasm. The best results come from a small number of repeatable actions: review transactions, keep categories sensible, connect spending with goals, and check net worth on a slower schedule. That approach makes the app feel manageable rather than demanding.
Its strongest quality is the way it brings several financial perspectives together without forcing me to calculate everything manually. Its main weakness is the maintenance and interpretation that still sit with the user. If I ignore corrections, the summaries lose credibility; if I obsess over every fluctuation, the broader view becomes stressful.
The 4.8 average and around 2.3 thousand written reviews show that many users respond positively to the experience, while the 500 thousand-plus install base indicates that it has reached beyond a tiny specialist audience. I would not choose it solely because of those figures, but they fit my impression of an established tool with a clear purpose.
For me, the deciding question is simple: do I want a financial overview that I will revisit and maintain? If the answer is yes, this app can turn disconnected spending, goals, net worth, and investment information into a more useful personal routine. If the answer is no, a simpler alternative will probably be more effective. The app is at its best when it supports a habit I can actually keep.
FAQ
What is Monarch: Budget & Track Money, and who is it designed for?
Monarch is a personal finance app designed to help individuals and households organize their money in one place. It can bring together bank accounts, credit cards, investments, loans, property, and other financial information, then present spending, net worth, recurring bills, and budgets in a single dashboard. It is especially useful for people who want a broader financial overview rather than a basic expense tracker.
Can Monarch connect to my bank accounts and financial institutions?
Yes, Monarch is built to connect with many banks, credit unions, brokerages, credit card providers, and other financial institutions. After signing in through the supported connection service, transactions and balances can be synchronized automatically. Availability and reliability may vary by institution, and some accounts may occasionally require reconnection. Before subscribing, it is worth checking whether your specific providers are supported.
Does Monarch automatically categorize transactions and support custom budgets?
Monarch automatically imports and categorizes transactions, which can save considerable time when setting up your finances. Categories can usually be edited when a purchase is classified incorrectly, and users can create rules to make future categorization more consistent. The app also supports flexible budgeting, allowing you to plan spending by category and compare your targets with actual activity over time.
Is Monarch: Budget & Track Money free to use?
Monarch generally operates as a subscription-based personal finance service rather than a completely free budgeting app. New users may receive access through a trial or promotional period, but the exact offer, price, billing schedule, and available features can change depending on the platform or region. Review the current subscription details in the official app listing before starting a trial, especially if automatic renewal applies.
Is my financial information secure when using Monarch?
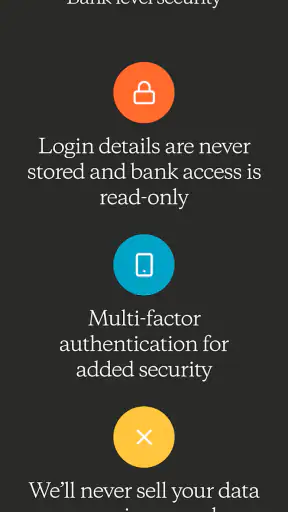
Monarch uses account connections and security practices intended to protect sensitive financial information, and bank credentials are typically handled through secure connection providers rather than stored directly in the app. However, no online service can eliminate every risk. Use a strong, unique password, enable available security protections, keep your device updated, and review connected accounts and permissions regularly.


