

Kikoff - Build Credit Quickly
Kikoff Inc.Finance
Scanned and Safe · Free
- Rating
- 4.8Out of 5
- Downloads
- 5.00M
- Android
- 7.0
Screenshots
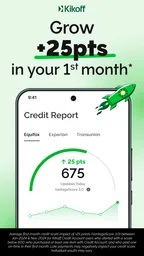
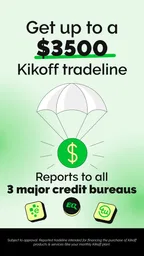
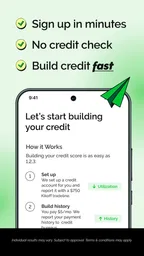
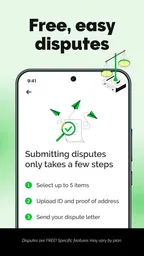
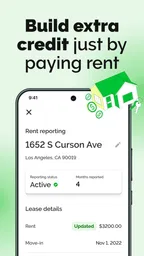
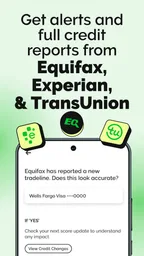
Analysis by Appxis
When I’m judging a credit-building app, I care less about flashy charts than whether the routine is understandable and manageable. Kikoff - Build Credit Quickly is aimed at people who want a structured first step, especially if applying for ordinary credit feels intimidating. It is a finance app from Kikoff, Inc., and its no-credit-check approach makes the initial prospect less daunting. I’d still treat it as one tool in a longer credit plan, not a quick fix or a substitute for keeping bills current.
What “quickly” can—and can’t—mean
The name may set expectations, so it’s worth separating quick setup from quick results. Getting into the app and understanding its basic idea can feel straightforward; building a useful credit history is a longer process that depends on consistent payments and how credit reporting works. I wouldn’t install it expecting an immediate score change or plan a major loan around a hoped-for result. Think of it as a way to start a repeatable habit, then give that habit time to matter.
That distinction is particularly useful if you’re starting with little credit history. A small, predictable account activity can be easier to manage than taking on a conventional card just to create a record. But a credit-building product only helps if the payment routine fits your real budget. Before signing up, I’d read the current terms in the app and decide what reminder or calendar habit will keep the due date from slipping your mind.
Where it fits in an ordinary week
Picture someone who has just started a first job and is trying to build a financial history while paying rent, transit costs, and phone bills. They might check Kikoff on payday, make sure the planned payment still fits after essentials, and then leave the rest of the month alone rather than repeatedly browsing for something to buy. That is a more sensible use than treating the in-app store as a shopping destination. The practical goal is consistency, not finding a reason to spend.
A less obvious benefit of this kind of setup is that it can make the credit-building action feel separate from everyday card spending. That separation may help someone who wants to avoid using a regular card for purchases they would not otherwise make. The trade-off is that it is not the same as learning to manage a revolving card balance, compare card terms, or earn rewards. If those are your goals, Kikoff is better viewed as a starting point than a complete financial education plan.
Busy periods, reminders, and recovery
The app’s simple purpose should make occasional check-ins easier than managing several credit accounts, but I would not confuse a clean interface with a guarantee that nothing can go wrong. A new phone, a changed email address, or a busy month can interrupt any financial routine. I’d keep account access details somewhere secure and put payment dates alongside rent and other fixed bills. If a payment or account detail looks wrong, deal with it promptly through the app’s available support or account tools rather than assuming it will sort itself out.
For someone balancing several obligations, the important question is not whether the app feels light to use; it is whether another payment date adds useful structure or just another thing to remember. If you already struggle to keep track of due dates, first build a reliable reminder system. And if you miss a payment, check the account and terms directly to understand the next step instead of guessing about effects on your credit. I’d avoid making promises to myself about recovery speed: credit histories don’t reset on the schedule of an app screen.
More Stories While You Read






How it compares with familiar alternatives
Compared with applying for a standard credit card, Kikoff’s appeal is the lower barrier to getting started: the app’s approach does not require a credit check to begin. A card may be more useful for someone who wants broad purchasing flexibility and is confident they can pay responsibly, but it can also introduce spending temptation and more decisions about balances and terms. A secured card is another route people consider; it may provide a more conventional card experience, while requiring the user to understand its deposit and account conditions. I’d compare the actual terms rather than assume one route is automatically better.
There is also a difference between this and simply paying ordinary bills on time. Staying current on bills is essential for financial stability, but not every bill necessarily contributes to a credit file in the same way. Kikoff is designed around a credit-building account and payment routine, so it may suit someone seeking a more directed path. Still, I would not replace responsible bill management with it. If you already have a card or loan that is being reported and can be managed safely, improving that routine may be a more direct priority.
Who benefits most, and who may prefer another route
I can see this being most useful for someone with a thin file, someone rebuilding after past difficulties, or someone who wants a small, contained first step before considering more complex products. It may also appeal to a person who prefers handling a financial task on a phone and wants the process presented in a focused way. The app is free to download, rated for Everyone, and has a 4.8 average from around 106,000 ratings; those figures suggest broad interest, but they don’t tell me whether the product fits an individual budget or credit goal.
I’d be more cautious if you need a conventional line of credit for everyday purchases, want travel or cash-back rewards, or are already stretched by existing obligations. In those situations, adding another account or payment schedule may not be the right move. Someone who wants face-to-face guidance on debt or credit disputes may also be better served by a qualified nonprofit counselor or another appropriate source of help. No app can make unaffordable commitments safe, and a credit-building routine should never come ahead of rent, food, utilities, or emergency needs.
Questions worth settling before you begin
One practical question is whether you need a credit check to start: Kikoff’s stated approach is that one is not needed. That can reduce one entry barrier, but it doesn’t mean you should skip reading the account terms or checking that your personal details are accurate. Another question is whether the app is a credit card. The experience described here is centered on a credit line used for purchases in its store, so I wouldn’t treat it as interchangeable with a general-purpose card accepted everywhere.
You may also wonder whether you have to shop often to get value from it. I’d approach the store cautiously and focus on the payment routine, not on buying things for their own sake. Before relying on any expected credit benefit, check how the account and payments are reported and what conditions apply in your case. And if you change phones or lose access, use the app’s account-recovery options and keep your contact information current; access problems are easier to handle before a payment deadline than after one.
Getting Started with Kikoff
First things first, setting up Kikoff is a breeze. You download the app, sign up with your details, and boom, you’re in. What I love about Kikoff is that it doesn’t require any credit checks to get started. So, if you’re starting from scratch or trying to rebuild after a few financial hiccups, breathing a sigh of relief is totally justified.
How Does Kikoff Work?
Okay, let’s break it down. The main idea behind Kikoff is that it gives you a credit line that you can use to purchase products from their store. Now, I know what you’re thinking, "An online store? Really?" But hear me out. The purchases are small, think ebooks or small gadgets, and the kicker is that your payments (which are super manageable, by the way) are reported to the credit bureaus. This means that as you pay off your items, your credit score gets a little boost.
User Experience
The user interface is clean and intuitive, which is always a win in my book. Navigating through the app is straightforward, and all the information you need is right there at your fingertips. I didn’t find myself scratching my head trying to figure out how things work, which is a huge plus.
Moreover, Kikoff doesn’t charge any fees. Yep, you heard that right—no hidden fees, no annual fees, nada. It’s like a breath of fresh air in a world where we’re so used to getting hit with unexpected charges.
Is Kikoff Right for You?
So, who should be jumping on the Kikoff bandwagon? If you’re someone who’s new to credit or trying to rebuild, Kikoff is definitely worth considering. It’s low-risk, and the fact that there are no fees involved makes it even more appealing. However, if you’re looking for a traditional credit card experience with bells and whistles, you might find Kikoff a bit too simplistic.
In my opinion, Kikoff is like that trusty starter bike with training wheels. It’s perfect for getting you started on the path to building a solid credit foundation without the fear of falling flat on your face.
Final Thoughts
Overall, Kikoff - Build Credit Quickly is an innovative approach to tackling the sometimes daunting world of credit scores. It’s simple, effective, and most importantly, it’s user-friendly. While it might not be the ultimate solution for everyone, it’s undoubtedly a fantastic stepping stone for those looking to take control of their financial future.
So, if you’re ready to give your credit score a little nudge in the right direction, Kikoff might just be the app for you. And who knows, maybe one day you’ll look back and wonder how you ever managed without it!
Everyday performance and device fit
For a finance app like this, I judge speed by how quickly I can find the relevant account information and complete a brief check-in, not by animations or elaborate dashboards. Kikoff’s focused layout makes that kind of occasional use feel more appropriate than leaving it open throughout the day. I wouldn’t expect a credit-building account to require constant attention; a short review when planning monthly payments is the more sensible pattern.
Heavy use is likely to happen around practical moments: reviewing the account before payday, checking a purchase decision, or confirming a payment routine while organizing bills. The useful habit is to pause before buying anything in the store and ask whether you would want that item without the credit-building context. That small check helps keep the app’s purpose from turning into an excuse for unnecessary spending.
On reliability, I value a predictable routine more than frequent visits. Keep your contact details current, save a payment reminder outside the app, and avoid waiting until the last minute to resolve an access issue. These are ordinary safeguards, but they matter because a phone app is only one part of managing a financial account. The same approach also makes recovery less stressful if you replace a device or temporarily lose access.
Kikoff is listed as requiring Android 7.0 or later, so owners of older Android devices should check compatibility before planning to use it. The current version is 1.141.2160, and the app has more than one million installs. That scale can be reassuring when choosing a familiar finance tool, although it cannot guarantee that every device or account situation will behave identically. I’d keep the app updated where possible and make sure I can still reach account information if my phone is unavailable.
My performance verdict is that Kikoff is best understood as a low-friction, occasional-use companion for a deliberate credit routine—not an app that can make credit building instant or effortless. Its free download and approachable setup lower the barrier to trying that routine, while its store-based credit-line model is narrower than a standard card. With realistic expectations, careful payment reminders, and no impulse shopping, I can see why it may work well as a first step; anyone seeking broader borrowing flexibility should compare other options before choosing.
Pros
- User-friendly interface for all ages.
- Quick setup with minimal requirements.
- Free credit score tracking available.
- Personalized financial tips included.
- Secure data encryption ensures privacy.
Cons
- Limited credit building options.
- Requires bank account for verification.
- No mobile app notifications.
- Customer support only via email.
- No live chat support option.
Kikoff - Build Credit Quickly FAQ
What is Kikoff and how does it help in building credit?
Kikoff is a financial app designed to help users build their credit score quickly and efficiently. It offers a credit line that reports to major credit bureaus, allowing users to improve their credit score by making regular, on-time payments. This can be especially beneficial for those with no credit history or a poor credit score.
How much does Kikoff cost to use?
Kikoff is known for its affordability, offering a low-cost membership plan. Users can start with a minimal monthly fee, which makes it an accessible option for those looking to build credit without significant financial investment. It's important to check the app for the latest pricing information as it may vary over time.
Is Kikoff safe to use for managing my credit?
Kikoff takes user security seriously, implementing industry-standard encryption and security measures to protect personal and financial information. It’s always recommended for users to review the app’s privacy policy and user reviews to ensure they are comfortable with how their data is handled.
Can Kikoff guarantee an improvement in my credit score?
While Kikoff provides tools and a credit line aimed at helping users build credit, it cannot guarantee a specific improvement in credit score. Success depends on various factors, including timely payments and individual financial behavior. Users should use Kikoff’s services responsibly to maximize their potential credit score improvements.
How quickly can I expect to see changes in my credit score with Kikoff?
The timeline for credit score improvements with Kikoff can vary. Typically, users may start to see changes after several months of consistent, on-time payments. It’s important to note that while Kikoff reports to credit bureaus monthly, the impact on a user’s credit score can depend on their broader financial behavior and credit history.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Kikoff Inc.
- Package Name
- com.kikoff
- Version
- 1.181.3223
- Android
- 7.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at hello@kikoff.com, visit https://kikoff.com, or view the https://kikoff.com/privacy-policy.html.