Jim: sell & get paid instantly

- 470.00 Reviews
- 4.3
- Downloads
- 100.00K
- 1.4.19
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Instant payouts help sellers access earnings without long processing delays.
- Simple selling tools make it easy to list products from a mobile device.
- Useful for local transactions and quick exchanges with nearby buyers.
- Payment tracking helps users monitor completed sales and incoming funds.
- A focused marketplace experience keeps selling tasks straightforward.
Cons
- Availability and features may vary depending on your country or region.
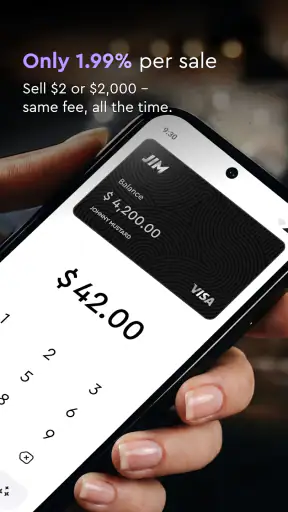
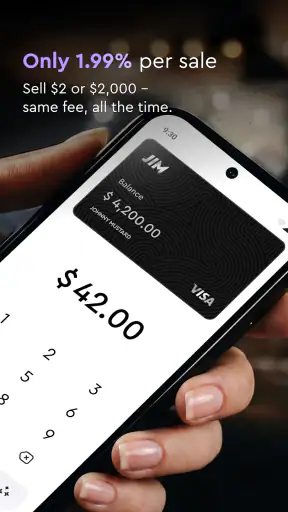
- Transaction fees can reduce the final amount sellers receive.
- Users may need to verify their identity before accessing payments.
- Local marketplaces can have limited buyer activity in smaller areas.
- Disputes or refunds may take time to resolve after a sale.
Review of Jim: sell & get paid instantly Appxis
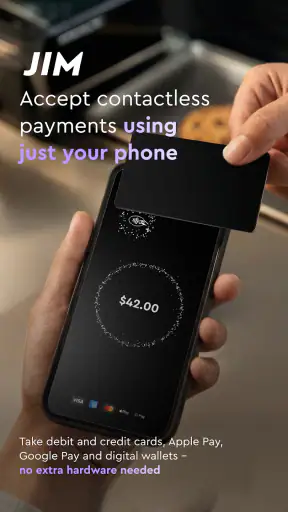
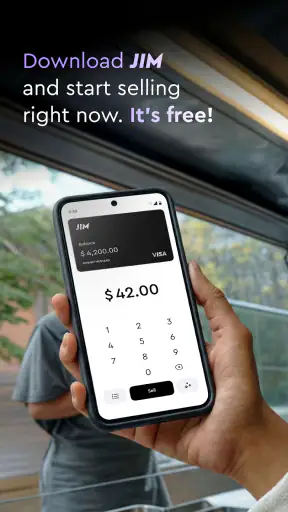
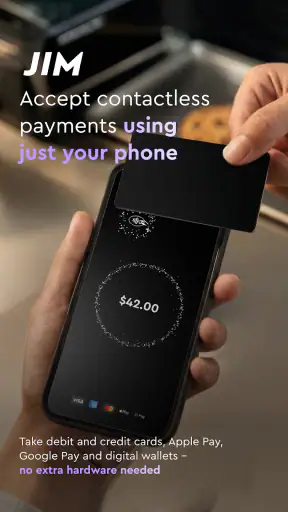
Jim: sell & get paid instantly is a finance app from CloudWalk that turns a compatible phone into a mobile card reader. I approached it as a tool for people who need to take payments away from a fixed checkout, rather than as a general banking app. That distinction matters: its value appears when a customer is standing in front of you and you want to complete a sale without carrying a separate terminal.
My first impression is that Jim is focused on reducing equipment. Instead of building a payment setup around a counter, I can imagine using the phone I already carry as the center of a small selling workflow. That makes it interesting for independent sellers, market stalls, mobile services, event vendors, and anyone who occasionally needs to accept card payments in different places.
The app is free, is rated for Everyone, and has reached over one hundred thousand installs. Its average rating is 4.3 from around two thousand ratings, with roughly five hundred written reviews. Those figures suggest a product that has found a real audience, while also leaving enough room for individual experiences to vary depending on phone, network, customer card, and selling environment.
Where connectivity becomes part of the payment experience
A card-reader app is more dependent on its surroundings than an ordinary finance app. With Jim, the quality of the connection is not a minor convenience: it can shape whether a sale feels immediate or uncertain. When I am in a place with a stable mobile signal or reliable Wi-Fi, the phone can fit naturally into the transaction. I can focus on the customer instead of moving between a cash box, a separate terminal, and a receipt process.
The opposite situation is easy to picture. A vendor at a crowded outdoor event may have a busy network, weak reception, or a phone switching between connection types. Even if the app itself opens normally, the payment journey may feel slower when the transaction has to communicate with payment services. That is why I would treat connectivity as part of the equipment checklist, alongside battery level and a clean screen.
The practical lesson is simple: Jim can simplify the hardware, but it cannot remove the need for a dependable payment connection. I would test it in the actual places where I sell before relying on it for a high-pressure event. A short test at home proves that the app launches; it does not prove that a payment will feel smooth in a crowded venue or a building with poor reception.
This also affects how I would explain the process to customers. If a transaction takes longer than expected, silence makes the delay feel worse. I would tell the customer that the payment is being processed, avoid repeatedly tapping the phone, and wait for a clear result before trying again. That small habit helps prevent confusion between a delayed response and a genuinely failed attempt.
Why the phone format works well in mobile selling
The strongest use case is a seller who moves around. A home-based baker delivering an order, a repair professional collecting payment after a visit, or a craft seller working from a temporary table does not necessarily want a traditional checkout station. Jim is designed around that mobile reality, and the phone-first approach can make a payment setup feel less intimidating for someone starting small.
I also see a useful role for occasional sellers. If I only accept payments at periodic markets or short-term events, carrying a dedicated terminal may feel excessive. An app that lets the phone handle the reader role is easier to keep with the rest of my everyday tools. The trade-off is that the phone becomes more important during the sale, so I would not treat it as just another device in my pocket.
Before opening for business, I would charge the phone, close unrelated apps, clean the display, and keep the device within reach. I would also prepare a backup way to communicate with the customer if the transaction needs checking. These are not glamorous preparations, but they matter more in a mobile setup than they do at a permanent register.
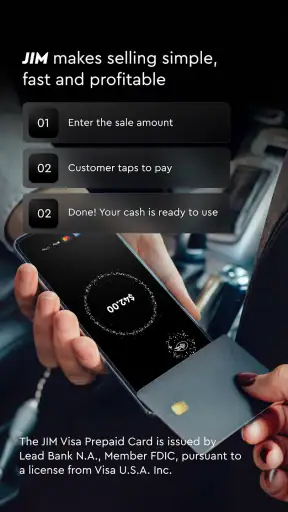
A realistic example would be a weekend food seller taking orders from a small stand. During a quiet period, Jim could keep the payment step close to the order-taking process. During a rush, however, the seller needs a clear routine: confirm the amount, let the customer complete the payment interaction, wait for the final status, and only then move to the next order. The app may reduce hardware, but it does not replace good queue discipline.
What changes when the network is weak
Connectivity problems are particularly awkward in finance because guessing is risky. If the screen appears to pause, I would not immediately assume that the payment failed. I would first give the transaction time to return a definite status, then check the app before starting another attempt. Repeating a payment too quickly can create uncertainty for both sides, especially when the customer sees activity on their card or account.
If a transaction does fail, I would record the order details and the visible result before trying again. A quick note with the customer’s name or order number can help me reconcile the sale later. This is one of the less obvious habits that makes a phone-based reader safer to use: the app handles the payment interaction, but I still need a simple human record for anything interrupted by a connection problem.
I would also avoid switching networks in the middle of a payment unless the app clearly returns to a safe starting point. Moving from mobile data to public Wi-Fi may solve a signal problem, but it can also add another variable while the transaction is unresolved. My preference would be to stabilize the connection first, then reopen the payment flow only when the previous attempt has a clear outcome.
For a business that cannot tolerate this kind of uncertainty, a conventional terminal or a second payment method may be the better primary option. Jim is more appealing when portability and low equipment overhead matter more than having a dedicated, purpose-built device at every moment.
Recovering from interruptions without making a mess
Phone-based payments introduce ordinary phone problems as well as payment problems. A call, an accidental screen lock, a low battery warning, or an app interruption can break the seller’s concentration. I would avoid placing the phone where customers can bump it, and I would keep the payment amount visible to both sides before starting. That reduces the chance of having to reconstruct what happened from memory.
When a payment is interrupted, my recovery order would be cautious: check whether Jim shows a completed or unsuccessful result, confirm the customer’s side without asking them to pay again immediately, and keep the order marked as pending until the situation is clear. If there is no definite answer, I would rather pause the sale than create a duplicate charge.
This is also where the difference between Jim and cash becomes clear. Cash gives an immediate physical signal, while a digital payment depends on a chain of devices and services. Compared with a standard card terminal, Jim may be lighter to carry, but the phone itself becomes the point of failure. A dedicated terminal is often easier to reserve exclusively for payments, whereas a personal phone is exposed to notifications, calls, storage pressure, and battery use from other tasks.
I would therefore set a personal rule: never promise that an order is paid based only on a customer saying they tapped or approved something. I would wait for Jim to display the completed result. This protects the seller without making the interaction awkward, because the rule can be explained as a normal checkout step rather than a lack of trust.
Using mobile data carefully
Jim is not the kind of app I would casually leave running all day without thinking about the phone’s resources. Payment moments are short, but sellers may spend hours at an event, and a phone that starts the day with limited battery or a weak data plan can become a liability. I would check my connection before leaving, carry a charger or power bank, and avoid relying on a congested public network when a more stable option is available.
Data-conscious use does not mean trying to interfere with the payment process. It means preparing the environment so the app has the best chance of completing its job. I would update the app before a major selling day rather than immediately before opening, test the device after the update, and keep nonessential downloads and streaming off the phone while taking payments.
The current version is 1.4.19, and the app requires Android 7.0 or later. For an Android user with an older device, checking compatibility before planning a new payment workflow is important. A phone that technically runs the operating system may still be a poor business tool if its battery is worn out, its screen is unreliable, or its connection drops frequently.
I would also separate personal and selling habits where possible. A phone full of alerts can make it harder to notice the final payment state. Muting distractions during a busy period, keeping the brightness practical, and using a stable surface for customer interaction all improve clarity without requiring extra equipment. These small choices are especially useful because Jim places the payment action on a device that normally does many unrelated jobs.
Who should choose Jim, and who should look elsewhere
I think Jim is a strong fit for small sellers who value mobility, already carry a compatible Android phone, and want to avoid adding a separate card reader to their kit. It is also worth considering for service providers who collect payment at the customer’s location and for people testing a small selling idea before investing in a more elaborate checkout arrangement.
I would be more cautious if I ran a busy shop with several employees, multiple checkout points, or a constant stream of transactions. In that setting, a dedicated terminal and a more structured point-of-sale system may be easier to manage. The phone format is convenient for one person, but a larger operation may need clearer staff controls, a shared workflow, and equipment that remains available even when one employee’s phone is busy or unavailable.
It may also be the wrong choice for someone who regularly sells in places with unreliable reception. In that case, the central question is not whether Jim is easy to carry; it is whether the payment environment is dependable enough for the business. I would not choose any connection-dependent payment method as my only option for remote or crowded locations without testing it there first.
Compared with cash, Jim removes the need to handle change and can suit customers who prefer card payments, but it introduces digital uncertainty. Compared with a traditional card terminal, it is more portable and potentially simpler to carry, while making the seller’s phone, battery, and network more important. Compared with a broader finance app, its identity is narrower and more practical: it is about accepting payment at the point of sale rather than managing every part of a business.
What I would check before the first real sale
I would begin by installing Jim on the phone that will actually be used during work, not merely on a newer personal device that will stay at home. I would confirm that the Android version meets the requirement, open the app while connected, and walk through the payment setup far enough to understand the screens and the order of actions.
Next, I would test the phone in the real selling position. If I sell from a stall, I would test at the stall. If I collect payments during home visits, I would test from the areas where customers normally meet me. The goal is not just to see whether the app opens; it is to learn how the phone behaves when held at the angle, distance, and pace of an actual transaction.
I would also decide in advance how I will handle a delayed result. A written procedure can be as short as: wait, check the status, do not repeat immediately, and record the order if clarification is needed. That may sound overly careful for a free app, but payment mistakes are more expensive than a few seconds of preparation.
Finally, I would tell customers what to expect without overexplaining. I would state the amount, let them complete their part, and wait for the confirmation shown in Jim. A calm, consistent routine makes the phone feel like a proper checkout tool rather than an improvised workaround.
My connectivity verdict
After looking at Jim as a real mobile payment tool, I see its main appeal in the balance between portability and simplicity. CloudWalk has positioned it for sellers who want the phone to play the role of a card reader, and that can be genuinely useful when a separate terminal would be inconvenient. The free price also lowers the barrier for someone exploring mobile sales, while the Everyone age rating keeps the app approachable for a broad audience.
My recommendation comes with a clear condition: choose it because your selling environment has a dependable connection and because you are comfortable making the phone part of the checkout routine. Do not choose it solely because carrying less equipment sounds attractive. A lightweight setup still needs preparation, battery awareness, careful confirmation, and a sensible recovery plan when the network or device interrupts the flow.
For a solo seller, a mobile professional, or an occasional vendor, Jim can be a practical alternative to carrying a dedicated reader. For a high-volume business or a location where connectivity is unpredictable, I would compare it closely with dedicated payment hardware and keep another method available. In my view, the app is most convincing when used deliberately: test it in context, protect the payment routine from distractions, and treat every unclear transaction as something to verify rather than guess.
That makes Jim less of a magic replacement for every checkout setup and more of a focused tool for a specific job. When the phone, network, and workflow are ready, it can make taking card payments feel much more convenient. When any of those three pieces is fragile, the convenience quickly becomes a responsibility the seller has to manage.
FAQ
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a mobile marketplace designed to help users list items for sale and receive payment through the app. It focuses on making local or direct selling more convenient by combining product listings, buyer communication, and payment-related features in one place. Availability and supported services may depend on your country.
How do I sell an item using Jim?
To sell an item, you generally need to create an account, add clear photos, write an accurate description, choose a category, and set a price. Providing honest information about the item’s condition can help attract serious buyers. Before publishing a listing, review the delivery, collection, and payment options available in your region, as these may vary by location.
Can I really get paid instantly through the app?
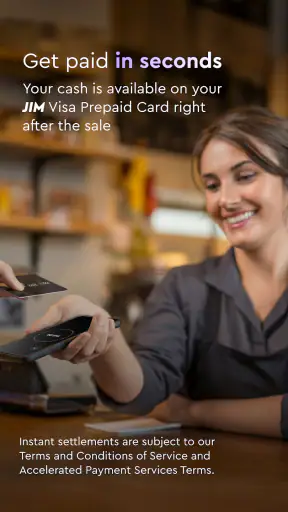
The app promotes fast payment for completed sales, but the exact timing may depend on the payment method, buyer confirmation, account verification, and local banking or platform rules. “Instant” does not necessarily mean that funds will appear immediately in every situation. Check the current payment terms, possible processing times, and any applicable fees before accepting a transaction.
Is Jim safe to use for buying and selling?
Jim may include features intended to support safer transactions, such as account controls, in-app communication, and payment handling. However, users should still take normal precautions: avoid sharing passwords or verification codes, keep conversations within the platform, inspect items carefully, and be cautious of requests to move payments outside the app. Never ignore suspicious behavior or unusually attractive offers.
Are there fees or requirements for using Jim?
Depending on the transaction and your location, Jim may apply service charges, payment fees, listing costs, or other deductions from a sale. Some features may also require identity or account verification before they become available. Because pricing and eligibility rules can change, review the app’s latest fee information, terms of service, and privacy policy before listing an item or completing a purchase.


