Instant Cash Advance

- 58.00 Reviews
- 4.6
- Downloads
- 10.00K
- 1.7.4
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast application process with funds often available quickly
- Clear repayment schedule helps users plan upcoming payments
- Useful for handling unexpected short-term expenses
- Mobile access makes applying convenient from almost anywhere
- May help users with limited credit access explore borrowing options
Cons
- High fees or interest can make borrowing expensive
- Short repayment periods may strain a tight budget
- Late payments could lead to additional charges
- Approval and loan terms may vary by applicant
- Repeated advances can encourage a cycle of borrowing
Review of Instant Cash Advance Appxis
When an unexpected bill lands before payday, the appeal of an instant cash advance is obvious: open an app, request help, and try to close the gap without visiting a branch. That is the situation Instant Cash Advance is built around. I reviewed it as a finance app from Janssen Herman, and my overall impression is that it is aimed at people who value a quick, phone-based starting point more than a full personal-finance toolkit.
The app is free to install and carries an Everyone content rating, which makes it easy to try from a basic Android device. It has an average rating of 4.6 from around 1.8 thousand ratings, with over 10 thousand installs. Those figures suggest that it has found a modest but interested audience, although they should not be treated as a promise that every application will end in an approved advance.
From a sudden cash gap to a lending decision
Starting with the right expectation
The most important first step is deciding whether this kind of service matches the problem. Instant Cash Advance is not something I would approach as a budgeting app, a savings account, or a long-term debt-management tool. Its purpose is narrower: help a user explore access to fast funds through a mobile workflow.
That distinction matters in everyday life. Imagine a utility payment is due tomorrow, your salary arrives later in the week, and you need to investigate a short-term option quickly. The app can be a practical place to begin that search. If, instead, you are trying to reduce recurring debt or understand why your monthly spending is out of control, a budgeting application, bank adviser, or credit-union conversation is likely to be more useful.
I also recommend entering the process with a clear repayment plan already in mind. An advance can solve a timing problem, but it does not remove the underlying obligation. Before submitting anything, I would write down the bill, the date income is expected, and the amount that can realistically be repaid without creating another shortfall. The fastest application is not automatically the safest financial choice.
Beginning the application journey
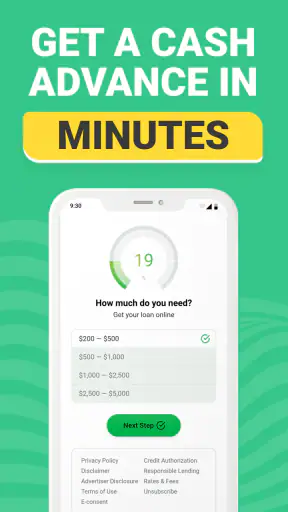
The first advantage is convenience. A phone-based application removes the need to search for a branch or make several calls just to learn whether an option may be available. The store summary presents Instant Cash Advance as a way to access fast funds through a trusted loan app, while the short description focuses on an instant cash advance. In practical terms, I see it as an initial request and matching route rather than a substitute for reading the final lending terms.
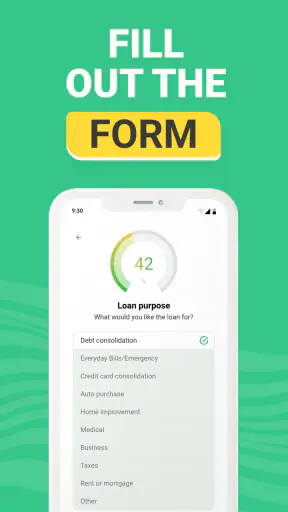
That is an important handoff. The app may help collect the information needed to assess a request, but the user still has to move from a short mobile form to a real financial decision. I would slow down at every screen that asks for personal or financial details, check that the information is accurate, and avoid guessing simply to move forward. A wrong income or employment detail can create confusion later, especially when the request reaches the party responsible for evaluating it.
One useful habit is to prepare the basic facts before opening the app: the amount needed, the reason for the request, the expected repayment date, and a simple account of regular income and essential expenses. This makes the process less stressful and reduces the temptation to request more than the immediate problem requires. It also helps reveal whether borrowing is genuinely necessary or whether delaying a nonessential payment would be less costly.
What happens after information is submitted
Once a request leaves the app, the process is no longer entirely in the reviewer’s hands. The information may need to be assessed by a lender or financial service involved in the next stage. That handoff is where users should separate the convenience of the interface from the actual terms of an offer.
I would look carefully for the total repayment amount, any applicable fees, the repayment schedule, and the consequences of missing a payment. A large-looking advance can become difficult to manage if the timing or total cost does not fit the borrower’s income cycle. The phrase “instant” describes the intended speed of the experience, not a guarantee that every person will receive money immediately or under identical conditions.
This is also the point where privacy deserves practical attention. A finance app asks users to treat their information more carefully than they would treat a casual shopping app. I would review each request for personal details, confirm that the information is necessary for the application, and avoid continuing if I cannot understand who will receive it or what decision it supports. Convenience should never replace informed consent.
The handoff from app to account
The outcome a user wants is simple: funds reaching the appropriate account in time to cover the urgent need. Yet the path between submitting a request and seeing money available can involve review, eligibility checks, acceptance of terms, and transfer timing. That means the app should be used early enough to leave room for those stages, rather than opened minutes before a payment deadline.
For a realistic scenario, consider someone whose car is needed for work and who faces an unexpected repair bill. The app may offer a faster way to explore a cash advance than visiting multiple providers. The user still needs to compare the proposed repayment burden with the cost of postponing the repair, using public transport, asking an employer about an advance, or contacting a bank. The right answer depends on the total cost and the certainty of future income, not just on how quickly the first screen appears.
Another useful workflow is to save the final terms outside the app after accepting an offer, whether by keeping the confirmation available or recording the repayment dates in a calendar. I would not rely on memory for an obligation that may affect the next pay cycle. A calendar reminder several days before repayment can give the user time to move money or contact the provider if a problem arises.
What a successful result looks like
A successful experience is not merely receiving funds. It is receiving an amount that solves the immediate issue, understanding the complete cost, knowing when repayment is due, and avoiding a second emergency caused by the first one. Instant Cash Advance is most useful when it helps a disciplined borrower move through that decision quickly without losing sight of those details.
I like the focused nature of the app. Someone who needs to investigate a short-term advance does not have to navigate investment charts, spending categories, or unrelated banking tools first. That directness can be valuable under pressure. The free price also lowers the barrier to exploring the service, although free access to an app should not be confused with a free loan or a cost-free borrowing experience.
The current version is 1.7.4, and the app supports Android starting with version 6.0. That compatibility makes it approachable for people using older Android phones rather than only the newest devices. I would still keep the operating system updated where possible, use a screen lock, and avoid completing a sensitive application on a shared or unsecured device.
Where the workflow becomes uncomfortable
The main friction is the gap between a quick request and a final financial outcome. A clean mobile flow can make borrowing feel simpler than it really is. Approval, amount, timing, and terms depend on the assessment process and the details presented during the application. Anyone looking for certainty before entering information may find this type of app less reassuring than speaking directly with a known bank or credit union.
There is also a risk of using a short-term advance for a problem that is not short term. If the same bill appears every month, borrowing repeatedly may hide a structural budget issue. In that situation, I would choose a debt counselor, a bank conversation, a benefits adviser, or a spending plan before opening another advance application. The app is poorly suited to users who need ongoing financial guidance rather than a one-off route to emergency funds.
People who dislike sharing financial information through mobile forms should also think carefully before proceeding. A branch visit or direct conversation may feel slower, but it can provide more opportunity to ask questions in real time. Instant Cash Advance is better for users who are comfortable navigating a digital request and who are prepared to inspect every condition themselves.
How it compares with familiar alternatives
Compared with a traditional bank, this app offers a more direct mobile-first starting point. A bank may be preferable when the customer already has an established relationship, wants to discuss several borrowing options, or needs a larger, more structured product. The bank route may take more effort, but personal assistance can be valuable when the situation is complicated.
Compared with a credit union, the app may feel more immediately accessible, while the credit union may offer a more personal assessment or a broader conversation about affordability. Membership requirements and local availability can affect that comparison, so I would not assume the fastest digital route is the cheapest or most suitable one.
Compared with a credit card cash advance, the app presents a separate way to explore short-term funds rather than automatically using an existing line of credit. A credit card can be convenient for someone who already understands its fees and repayment structure, but it can also encourage repeated borrowing. The sensible choice is the option whose total cost and repayment date are clearest, not the one with the most familiar name.
Compared with asking an employer for a salary advance or negotiating a payment extension, Instant Cash Advance may be easier to access privately and quickly. On the other hand, an employer arrangement or delayed bill may avoid some borrowing costs altogether. I would check those possibilities before accepting an offer, especially when the amount needed is small and the income date is certain.
Small decisions that improve the experience
My first practical tip is to request only what closes the immediate gap. Asking for extra money because the application is already open can turn a manageable repayment into a stressful one. The second is to compare the total amount repaid, not just the amount deposited. The third is to match the repayment date with the actual date money becomes available, allowing for weekends, holidays, and normal banking delays.
A fourth tip is to treat every handoff as a fresh checkpoint. When the app presents an offer or moves the request to another service, I would read the new terms rather than assuming they match the initial impression. A fifth is to keep a record of the request and repayment schedule. This is especially helpful if someone is managing several bills at once and needs to distinguish a completed application from an active obligation.
Finally, I would stop if the process becomes unclear. Pressure to continue, unexplained conditions, or a repayment amount that does not fit the budget are valid reasons to step back. A short delay while comparing alternatives is usually better than accepting a commitment that creates a larger problem after payday.
Who should use it and who should skip it
I would recommend Instant Cash Advance to an Android user facing a specific, temporary cash shortage who wants a convenient way to explore an advance and is willing to read the terms carefully. It is particularly suitable for someone who already knows the amount required and has a credible repayment plan.
I would skip it if the need is recurring, if repayment depends on uncertain future income, or if the user is already juggling several loans. I would also choose a direct bank, credit union, employer option, or payment negotiation when personal advice matters more than speed. The app’s focused design is a strength for a narrow emergency, but that same focus means it should not be mistaken for a complete financial safety net.
My final assessment after following the full path
Instant Cash Advance succeeds as a focused entry point for people investigating emergency borrowing from an Android phone. Its free availability, Everyone rating, broad support for older Android devices, and straightforward purpose make it easy to consider when time is tight. Janssen Herman has kept the concept centered on accessing a cash advance rather than surrounding it with unrelated finance features.
My reservation is not about the idea of a mobile application; it is about the responsibility that begins after the request is submitted. The real value depends on the offer, the complete repayment terms, the timing of the transfer, and the borrower’s ability to repay without another advance. I would use it as one option in a comparison, not as an automatic answer.
If you approach it with a fixed amount, a written repayment plan, and patience for every handoff, it can be a useful tool for a short-lived cash gap. If you need lasting debt support or certainty that only a personal adviser can provide, a different route will serve you better. That balance is what makes this app worth considering, but not worth using casually.
FAQ
What is Instant Cash Advance, and how does it work?
Instant Cash Advance is a financial service app designed to help eligible users request short-term funds through their mobile device. After creating an account, you generally provide personal, employment, banking, and income information so the service can evaluate your application. If approved, the amount, fees, repayment schedule, and delivery method should be shown before you accept the offer. Availability and approval are not guaranteed.
Is Instant Cash Advance a legitimate and safe app to use?
Before using Instant Cash Advance, download it only from an official app store and verify the developer, privacy policy, customer support details, and user reviews. A legitimate service should clearly explain its fees, loan terms, data practices, and licensing or lending partners. Avoid entering sensitive information if the app requests unnecessary permissions, promises guaranteed approval, or asks for an upfront payment before explaining the agreement.
How much money can I borrow, and how quickly will I receive it?
The amount available through Instant Cash Advance depends on factors such as your income, banking history, location, eligibility, and the provider’s policies. Some applications may provide a decision quickly, but approval does not always mean immediate access to funds. Standard bank processing times, weekends, holidays, verification checks, and optional expedited-transfer fees can affect when money actually reaches your account.
What fees, interest, and repayment terms should I expect?
Carefully review the complete offer before accepting an Instant Cash Advance. Depending on the provider and your location, costs may include interest, an origination or service fee, subscription charges, late-payment fees, or a fee for faster delivery. Confirm the annual percentage rate when available, the total repayment amount, the due date, and whether automatic withdrawals will be made from your bank account.
What information and permissions does Instant Cash Advance require?
An application for Instant Cash Advance may request identifying details, contact information, employment or income data, bank-account information, and documents needed for verification. Read the privacy policy to understand how this information is collected, stored, shared, and retained. Grant only permissions that are necessary for the service, and never share passwords, verification codes, or banking credentials outside the app’s secure process.


