Instant Cash Advance: CashHoop

- 1.36K Reviews
- 4.6
- Downloads
- 1.00M
- 1.0.15
- Version
Screenshots
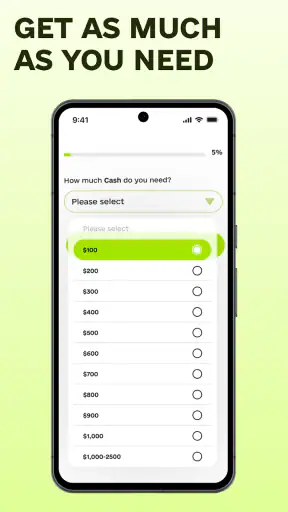
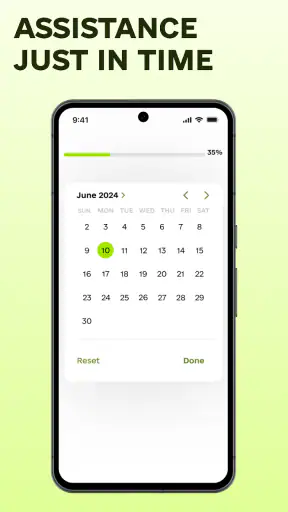
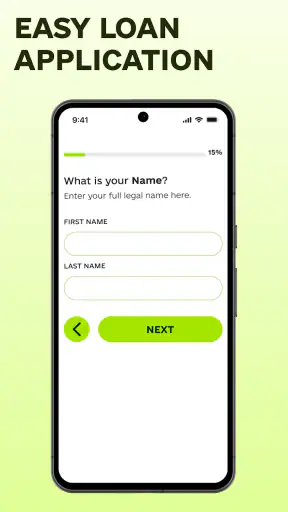
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast application process with minimal paperwork
- Clear repayment schedule shown before accepting an advance
- Useful for covering unexpected short-term expenses
- Simple interface that is easy for first-time users
- May help users with limited traditional credit options
Cons
- Advance fees can make borrowing expensive
- Repayment deadlines may arrive sooner than expected
- Availability and terms vary by state and eligibility
- Late payments could lead to additional charges or account issues
- Requires sharing sensitive personal and financial information
Review of Instant Cash Advance: CashHoop Appxis
When an unexpected bill lands between paydays, the difficult part is often not deciding what to buy but finding a practical way to cover the timing gap. CashHoop is built around that exact situation: it is a finance app from Biskup Apps that focuses on requesting a cash advance through a phone. I found its appeal easy to understand because the experience is aimed at speed rather than long-term money management. You open the app when a short-term problem appears, work through the available process, and use the result for an immediate expense or tax-related need.
The important point is that CashHoop is a short-term access tool, not a replacement for a budget, savings account, or full banking service. That distinction shaped my impression of it. The app can be useful when timing is the main issue, but it deserves a careful look before anyone treats an advance as extra income. I would recommend approaching it as a temporary bridge and checking every repayment detail before accepting anything.
CashHoop’s central promise: getting through a short cash gap
The app’s main capability is requesting an instant cash advance. In practical terms, that means CashHoop is designed for moments when an expense cannot wait until your next normal income arrives. The store summary also presents tax filing and unexpected bills as relevant situations, so the intended audience is broader than someone dealing with one particular kind of emergency.
I like the focus because it keeps the purpose clear. Many finance apps try to combine spending accounts, investing, credit monitoring, coupons, and budgeting into one crowded dashboard. CashHoop takes a narrower route. If your immediate question is, “How can I handle this bill before my cash flow catches up?” the app’s reason for being is obvious from the start.
That narrow focus is also the first limitation. A cash advance does not remove the expense; it changes when the money is available and when the obligation must be dealt with. I would not use it to support a recurring lifestyle cost, cover a monthly shortfall that keeps returning, or make a purchase that can simply wait. The feature makes most sense when the expense is genuinely time-sensitive and I already understand how the advance will fit into my next income cycle.
CashHoop is free to install and carries an Everyone content rating, which makes it approachable for a wide audience. The app has passed the early-discovery stage too: it has more than a million installs, an average rating of 4.6 from roughly 26 thousand ratings, and about 1.4 thousand written reviews. Those figures suggest that many people are willing to try it, although popularity should never replace checking the actual terms of a financial transaction.
What the capability changes in an everyday emergency
Imagine a household appliance stops working a few days before payday. Waiting may mean losing access to something essential, while putting the charge on a high-interest card can create a different problem. In that situation, a cash-advance app can reduce the immediate pressure by concentrating on the gap between the bill and the next available income.
That convenience is the real benefit I noticed. The phone becomes the starting point for the request instead of a physical branch, a long appointment, or a search through several unrelated financial products. For someone who is already comfortable managing sensitive money tasks on a mobile device, this can feel more direct than traditional alternatives.
There is a psychological trade-off, though. Fast access can make a decision feel smaller than it is. A request completed on a phone may seem like a simple tap, while the repayment still affects the rest of the month. I found it helpful to pause before moving forward and write down the expense, the expected repayment timing, and the money that must remain available for rent, food, transport, and existing commitments.
How I would approach the process in practice
CashHoop is currently at version 1.0.15 and supports devices running Android 7.0 or newer. That gives it a broad reach for Android users, including people who do not own a recent phone. The app’s purpose is straightforward, but the responsible workflow begins before submitting a request: I would first decide whether the expense is urgent, then verify that the next income event can realistically absorb the obligation.
The first useful habit is to separate qualification from affordability. Being able to request or receive an advance does not automatically mean it is comfortable to repay. I would treat the app’s approval path as one question and my personal budget as another. Even if the process feels quick, I would not skip the screen that explains the amount, timing, and any applicable cost.
The second habit is to use one advance for one clearly defined need. Mixing a tax payment, a utility bill, and discretionary spending makes it harder to understand what the money solved. When an advance is tied to a single purpose, I can later judge whether it actually helped or merely postponed several problems at once.
A third practical tip is to prepare the information I may need before opening the app. Having the bill amount, due date, and a realistic view of the next paycheck makes the decision less emotional. It also reduces the temptation to request more than the original need. I would keep the requested amount as close as possible to the actual gap rather than treating the available limit as a spending target.
For tax-related use, I would be especially cautious. A tax deadline can be predictable, but the amount owed may still compete with ordinary household expenses. CashHoop may help with timing, yet I would compare the total cost and repayment pressure with filing arrangements, a planned savings transfer, or speaking directly with the relevant tax authority. The app should be one option in the decision, not an automatic answer.
Where the app fits better than usual alternatives
Compared with asking friends or family, CashHoop offers a more private and structured starting point. That can matter to someone who does not want to explain a personal emergency or negotiate an informal repayment arrangement. The trade-off is that a digital financial product still comes with its own conditions, so privacy does not mean the decision is consequence-free.
Compared with a credit card, an advance may feel more targeted because it is connected to a specific short-term need rather than an open spending line. However, a card can sometimes be more suitable for a planned purchase if its terms are already familiar and the balance can be cleared without creating a new cycle of debt. I would compare the complete cost and timing rather than assuming the newer app is automatically cheaper.
Compared with a bank loan, the attraction is convenience and a potentially simpler first step for a small, urgent gap. A conventional loan may be better for a larger, planned expense because it normally encourages a more deliberate review of repayment. CashHoop’s strength is immediacy, not replacing every form of borrowing.
Compared with an overdraft, the better choice depends on the account terms and the timing of the charge. An overdraft may solve an immediate payment problem, but fees and account restrictions can vary. CashHoop deserves the same careful comparison. I would place the two options side by side and consider which one leaves the next pay cycle in a safer position.
The best scenario for using CashHoop
The strongest use case is a one-off, necessary bill with a known amount and a dependable near-term source of repayment. For example, if a critical service requires payment before payday and I know exactly when my income arrives, the app’s central capability matches the problem: a temporary cash-flow bridge.
In that scenario, I would follow a simple sequence. First, I would confirm that delaying the bill creates a greater problem than using an advance. Next, I would request only the amount needed. Then I would review the repayment impact against fixed expenses. Finally, I would avoid taking another advance to cover the first one. That last step is crucial because repeated advances can turn a timing solution into a continuing dependency.
The app may also suit someone handling an unexpected household cost who values a mobile-first process. I can see the appeal for a person who needs an answer outside normal branch hours or who prefers to manage financial tasks privately. The convenience is meaningful when the need is urgent and the repayment plan is already clear.
It is less convincing for a planned holiday, a nonessential upgrade, or a bill that appears every month. Those situations call for budgeting, negotiating the due date, reducing the expense, or building an emergency fund. Using an advance repeatedly for predictable costs would hide the underlying budget problem instead of solving it.
Trade-offs I would not ignore
The biggest friction is the need to make a careful decision inside a fast-moving experience. Speed is valuable, but it can also encourage people to focus on receiving money rather than the full obligation. I would read the offer and repayment information slowly, even if the rest of the process feels designed for quick completion.
I would also avoid assuming that the word “instant” means every user will receive money under identical conditions or on an identical timetable. Financial applications can involve individual eligibility and transaction circumstances. CashHoop’s appeal is the promise of a rapid route to an advance, but I would still keep a backup plan for a bill that cannot wait.
Another trade-off is that the app’s narrow purpose may leave gaps for users who want a complete picture of their finances. If I needed detailed spending categories, long-term savings goals, investment tools, or broad account management, I would look to a dedicated budgeting or banking app instead. CashHoop is easier to understand when judged as a cash-gap tool, not as an all-purpose financial home.
The developer, Biskup Apps, has kept the product’s public identity focused on this particular financial need. That clarity helps with discovery, but it also means I would not expect the same depth as a mature bank platform across every money task. The right question is not whether it does everything; it is whether its advance workflow is appropriate for the specific problem in front of me.
Security and privacy deserve a personal check before use. Because a finance app can involve sensitive information, I would install it only from the official Android store, review the permissions shown on my device, and avoid entering financial details while connected to an untrusted network. I would also protect the phone with a screen lock and remove access if I stopped using the service. These are simple steps, but they matter more here than they would with a casual utility.
Who gains the most from this focused design
CashHoop is most useful for an Android user who has a genuine short-term cash-flow gap, understands the next repayment point, and wants to begin the process from a phone. The broad device support is helpful for people using older Android hardware, while the free installation lowers the barrier to exploring the app before deciding whether it fits a particular situation.
I would also see value for someone who wants a private alternative to asking acquaintances for help. The app’s finance category and clear advance focus make it more relevant than a general budgeting tool when the immediate task is handling a bill. Its strong user response, including a 4.6 average and a large install base, gives it some social proof, but I would still make my decision from the terms presented to me personally.
On the other hand, I would tell a user with irregular income to be especially careful. If the next payment date or amount is uncertain, an advance can create pressure at exactly the wrong time. I would also steer someone toward a nonprofit debt adviser, a bank conversation, or a structured budget if they are already using borrowing to cover essentials every month.
People who dislike reading financial conditions on a small screen may prefer a conventional provider where they can ask questions directly. Likewise, anyone looking for long-term money organization should choose a tool built around budgets and savings rather than expecting this app to become a complete financial planner.
My practical verdict after weighing the convenience
I see CashHoop as a focused option for a specific problem: accessing a cash advance when an important expense arrives before available income. Its value comes from making that request mobile and direct, not from promising to repair an unhealthy budget. The free app, Everyone rating, current Android support, and substantial user adoption make it easy to consider, while the 1.0.15 release shows that the product is being delivered as a defined app experience rather than an abstract service.
My recommendation is conditional but positive. I would consider using it for a one-time emergency after checking the complete repayment details and confirming that my next income can handle them comfortably. I would not use it for discretionary spending, repeated monthly shortages, or any situation where I am unsure how the advance will be repaid.
CashHoop works best when it bridges a clearly measured gap, not when it becomes part of the regular budget. If that describes your situation, its focused design may be more useful than a broad finance app that makes you search through unrelated features. If your problem is ongoing debt or unstable income, a slower and more comprehensive solution is likely the better choice.
FAQ
What is Instant Cash Advance: CashHoop, and how does it work?
Instant Cash Advance: CashHoop is a financial app designed to help eligible users explore short-term cash advance options through a mobile application. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess your request. Available amounts, fees, repayment terms, and approval decisions can vary by applicant and are not guaranteed.
Is CashHoop a direct lender, and will everyone be approved?
CashHoop may function as a connection service that helps users submit information to potential lenders or financial providers rather than providing every advance directly. Approval is not guaranteed, and eligibility can depend on factors such as income, employment, banking history, location, and the provider’s own requirements. Before accepting an offer, carefully confirm who the lender is and review the complete agreement.
How much does a CashHoop advance cost?
The total cost of using CashHoop depends on the offer you receive and may include interest, origination charges, service fees, late-payment fees, or other costs. Some users may also be redirected to third-party providers with different pricing structures. Do not rely only on an advertised amount or representative example; read the final disclosure carefully and compare the annual percentage rate, repayment total, and due date.
What information and permissions does CashHoop require?
During registration or an application, CashHoop may request details such as your name, contact information, address, employment status, income, bank account information, and identification data. The app may also request device or communication permissions depending on its current configuration. Before submitting sensitive information, review the privacy policy, understand how data may be shared, and download the app only from a trusted official store.
When must a CashHoop advance be repaid, and what happens if I miss the payment?
Repayment timing is determined by the specific lender or provider and should be clearly stated in the offer agreement. Short-term advances can have relatively quick due dates, so check whether repayment is scheduled for your next payday or another date. Missing a payment may result in additional fees, collection activity, or negative consequences under the agreement. Contact the provider promptly if you expect difficulty repaying.


