Grant Cash Advance

- 8.79K Reviews
- 4.8
- Downloads
- 1.00M
- 2.67.1406
- Version
Screenshots
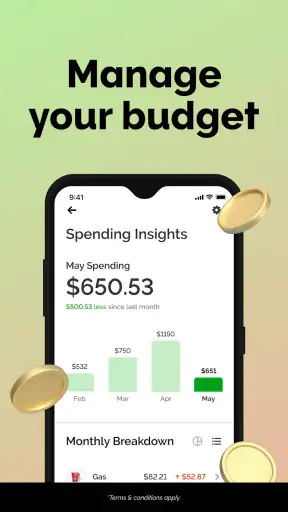
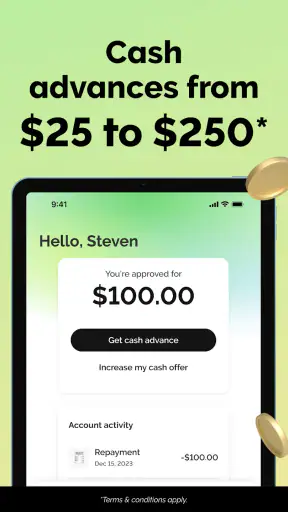
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple application process with minimal paperwork required.
- Useful for handling unexpected expenses between paychecks.
- Clear repayment terms are shown before accepting an offer.
- Funds may arrive quickly after approval
- depending on eligibility.
- Convenient access through a mobile app at any time.
Cons
- High fees or interest may make borrowing expensive.
- Approval and loan amounts depend on personal eligibility.
- Late payments can lead to additional charges or collection activity.
- Not available in every state or to all types of applicants.
- Repeated advances may encourage a cycle of borrowing.
Review of Grant Cash Advance Appxis
When money is tight in a household, a cash advance app can look like a simple way to cover a small gap before payday. I looked at Grant Cash Advance with that everyday situation in mind: not as a replacement for a bank account, but as a tool someone might consider when an unexpected expense appears and the usual balance is not enough. It is a free finance app from Kikoff Inc., built around getting cash quickly without a credit check or interest, and it is available for Everyone.
That description sounds straightforward, but borrowing from an app still deserves careful thought. The useful question is not only whether the application is easy to open. It is whether the person using it understands the repayment responsibility, keeps their account separate from everyone else in the home, and has a realistic plan for the next few days. In my experience, those practical boundaries matter more than a polished sign-up screen.
How Grant Cash Advance fits into a shared household
A realistic example is a household where one person handles rent and utilities while another pays for groceries, transport, or childcare. A sudden pharmacy purchase or a necessary trip can create a short-term gap. In that situation, Grant Cash Advance may be useful to the individual whose name and financial details are attached to the account. It is not something I would treat as a communal wallet that everyone can dip into.
That distinction is important on a shared phone. If partners, relatives, or roommates use the same device, the person who opens the app should remain the person making the financial decision. I would not hand the phone to someone else and ask them to choose an advance, review account information, or manage repayment on my behalf. Even when the household trusts one another, a cash advance is still a personal financial commitment.
The app’s free availability removes an upfront download cost, but “free” should not be interpreted as “without responsibility.” The store summary presents the service as having no credit check and no interest. That can make it more approachable than a traditional credit product, especially for someone worried about a credit inquiry. Still, I would read every screen carefully before accepting anything, paying particular attention to the amount, timing, and repayment terms shown during the process.
The strongest household rule is simple: one person, one account decision, one clearly understood repayment plan. That rule prevents a common shared-device problem: one family member assumes another person has already checked the details, while neither has a complete picture of what will happen next.
Keep the account boundary clear from the beginning
Grant Cash Advance is best approached as an individual finance tool, even when the money will help the whole household. I would set it up using the applicant’s own information and keep the login process private. A shared device does not need to become a shared financial profile. If several people use the phone, I would avoid saving sensitive details where another person could accidentally see them.
I would also choose a quiet moment for setup rather than rushing through it at a checkout counter or while dealing with an emergency. The app may be designed for speed, but speed is not a good reason to skim financial screens. Before proceeding, I would make sure I know how much cash is being requested, where it will go, and what future balance needs to be available for repayment.
One practical workflow is to write down the planned use before opening the application. “Cover the electric bill until payday” is more disciplined than “get some extra money.” A specific purpose gives the household a way to decide whether the advance is genuinely necessary. It also makes it easier to avoid using the same money for several unrelated purchases once it arrives.
I would not use another household member’s phone number, payment details, or identity information simply because they are more convenient. If the person applying cannot comfortably complete the process with their own details, that is a reason to pause rather than improvise. Financial apps are not a good place for informal account sharing.
Coordinate the repayment before using the cash
The most useful conversation in a household should happen before the advance is taken, not after the money has been spent. If the cash is intended for a shared expense, everyone affected should know who is responsible for repayment. That might be the applicant alone, or the household might agree that another person will transfer their share. Either way, the arrangement should be explicit.
I would suggest matching the advance to a single, necessary expense and recording the repayment obligation alongside ordinary bills. A note in a household budget can be enough: amount borrowed, expected repayment date, and the person responsible. This is a small step, but it avoids the vague assumption that “we will sort it out later.”
Coordination also matters when the phone is used by children or guests. I would not leave the app open on a screen that displays financial information, and I would not let someone unfamiliar with the service tap through it just to see how it works. A curious click can become a financial action if the account is already prepared.
Grant Cash Advance may be a better fit for a short, defined interruption than for a recurring household shortfall. If the same bills require advances repeatedly, the app is no longer solving an isolated timing problem. It may be time to compare a revised budget, a payment arrangement with the provider, a credit-union option, or help from a qualified financial counselor. A fast app can be convenient while still being the wrong long-term answer.
Age, trust, and who should use it
The Everyone content rating makes the app broadly accessible from an age-rating perspective, but that does not mean every person in a family should use it independently. Cash advances involve judgment about income, bills, repayment, and personal responsibility. In my view, a young person who does not manage their own income should not be encouraged to request money simply because the app is easy to find on a shared device.
Adults can still benefit from a clear household boundary. I would explain what the app is for, what it is not for, and why the account belongs to one named user. Trust is not improved by sharing passwords or leaving financial screens visible. It is improved when the household agrees on who may make decisions and how any shared expense will be recorded.
This is also where the app’s no-credit-check positioning needs context. Someone who has limited credit history may find that feature appealing, but avoiding a credit check does not remove the need to judge affordability. A person with irregular income, several existing obligations, or no money expected before repayment should be especially cautious. The absence of interest in the store summary should not be treated as a guarantee that every possible cost or condition is irrelevant; I would inspect the actual offer and terms presented in the app.
For a household that already has a stable emergency fund, using that fund may be simpler and easier to control. For someone who needs a small bridge and has a dependable plan to restore the balance, Grant Cash Advance can be worth considering. The difference is not the app alone; it is the user’s ability to repay without creating a second emergency.
What the app does well in daily use
The clearest advantage is accessibility. Grant Cash Advance is free to install, and its central proposition is easy to understand: request cash without a credit check or interest. That can make it less intimidating than a conventional loan application for someone who only needs to manage a brief cash-flow problem.
Its popularity also suggests that many people have found the product worth trying. The app has a 4.8 average from around 134 thousand ratings, with more than a million installs. Those figures do not prove that it will suit every financial situation, but they do indicate that it is not an obscure experiment with no established user base.
I also appreciate that the app has a focused purpose rather than trying to be a full banking replacement. If I were opening it, I would want to complete one clear task, review the consequences, and leave. That narrow use can be helpful for someone who does not want to open a new checking account or apply for a conventional credit card just to handle a temporary timing issue.
Another practical strength is that a cash advance can be easier to discuss in a household than a larger borrowing product. The smaller, defined purpose may encourage a more precise conversation about what happened and how the shortfall will be covered. That benefit depends on honest communication, but the app’s straightforward role can support it.
Where the usual alternatives may be better
Compared with overdraft protection, Grant Cash Advance may feel more deliberate because the user chooses to open a separate app and consider the request. An overdraft, by contrast, can happen automatically when a payment clears. However, someone whose bank already offers a clearly understood, low-cost short-term buffer may prefer staying inside the existing account rather than adding another service.
Compared with a credit card, the app’s no-credit-check approach may appeal to people who want to avoid a credit application. A credit card can be more useful for repeated purchases or established credit-building goals, but it also creates a longer-running balance if the user does not pay it down. I would not choose Grant Cash Advance as a substitute for building credit, and I would not choose a credit card merely because cash-flow problems are happening every month.
Compared with borrowing from family, the app can avoid an awkward personal conversation. That convenience has a trade-off: a family loan may offer more flexibility if repayment is delayed, while an app-based obligation may follow its own schedule. Compared with a payday loan, the store summary’s no-interest positioning is attractive, but I would still compare the complete terms rather than assuming every short-term product works the same way.
The best alternative may sometimes be negotiating the bill itself. A utility provider, medical office, landlord, or service company may offer a payment arrangement that addresses the actual problem without adding a separate cash obligation. Grant Cash Advance is most convincing when the expense is urgent, the amount is manageable, and the user knows exactly how the next income will cover it.
Small habits that make the experience safer
My first tip is to separate the decision from the spending. Decide the exact purpose and amount before requesting anything. If the requested cash grows because several nonessential purchases are added, stop and reassess. Convenience can quietly turn a narrow bridge into a larger commitment.
My second tip is to check the account after the household expense is paid. Keep a simple record of what the advance covered and what remains available for ordinary bills. This is particularly useful when several people contribute to rent, groceries, or transport. Without a note, shared money tends to become invisible, and the repayment can surprise the person whose account is connected.
My third tip is to avoid using a shared device as a shared control panel. Sign out when finished, keep notifications private where possible, and never assume that a spouse, roommate, or older child knows what a button means. These are not special Grant Cash Advance features; they are sensible boundaries for using a personal finance app around other people.
My fourth tip is to treat repeated use as a warning signal. One unexpected repair is different from needing an advance for ordinary groceries every pay cycle. If the pattern repeats, I would stop looking for faster access to cash and start examining the household’s income timing, fixed bills, subscriptions, and emergency savings. The app may help with the immediate moment, but it cannot correct a budget that is permanently short.
Performance, compatibility, and the overall experience
The current Android version is 2.67.1406, and the app supports Android 7.0 or later. That makes it usable on many older Android phones, which is helpful in a household where the newest device belongs to someone else. I would still keep the operating system updated and use the device’s normal security protections, especially because finance apps handle information that should not be casually exposed.
Grant Cash Advance was released on December 15, 2023, and Kikoff Inc. continues to identify it as a finance product rather than a general-purpose wallet. That context helps set expectations: I would open it for a cash-advance decision, not for detailed household budgeting, shared bill management, or long-term financial planning.
The main friction is not necessarily technical. It is the mental effort required to slow down when the app is designed around urgency. A quick request can be useful, but it can also encourage a “solve today, think tomorrow” habit. I would regard the review of the offer and repayment details as part of the product experience, not as paperwork to skip.
For someone who wants a full account, direct deposit tools, spending categories, or coordinated household access, a traditional banking app may be a better center of gravity. For someone who needs a narrowly focused short-term option and understands the responsibility attached to it, this app has a clearer purpose.
My household verdict
After looking at Grant Cash Advance through the lens of shared-device use, I see it as a potentially useful personal tool rather than a family finance system. I would recommend it to an adult who has a specific short-term need, can identify the repayment source, and is comfortable keeping the account private. The free price and no-credit-check positioning make it approachable, while the app’s focused design may be less burdensome than applying for a conventional credit product.
I would skip it if the household is already relying on advances for routine expenses, if the repayment plan is uncertain, or if several people would be using one account interchangeably. In those cases, a budget review, creditor arrangement, emergency fund, or more structured banking solution is likely to address the underlying issue better.
The app’s high user rating and broad install base make it easy to take seriously, but popularity should not replace personal judgment. My recommendation is to use it only for a defined purpose, discuss any shared expense before requesting cash, and keep the account firmly tied to the responsible adult. Used with those boundaries, Grant Cash Advance can be a practical bridge for an occasional gap. Used casually on a shared phone, it can make a private financial obligation look like a household convenience, and that is where I would be most cautious.
FAQ
What is Grant Cash Advance, and how does it work?
Grant Cash Advance is a financial service app designed to help eligible users explore short-term cash advance options through a mobile application. After creating an account, you may be asked to provide personal, employment, banking, and income information so the service can assess eligibility. Approval is not guaranteed, and available amounts, repayment terms, fees, and conditions can vary by applicant and location.
Is Grant Cash Advance a legitimate loan provider or a loan-matching service?
Before submitting an application, users should carefully determine whether Grant Cash Advance provides funds directly or connects applicants with third-party lenders. The app may present offers from external providers rather than approve every request itself. Read the lender’s name, agreement, annual percentage rate, fees, repayment schedule, and privacy terms before accepting anything. Avoid assuming that a displayed offer represents guaranteed approval or instant funding.
What information does Grant Cash Advance require during registration?
Grant Cash Advance may request details such as your full name, address, date of birth, phone number, email address, employment information, income, and bank account details. This information can be used for identity verification, eligibility checks, and processing a potential advance. Only enter accurate information through the official app or website, review its privacy policy, and avoid sharing login credentials or verification codes with anyone.
How much does Grant Cash Advance cost, and when must the money be repaid?
The total cost and repayment date depend on the offer you receive, your location, the provider involved, and your financial profile. Possible charges may include service fees, interest, origination costs, or late-payment fees. Carefully review the complete agreement before accepting funds, including the annual percentage rate and automatic-debit terms. Borrow only what you can repay on time, since missed payments may create additional costs.
Is Grant Cash Advance safe to use, and what should I check before downloading it?
Use caution with any app requesting sensitive financial information. Download Grant Cash Advance only from a verified Google Play or Apple App Store listing, confirm the developer name, inspect permissions, and read recent user reviews. Never pay an upfront fee simply to receive a promised loan, and be cautious of guaranteed-approval claims. Check customer-support details, privacy practices, lender disclosures, and local regulations before applying.


