Get Paid Early: Cash Advance

- 166.00 Reviews
- 4.2
- Downloads
- 50.00K
- 3.0.39
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast access to earned wages before payday
- Simple application process with minimal eligibility requirements
- No traditional credit check for cash advances
- Repayment is automatically scheduled for convenience
- Useful for covering unexpected short-term expenses
Cons
- Advance limits may be low for new or infrequent users
- Optional express fees can make borrowing more expensive
- Requires consistent income and verified employment details
- Automatic repayment may strain your next paycheck
- Availability and terms can vary by employer or location
Review of Get Paid Early: Cash Advance Appxis
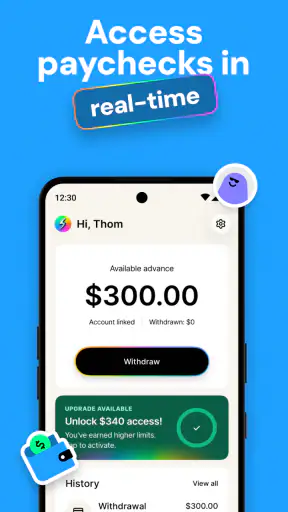
Getting access to earned pay before the usual payday sounds simple, but the real test is what happens when setup does not go smoothly. I spent time looking at Get Paid Early: Cash Advance as a finance app from StreamFunds, Inc., focusing less on its short promise and more on the moments that can make an early-pay request confusing. My overall impression is that it can be useful for a narrow, practical need: managing a short gap between work already completed and money arriving through the normal payroll cycle.
The app is free and aimed at everyone, which makes it approachable for people who do not want to start with a complicated financial product. Its central appeal is also clear: it presents early access to earned pay as an alternative to borrowing. That distinction matters, but it does not remove the need to check your employment, payroll, identity, and bank details carefully. In my experience, most frustration with services in this category begins before the actual request, when one small mismatch prevents the app from recognizing the user or the available earnings.
What using the app is really like when something goes wrong
The first sticking points are usually practical
The hardest part of an earned-pay app is often not finding the main action. It is getting the app to connect your situation with the information it needs. A name written differently from the one used by payroll, an old phone number, an incorrect bank detail, or employment information that has not updated can all create a confusing experience. The screen may appear to be asking for a simple correction, while the underlying problem is that two records do not match.
I would approach the first session slowly rather than treating it like a quick download-and-cash-out tool. Keep your payroll information, current contact details, and receiving-account information close at hand. Enter everything consistently, especially your legal name and address. Small formatting differences are not always important, but changing details repeatedly can make it harder to understand which part of the setup is actually blocking progress.
Another common point of confusion is the difference between earned wages and money that is already available to move. Seeing that work has been performed does not necessarily mean the amount can be accessed immediately. Payroll timing, employer records, account verification, and the app’s own eligibility checks can affect what appears. I would not plan a bill payment around an amount until the app clearly shows that the request has been accepted and the transfer process is underway.
This is also where expectations need to be realistic. The service is not a replacement for a regular paycheck, a savings cushion, or a long-term budgeting system. It is designed around timing. If the problem is that monthly income is consistently too low, receiving part of earned pay earlier may provide temporary relief without solving the larger issue. That is an important distinction before making the app part of a recurring financial routine.
Setup checks that save time later
My preferred setup method is to treat the account like a financial record rather than a casual social app. First, I would verify that the personal information matches the information used by the employer or payroll provider. Next, I would inspect the destination account details character by character. Finally, I would check whether the current job and pay cycle are represented correctly before attempting to request anything.
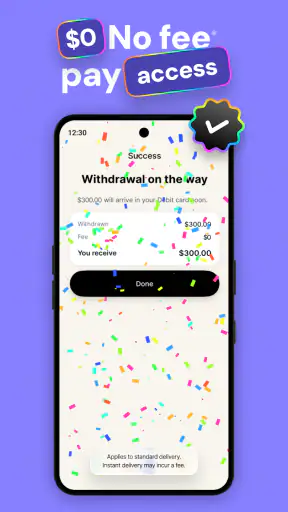
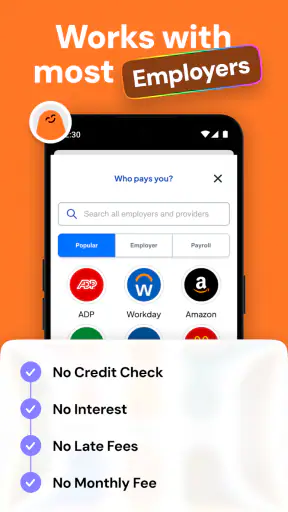
Do not rush through a screen simply because the app is free. Free access does not mean the user can skip reading the wording around eligibility, timing, or repayment through payroll. The store summary emphasizes no loans, no interest, and no hidden fees, but I would still read every confirmation page. The important question is not only how much can be accessed; it is how receiving pay early changes what remains for the normal payday.
A useful personal check is to write down the next expected paycheck and the expenses that must come from it. If an early transfer covers a small emergency today, the later paycheck may be smaller than usual. That is not necessarily a flaw in the app; it is the natural consequence of receiving part of earned income ahead of schedule. Thinking through that trade-off before tapping confirm helps prevent a short-term solution from creating another shortfall.
I would also keep notifications and account messages easy to find. If a request needs attention, a user who ignores an email or in-app message may assume the transfer failed when it is actually waiting for a correction. The safest workflow is to read the exact status, note what action is requested, and make one deliberate change at a time. Repeatedly submitting the same request is rarely a good troubleshooting strategy for a finance service.
Recovering from a stalled or unclear request
When a request does not move forward, start with the status rather than immediately uninstalling the app. A pending state, an eligibility message, and a failed transfer point to different problems. A pending message suggests that the process is still being checked. An eligibility message suggests that the app does not currently recognize the required conditions. A failed transfer makes the receiving account or transfer path more important to review.
My first recovery step would be to close and reopen the app, then check whether the same status remains. If the issue looks like a connection problem, switch between a reliable Wi-Fi connection and mobile data, provided the device has service. I would avoid using public networks for sensitive financial activity. If the app has just been updated, I would also make sure the device is running a supported operating system and that the current version is installed rather than an outdated build.
The current version is 3.0.39, and the app supports Android 7.0 or later. Those details are useful when diagnosing a technical problem: an older phone may meet the minimum system requirement but still behave less reliably than a newer device, especially if storage is nearly full or background activity is restricted. Before blaming the service, I would restart the phone, free a little storage, and check that the app can display its screens normally.
If the issue involves a bank account, I would not keep adding alternative accounts at random. First confirm that the original details are correct and that the receiving account is active. A typo, a closed account, or a mismatch in account ownership can turn a straightforward request into a failed transfer. Correcting the source of the problem is safer than creating several new possibilities that are harder to track.
There is also a useful distinction between an app problem and a payroll-data delay. If recently worked hours have not appeared, the app may simply be waiting for the employer’s records to update. In that situation, reinstalling the app will not create new earnings information. I would compare the timing with the employer’s normal payroll process and wait for the record to refresh before trying the request again.
When the app is not the cause
Finance apps are often blamed for events outside their control. A delayed payroll update, a bank maintenance window, a changed employment record, or a phone that blocks notifications can all look like an app failure. Before contacting support, I would gather the exact message shown, the time the problem appeared, and whether the issue affects login, earnings visibility, or transfer delivery. That makes the conversation more useful and avoids vague explanations such as “it does not work.”
It is especially important not to share passwords, full security codes, or unnecessary account credentials while asking for help. A legitimate troubleshooting conversation should focus on the error and the relevant account details, not on handing over control of the account. I would use only the support route presented inside the official app experience and avoid third-party messages promising to unlock a transfer.
Users should also consider whether the financial problem is actually a timing problem. If an unexpected expense is larger than the available earned pay, the app may not be the right answer. A bank overdraft arrangement, a formal credit product, a payment plan with the biller, or help from a trusted person may be more appropriate depending on the situation. Those alternatives have their own costs and risks, but comparing them honestly is better than forcing an early-pay tool to solve a problem outside its purpose.
On the other hand, if the need is small and temporary, getting part of already earned income may feel more sensible than taking a conventional loan. The difference is meaningful: the user is managing the timing of wages rather than borrowing against future income through a separate debt product. Even so, I would treat every request as a decision with a later-paycheck consequence, not as free extra money.
Everyday situations where it can help
Imagine a worker has completed a normal week but faces an urgent transport expense before payday. If the app recognizes the employment and earnings information, early access could help bridge that specific gap. The practical advantage is not that the user suddenly has more income; it is that money already earned becomes available at a more useful time. For someone who can comfortably manage the reduced later paycheck, that may be a reasonable use.
A second scenario is a recurring bill that falls just before payday. Here, I would be more cautious. Using early pay once to avoid a late payment may be sensible, but using it every pay cycle can hide a mismatch between the bill schedule and the household budget. A better long-term move might be changing the bill’s due date, building a small buffer, or adjusting spending. The app can assist with timing, but it should not become invisible support for an unsustainable pattern.
A less obvious use is as a planning tool for irregular cash flow. Someone whose work hours vary may use the app to understand when earned pay becomes available, then compare that timing with upcoming expenses. The insight is valuable only if the user records what was accessed and what remains. I would keep a simple note after each transfer so the next payday does not come as a surprise.
There is a trade-off for users who prefer complete predictability. Conventional payroll deposits are easier to understand because the full cycle arrives at its scheduled time. An earned-pay service introduces another decision: whether to move money now or wait. If that extra choice causes repeated confusion, the usual payroll arrangement may actually be better for you.
How it compares with familiar alternatives
Compared with a traditional payday loan, the app’s appeal is obvious. The store positioning focuses on accessing earned pay without loans, interest, or hidden fees, so the concept is different from taking on a separate high-cost debt. That can make it more attractive for a short timing issue. Still, users should not compare only the headline cost; they should compare how each option affects the next paycheck, future obligations, and their ability to cover essentials.
Compared with an overdraft, early access may feel more deliberate because the user is moving earned income rather than allowing a transaction to push an account below zero. But an overdraft facility may be more familiar or more widely accepted for certain urgent payments. The better choice depends on the exact timing, the account terms, and whether the user can restore the balance quickly.
Compared with a budgeting app, this service addresses cash availability rather than spending visibility. A budgeting tool can help identify why money runs short, while Get Paid Early: Cash Advance can potentially change when part of the income arrives. I would use the two ideas differently: budgeting for prevention, early pay for an occasional timing gap. Choosing this app alone will not show whether subscriptions, groceries, transport, or debt payments are consuming too much of the monthly income.
Compared with simply asking an employer about payroll timing, the app may offer a more direct user experience when the employment connection works properly. However, an employer’s payroll department can explain missing hours or a delayed pay record in a way an app cannot. If the issue is incorrect wages rather than access timing, the employer remains the right place to start.
Who should use it and who should skip it
I think the app is best suited to someone with predictable employment income who occasionally needs to bring forward a portion of money already earned. That person should be comfortable checking account details, reading confirmation screens, and budgeting for a smaller later paycheck. The free price and Everyone age rating make the initial barrier low, but financial responsibility still depends on the user’s situation rather than the download cost.
I would hesitate to recommend it to someone whose income is highly uncertain, whose employment information changes frequently, or who is already using early access every pay period to cover basic necessities. In those cases, the service may provide relief without improving stability. It may also be a poor fit for anyone who expects an instant transfer every time or who dislikes troubleshooting account and payroll mismatches.
The app has attracted a meaningful user base, with over 50 thousand installs and a 4.2 average from 713 ratings. Those figures suggest that the concept is useful to many people, while the number of ratings also reminds me not to treat the average as a guarantee that every payroll arrangement will work identically. StreamFunds, Inc. has built a focused finance product rather than a broad money-management suite, and that narrow focus is both its strength and its limit.
Before installing, I would ask myself three questions. Is the problem genuinely temporary? Can I manage the later paycheck after accessing money early? And am I willing to verify payroll and bank information carefully if the first attempt stalls? If the answer to all three is yes, the app is worth considering. If the answer to the second is no, waiting for regular pay or seeking a more sustainable solution is safer.
My practical verdict
My view is positive but measured. Get Paid Early: Cash Advance makes sense as a focused tool for a short cash-flow gap, especially for users who want an alternative to a conventional loan. Its strongest quality is the clarity of that purpose: it is about timing earned income, not pretending to replace budgeting or increase total earnings.
The main friction is that a smooth result depends on several connected pieces: accurate personal information, recognizable payroll records, a suitable receiving account, a supported device, and realistic expectations about when earnings become available. When something fails, the best response is methodical checking rather than repeated submissions or assuming the app is responsible for a payroll delay.
I would recommend trying it for a specific, manageable need and keeping track of what happens to the next paycheck. I would not build an entire budget around early access until the workflow has proven reliable in your own circumstances. For occasional use, it can be a practical bridge. For persistent financial shortages, another solution is likely more valuable.
That balance is why I see this free finance app as useful for the right person, but not universally necessary. If you understand the timing trade-off and are prepared to resolve setup details carefully, it may make an awkward week easier. If you need long-term financial breathing room, the honest answer is to look beyond early pay and address the underlying budget, income, or bill-scheduling problem.
FAQ
What is Get Paid Early: Cash Advance?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected paycheck before their regular payday. After creating an account and completing the required verification, users may be able to request an advance through the app. Availability, limits, repayment timing, and eligibility can vary depending on your employer, income information, location, and account history.
How does the cash advance process work?
The app generally requires you to sign up, verify your identity and income details, and connect an eligible bank account or payroll information. If approved, you can select an available advance amount and review the delivery and repayment terms before confirming. Funds may arrive quickly, but timing depends on the transfer method, banking institution, weekends, holidays, and the information provided during registration.
Are there fees or interest charges for using the app?
Before requesting money, carefully review the complete cost shown in the app. Cash advance services may use subscription charges, optional expedited-transfer fees, required fees, or other costs rather than traditional interest, depending on the product and your location. Terms can change, so do not assume an advance is free. Confirm the total repayment amount, renewal conditions, and cancellation policy.
Who can use Get Paid Early: Cash Advance?
Eligibility is not guaranteed for every applicant. You may need to meet minimum age and residency requirements, have a regular source of income, maintain an eligible bank account, and successfully complete identity and risk checks. The app may also consider payroll information, account activity, repayment history, and other criteria. Meeting the basic requirements does not necessarily guarantee approval or a specific advance limit.
When and how is the advance repaid?
Repayment is normally scheduled for a future date connected to your expected paycheck or the terms displayed when you request the advance. The app may withdraw the amount from your linked bank account, so you should keep enough money available on the due date. Review the repayment schedule carefully, because missed payments, insufficient funds, bank restrictions, or extensions may lead to additional charges or account limitations.


