

Four | Buy Now, Pay Later
Four Technologies, IncFinance
Scanned and Safe · Free
- Rating
- 4.4Out of 5
- Downloads
- 1.00M
- Android
- 6.0
Screenshots
Analysis by Appxis
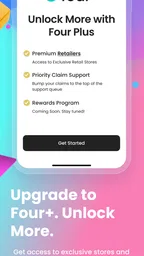
Ever found yourself eyeing that sleek gadget or trendy outfit but held back because payday is still a week away? Say hello to Four | Buy Now, Pay Later, the app that’s making these little dreams possible without burning a hole in your pocket. It’s a nifty tool that lets you snag what you want now and pay for it over time, interest-free!
A sensible way to approach the first purchase
I’d treat Four as a way to organize the timing of a purchase, not as extra money in my budget. That distinction matters: splitting a bill can make a planned expense easier to manage, but it does not make the total cost disappear. Before choosing a payment option, I’d check that the full purchase fits what I can afford and that the scheduled payments won’t collide with rent, groceries, or other essentials.
For example, if a household item needs replacing just before payday, paying in installments may help smooth out the immediate cash-flow pinch. For an optional purchase, though, I’d ask whether I would still buy it if the full amount came out of my account today. If the answer is no, waiting is usually the safer choice. That simple pause is more useful than treating a payment split as permission to add something to the cart.
How It Works
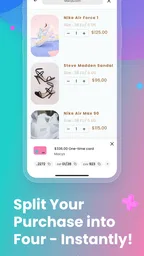
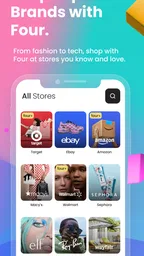
So, here’s the scoop. With Four, you get to split your purchases into four easy installments. You’re not just limited to a handful of stores; this app works with a wide array of retailers, both big and small. Shopping online or in-store? Doesn’t matter, Four has got you covered. It’s super seamless, just like swiping through your favorite social media feed.
Signing Up and Getting Started
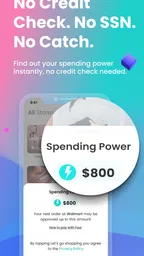
Getting started is a breeze. I honestly found the sign-up process as easy as pie. You just need to download the app, and after a quick setup involving basic information, you’re ready to start shopping. No lengthy paperwork or credit checks to worry about, which is a huge relief for many of us.
One practical habit I’d establish from the start is to keep the purchase details easy to find and review the payment schedule before committing. A quick check helps turn a convenient checkout into a deliberate decision: note the total, the installment dates, and which account will be used for payments. If the dates fall during a tight part of the month, I’d wait or choose a different way to pay rather than assume I’ll remember later.
Four is a finance app from Four Technologies, Inc. It is free to download, has an Everyone age rating, and its current version is 1.17.25; it runs on Android 6.0 and later. Those basics make it accessible to many Android users, though availability on a particular device and the checkout options shown can still depend on the retailer and situation. The app has a 4.5 average from around 9,900 ratings, with about 4,200 written reviews and over 500,000 installs. That suggests it has attracted a substantial audience, but I’d still judge whether its payment flow suits my own habits rather than treating popularity as a guarantee.
More Stories While You Read






Shopping Experience
Once you’re in, using the app feels like second nature. The interface is clean and user-friendly. You can discover new shops or stick to your usual favorites. The app sends you reminders about upcoming payments, so you won’t have to worry about missing a payment date. And the best part? Payments are automatically deducted from your account, making the whole process hands-off.
That hands-off element is also where a little routine helps. I’d check upcoming payments alongside my regular account review, rather than relying only on reminders. If I make several purchases close together, writing down each total and date in one place makes the combined commitment easier to see. The key is to look at all active obligations together: a payment that seems small on its own can feel different when it lands in the same week as other bills.
For a realistic everyday example, imagine ordering a replacement appliance part and a work shirt during the same month. I’d decide which purchase is genuinely time-sensitive, check the payment schedule for each before confirming, then make sure their dates do not overlap with a major bill. If only one fits comfortably, I’d use the split payment for that one and pay for the other later. This keeps the app serving a specific budgeting need instead of turning several separate checkouts into an unclear running balance.
Building a repeatable checkout routine
Experienced users get more value from a consistent process than from tapping through quickly. I’d keep a short pre-purchase checklist: confirm the retailer and total, inspect the installment schedule, make sure the payment method is current, and decide where I’ll track the dates. After placing an order, I’d check that the purchase appears as expected and retain the retailer’s order confirmation. That last step is useful because the retailer handles the goods and order itself, while Four is being used for the payment arrangement.
If an order is changed, delayed, or returned, I wouldn’t assume the payment plan updates in exactly the way I expect. I’d review the order and payment information in the relevant apps and contact the appropriate support channel if anything looks inconsistent. This is a general good practice for any split-payment service: a return or cancellation involves the retailer as well as the financing or payment provider, so keeping both records makes it easier to follow what happened.
Another useful boundary is to avoid opening the app simply to browse when I’m trying not to spend. A discovery-focused shopping experience can make tempting products more visible, while a planned list keeps the purpose clear. I’d use Four when I already know what I need and have checked the budget, not as a substitute for deciding whether I want the purchase at all.
Why It’s Worth a Try
Here’s the thing I love the most: the flexibility. Being able to spread out payments without any interest is a game-changer. It’s like having your cake and eating it too. For anyone who’s ever felt the pinch between paychecks, this app is a lifesaver.
I’d qualify that enthusiasm with a straightforward rule: the split should make a manageable purchase easier to schedule, not encourage a bigger one. The best fit is someone who already keeps track of bills, has enough income to cover the installments, and wants a clearer way to spread a planned checkout over time. Someone who is juggling overdue bills, has an unpredictable budget, or tends to forget automatic deductions may be better served by waiting, using a debit card, or saving up first.
Compared with paying the whole amount immediately, Four can reduce the immediate outlay, but paying in full is simpler and avoids adding future dates to a budget. Compared with a credit card, a pay-later app can make a particular purchase’s installment structure more visible, while a card may be more familiar for ongoing spending and account management. Neither option is automatically better: I’d compare the exact terms shown at checkout and choose the method I can monitor and repay comfortably. For a purchase that needs a longer repayment period or a formal financing arrangement, I’d look at alternatives designed for that purpose rather than assume a short installment plan is suitable.
It is also worth separating the app experience from the retailer experience. Four can help arrange payment, but I’d still evaluate the shop itself, its delivery expectations, return process, and customer service. A smooth payment screen cannot make an unreliable seller reliable. When shopping with a retailer I have not used before, I’d check its policies before placing the order and avoid treating a convenient checkout as a reason to skip that basic research.
Limits worth keeping in view
Flexible payments can make spending feel lighter than it is. That is the central trade-off, and it is easy to miss when every purchase is considered separately. I’d set a personal ceiling for installment purchases and review all outstanding dates before adding another one. If a new plan would leave too little room for ordinary expenses, that is a sign to postpone the purchase, even if the checkout offers a way to divide the cost.
Automatic deductions reduce the need to make each payment manually, but they do not remove the need to keep enough money available. Reminders are helpful prompts, not a replacement for checking balances and dates. I’d also review the payment method and account details periodically, especially after changing banks or replacing a card. These small checks are more dependable than assuming that a previous setup will always remain suitable.
Four is not the right choice for everyone. If you prefer to keep every purchase settled immediately, do not want recurring deductions, or find that installment plans make it harder to track your spending, paying upfront is likely cleaner. If you need to compare several financing options in detail, a dedicated budgeting tool or a more conventional credit product may provide a better fit. I’d choose the option that makes the total commitment easiest to understand, not simply the one that makes checkout fastest.
And let’s not forget the security aspect. In an age where online safety is paramount, Four ensures your data is protected with top-notch security measures. You can shop with peace of mind knowing your information is safe.
Conclusion
All in all, Four | Buy Now, Pay Later is a fantastic app for anyone looking to manage their finances more flexibly. It’s not just about buying things you love; it’s about doing it smartly and safely. It’s a great companion for the savvy shopper who wants to enjoy life without the financial stress.
My recommendation is to make Four part of a deliberate checkout routine: decide what you need, confirm the full amount and payment dates, and check how those dates fit alongside existing bills. Used that way, the app can be a convenient option for a planned purchase. Used to make unplanned spending feel painless, it can do the opposite of helping your finances. The difference comes down to the habit you bring to it.
If you haven’t tried it yet, I say go for it. Download the app, give it a whirl, and thank me later. Happy shopping!
Pros
- Flexible installment plans available.
- No interest on timely payments.
- Easy to use and navigate interface.
- Quick approval process.
- Supports multiple retailers.
Cons
- High late payment fees.
- Limited to participating stores.
- Not available in all regions.
- Requires credit check.
- May encourage overspending.
Four | Buy Now, Pay Later FAQ
What is Four and how does it work?
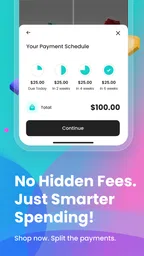
Four is a 'Buy Now, Pay Later' app that allows users to purchase items immediately and pay for them over time in four equal installments. Users can shop at participating retailers, both online and in-store, and split their purchase into four interest-free payments. The first payment is usually made at checkout, while the remaining three payments are automatically deducted from your linked payment method every two weeks.
Is there any interest or hidden fees when using Four?
Four prides itself on offering interest-free payments with no hidden fees, as long as users make their payments on time. However, if you miss a payment, there may be late fees applied. It's important to check the terms and conditions of each purchase to understand any potential fees that might apply if payments are delayed.
How do I sign up for Four and is it available in my country?
Signing up for Four is straightforward. You can download the app from the Google Play Store or Apple App Store and sign up with your email address or phone number. Four is continually expanding its reach, so it's best to check the app's availability in your country on their official website or app store page. Currently, it is available in several countries including the US and Canada.
What are the eligibility requirements to use Four?
To use Four, you typically need to be at least 18 years old and have a valid credit or debit card to link to your account. Additionally, Four may require a soft credit check to assess your eligibility, but this won't affect your credit score. It's designed to be accessible, but approval for transactions may vary based on your financial standing.
Can I return items purchased through Four?
Yes, you can return items purchased through Four, but it's important to follow the retailer's return policy. Once the return is processed and confirmed by the retailer, any payments made through Four will be refunded to your linked payment method. If a payment is due while you're waiting for a refund, you may still need to make that payment to avoid late fees, which will be reimbursed once the return is processed.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Four Technologies, Inc
- Package Name
- com.paywithfour
- Version
- 1.17.84
- Android
- 6.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@paywithfour.com, visit https://paywithfour.com/, or view the https://paywithfour.com/legal/privacy-policy.