FaithFi: Faith & Finance

- 85.00 Reviews
- 3.6
- Downloads
- 10.00K
- 5.1.3
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
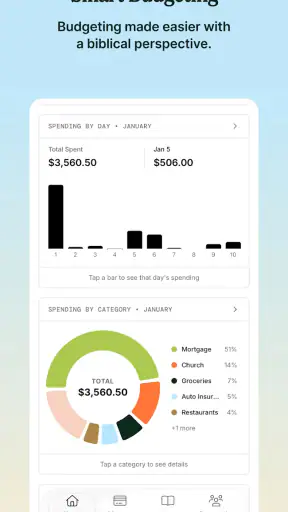
- Combines biblical principles with practical budgeting tools.
- Offers guided plans for saving
- giving
- and managing debt.
- Simple interface makes financial tracking approachable for beginners.
- Encourages intentional spending and regular financial reflection.
- Useful for users seeking faith-based accountability around money.
Cons
- Some features may require a paid subscription or in-app purchase.
- Faith-centered advice may not suit users wanting secular financial guidance.
- Limited investment analysis compared with dedicated finance platforms.
- Requires consistent manual input for accurate spending and budget tracking.
- Financial guidance should complement
- not replace
- professional advice.
Review of FaithFi: Faith & Finance Appxis
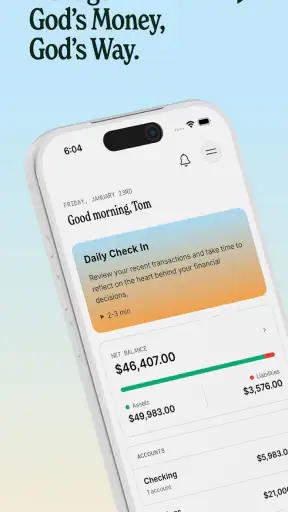
Money apps ask for a different kind of attention than ordinary entertainment or utility apps. I can forgive a rough menu in a casual game, but I want to understand what I am doing before entering financial information or changing a spending habit. FaithFi: Faith & Finance approaches that subject through a Christian faith perspective, with the stated aim of connecting belief and everyday money decisions. After spending time with it, I see a focused finance app for people who want reflection and practical money guidance in the same place, rather than a purely mechanical budget tracker.
The app is developed by FaithFi: Faith & Finance and is available free of charge, although it includes optional purchases priced from $3.99 to $11.99 per item. It is rated for Everyone, which fits its general educational and personal-finance positioning. The Android release has been available since August 31, 2020, and the current version is 5.1.3, supporting devices running Android 7.0 or later. Its audience is still relatively modest, with over ten thousand installs, and the average score sits at 3.6 from around 160 ratings and 85 written reviews. Those figures do not make it look like a universal replacement for established banking tools, but they do provide useful context: I would approach it as a specific faith-based companion, not as a complete financial institution in app form.
Where faith enters everyday money decisions
The most important thing to understand is that this is not simply another app that puts numbers into categories. Its identity is built around the meeting point between spiritual values and financial behavior. That changes the questions I bring to it. Instead of asking only whether I spent too much on dining out, I am encouraged to consider whether my priorities, generosity, saving habits, and treatment of money match the values I claim to hold.
That approach can be genuinely useful when a conventional finance app feels emotionally empty. Most budgeting tools are good at showing totals, trends, and account activity, but they usually leave the personal meaning of those numbers entirely to the user. FaithFi gives that meaning a clearer direction. For a Christian user who wants financial decisions to support a broader sense of stewardship, the app can make money management feel less like an isolated spreadsheet exercise.
I would not recommend it simply because someone wants the most advanced tracking system available. Its appeal depends on whether the faith-centered framing feels relevant rather than intrusive. If you are looking for investment research, detailed tax planning, business accounting, or a neutral household ledger, a conventional finance app will probably be a better fit. FaithFi is more interesting when the problem is not only “Where did my money go?” but also “What do I want my money to represent?”
A useful companion for intentional budgeting
One realistic way to use the app is during a weekly household check-in. I might open it after reviewing upcoming bills, look at the choices I made during the previous week, and then set one practical intention for the next one. That intention could involve slowing down impulse purchases, making room for generosity, or separating a genuine need from a habit that has simply become automatic. The value is in connecting a financial action to a reason I can remember.
This workflow is more effective than opening any finance app once a month and feeling guilty about a large total. Short, regular sessions give the reflective side of the app a chance to influence decisions before the next purchase happens. I also find that writing down the reason behind a goal can make it easier to keep when circumstances become inconvenient. A number alone may be easy to ignore; a number connected to a personal commitment has more weight.
There is a trade-off, though. A values-based approach can feel slower than opening a bank app and scanning a transaction list. If I only need to confirm whether a payment cleared, my bank’s own application is more direct. FaithFi earns its place when I am willing to pause and interpret my financial behavior, not when I need a quick account balance.
What the rating and size of the community suggest
The current 3.6 average rating tells me to keep expectations measured. It is not a reason to dismiss the app, especially because ratings can reflect different expectations, devices, and personal preferences. Still, it suggests that the experience may not satisfy everyone equally. The install count also indicates a smaller user community than the major budgeting and banking products people commonly encounter.
For me, that means I would test the app gently rather than moving my entire financial routine into it immediately. I would first see whether its content and workflow fit my beliefs, whether the controls feel understandable, and whether it actually changes how I make decisions. A smaller audience can suit a focused product, but it also means I would not assume that every edge case has been addressed as thoroughly as it is in a long-established mainstream finance platform.
The developer name, FaithFi: Faith & Finance, clearly communicates the intended audience. That clarity is helpful: I do not have to guess why the app discusses money through a faith lens. At the same time, users should distinguish a clear mission from a guarantee about financial results. No app can replace careful judgment, and a spiritual perspective does not remove the need to verify transactions, protect account details, and make decisions based on personal circumstances.
Trust begins with visible choices
When I assess a finance app, I pay attention to what I can see and control rather than filling gaps with assumptions. FaithFi’s free entry point makes it easy to explore without committing money at the start, while the optional in-app purchases create a boundary that I would want to understand before buying anything. I would check the purchase screen carefully, confirm what an item provides, and avoid treating an optional upgrade as necessary for basic financial responsibility.
The app’s Everyone content rating is reassuring in terms of its intended general audience, but an age label is not the same thing as a privacy or security assessment. I would still use a strong device passcode, keep Android updated, and avoid entering sensitive information while connected to an untrusted network. Those are ordinary precautions, yet they matter more when an app concerns money.
I also want clear account controls in any finance product: an obvious way to sign out, understandable settings, and a simple route for reviewing or removing information where the app provides such options. I would inspect those screens before making FaithFi part of a shared household routine. If a setting is difficult to find or an action feels irreversible, I would slow down and look for an explanation rather than tapping through quickly.
That is the honest limit of what I can judge from the experience itself: a calm design or faith-focused wording should not be mistaken for proof of a particular data practice. I do not infer security promises from the app’s purpose. Instead, I look for visible permission requests, readable explanations, and choices that are presented before a sensitive action. If the app asks for access that does not seem necessary for the task I am trying to complete, I would decline it and see whether the core experience remains usable.
Handling sensitive financial moments carefully
The most sensitive moment is not necessarily the first launch. It is the point at which I am tempted to enter information quickly because I want the app to become useful immediately. That is where I would stop and identify exactly what I am adding: a personal goal, a note, a financial figure, or information connected to an account. I would not assume that every field deserves the same level of trust simply because it appears inside a finance app.
My preferred setup would begin with the least sensitive information needed to evaluate the experience. I could start with broad goals and general spending reflections, then decide whether deeper use is worthwhile. This staged approach is one of the most practical ways to preserve control. It lets me judge whether the app’s faith-based guidance helps before I make it part of my financial record-keeping.
I would also separate reflection from verification. If FaithFi encourages me to think about generosity or spending priorities, that is useful guidance, but I would verify balances and payment status through my bank or card provider. The two tools serve different purposes. A bank app is the authoritative place for account activity; a values-oriented finance app can help me decide how I want to respond to that activity.
Another overlooked issue is shared access. Couples or families may want to discuss money together, but that does not mean every person should automatically use the same login or device profile. Before sharing the app, I would check what account controls exist and decide whether each person understands what information may be visible. A family conversation about money should increase clarity, not accidentally remove someone’s privacy.
Keeping control of the routine
The best way to use FaithFi is to give it a defined job. I would not ask it to replace every financial tool I already use. Instead, I would use it as a review layer: a place to connect financial actions with faith and personal priorities, while leaving transaction confirmation and formal records to the services designed for those tasks.
A simple routine could be divided into three steps. First, I would review the immediate facts using my bank or card provider. Second, I would use FaithFi to reflect on patterns and decide what deserves attention. Third, I would write down one action that is small enough to complete before the next review. This prevents the app from becoming a source of vague inspiration with no practical follow-through.
I would also avoid setting goals that are so ambitious they create shame. A faith-based finance tool should support honest reflection, not turn every imperfect month into a moral verdict. If the language or structure makes me feel pressured rather than helped, I would step back and use only the parts that encourage constructive action. The app is a tool; it should not replace personal discernment, a conversation with a trusted adviser, or professional help when debt and financial risk are serious.
The optional purchase model is another reason to keep the routine deliberate. Because the app is free to install but offers items within the app, I would decide in advance what I am willing to pay for and why. I would not purchase simply because a locked element appears during a moment of frustration. Waiting a day is a useful test: if the feature still seems valuable after I have used the free experience, then I can make a calmer decision.
Who will appreciate it, and who should skip it
I think FaithFi is most suitable for a Christian user who wants money management to reflect faith-based priorities and who enjoys guided reflection rather than purely numerical dashboards. It may also suit someone beginning to build a budgeting habit, because the spiritual framing can provide motivation when charts and categories alone have not worked.
It is less suitable for someone who wants automatic, highly detailed financial aggregation, professional investment analysis, complex debt modeling, or business bookkeeping. In those situations, established specialist tools are likely to offer deeper controls and more mature reporting. I would also suggest skipping it if you are uncomfortable with religious framing in financial guidance. The app’s central idea is not a small decorative theme that can be ignored; it shapes why the product exists.
People with complicated financial circumstances should be especially cautious about treating any app as a complete answer. If I were dealing with overdue obligations, legal questions, major investment decisions, or a business cash-flow problem, I would seek qualified advice and use FaithFi only as a personal reflection aid. Its strength is helping me think about everyday choices, not replacing expertise.
How it compares with ordinary finance apps
Compared with a bank application, FaithFi is less about immediate account servicing and more about the meaning behind financial behavior. My bank can usually answer a factual question quickly: what was charged, when money moved, or whether a payment is pending. FaithFi is more relevant after that question has been answered and I want to decide what the pattern says about my priorities.
Compared with a standard budgeting app, the distinction is motivational rather than merely technical. A traditional budget may tell me that a category is over its limit. FaithFi’s faith-centered approach can prompt a second question about discipline, generosity, contentment, or stewardship. That can be powerful for the right person, but it may feel unnecessary to someone who wants neutral financial organization.
Compared with a devotional or inspirational app, it has a more practical subject: actual financial decisions. That combination is its clearest point of difference. Still, I would not expect spiritual encouragement alone to provide the detailed controls found in a dedicated budget manager. The sensible choice may be to use both: one tool for precise records and FaithFi for values-based review, provided the extra effort does not become burdensome.
My cautious verdict after using it
FaithFi: Faith & Finance has a clear purpose, and I respect that it does not pretend money is only a collection of transactions. Its strongest contribution is helping a user connect everyday spending and saving decisions with faith-based priorities. For someone who has tried ordinary budgeting tools and found them technically useful but personally unmotivating, that perspective could make a real difference.
My recommendation comes with boundaries. I would start with the free experience, enter only the information needed to evaluate the app, review every purchase choice carefully, and keep a bank or specialist finance tool as the source for concrete account facts. I would pay attention to visible permissions, sign-in and account settings, and the way the app explains user choices. Trust should come from controls I can inspect, not from branding or good intentions.
The moderate average rating and relatively small audience make me favor a trial over an immediate commitment. If the app helps me establish a calm weekly money review and gives my goals a meaningful foundation, it can earn a regular place on my device. If I need precision reporting, automatic account management, or advanced financial analysis, I would choose a dedicated alternative instead.
In short, I see FaithFi as a focused companion for intentional Christian money management, not a universal replacement for banking or budgeting software. Its real value appears when reflection leads to one specific, responsible action. Used that way, and with careful attention to permissions, purchases, and sensitive information, it offers a distinctive way to bring faith into financial decisions without asking the app to do a job it was never meant to handle.
FAQ
What is FaithFi: Faith & Finance, and who is it designed for?
FaithFi: Faith & Finance is a personal finance app built around Christian principles and biblical stewardship. It is designed for users who want practical help managing money while reflecting on generosity, saving, budgeting, and responsible spending. The app may appeal to individuals, couples, families, and small groups looking for faith-based guidance rather than a purely conventional budgeting tool.
What features does FaithFi: Faith & Finance offer?
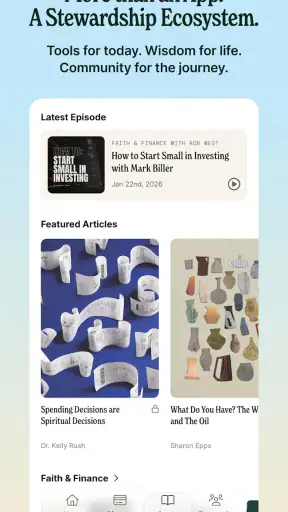
The app combines financial education with faith-centered content. Depending on the current version, users may find budgeting guidance, articles, podcasts, devotionals, Bible-based financial lessons, and resources addressing topics such as debt, giving, saving, and contentment. It is best understood as a source of encouragement and financial learning, although users should check the latest app listing because available tools and content can change.
Is FaithFi: Faith & Finance free to download and use?
FaithFi may be available to download at no initial cost, but some content, programs, or premium resources could require an in-app purchase, subscription, or separate membership. Before downloading, review the Google Play or App Store listing for the current pricing structure, trial terms, renewal conditions, and supported payment options. Always confirm subscription details before starting a trial to avoid unexpected charges.
Does FaithFi provide personalized financial advice or manage my money?
FaithFi is primarily an educational and inspirational resource, not a replacement for a licensed financial adviser, tax professional, credit counselor, or investment manager. It can help users think through financial habits and biblical stewardship, but it should not be treated as individualized advice. The app generally does not make decisions for you, guarantee financial results, or manage investments on your behalf.
Is FaithFi: Faith & Finance safe, and what should I know about privacy?
Before using FaithFi, review its privacy policy and the data-safety information shown in your device’s app store. Pay attention to whether the app collects account details, usage information, contact data, or analytics, and whether any information is shared with service providers. Avoid entering sensitive banking credentials unless the app clearly explains why they are needed and how they are protected.


