Expense IQ Money Manager

- 2.81K Reviews
- 3.2
- Downloads
- 1.00M
- 2.3.2
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
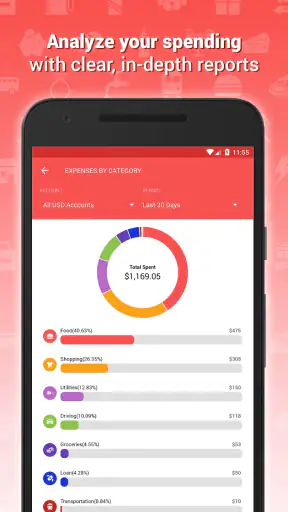
- Clear expense categories make spending patterns easy to understand.
- Recurring transactions reduce the effort needed for regular bills.
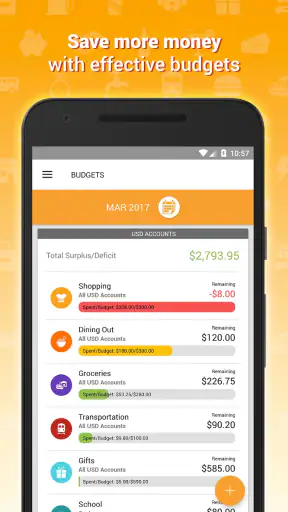
- Budget alerts help users notice overspending before it becomes a habit.
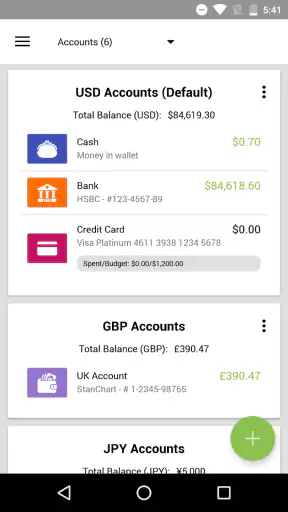
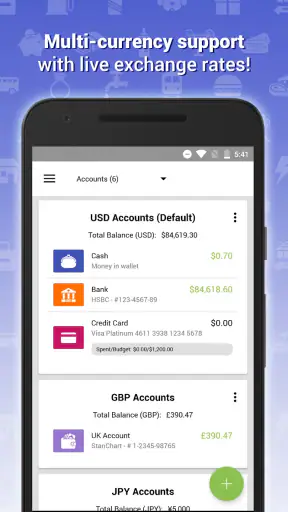
- Multiple account support suits users managing cash
- cards
- and bank balances.
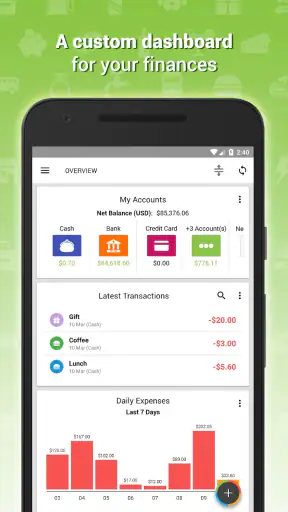
- Useful charts provide a quick visual overview of financial activity.
Cons
- Some advanced features may require an upgrade or paid version.
- Manual transaction entry can feel tedious for frequent daily purchases.
- Bank synchronization availability may vary by country and financial institution.
- The interface can seem busy until users become familiar with its menus.
- Cloud backup and data transfer may require careful setup between devices.
Review of Expense IQ Money Manager Appxis
I spent time using Expense IQ Money Manager as a practical finance app rather than treating it as a simple list of purchases. Its main appeal is the attempt to bring daily spending, budgets, bills, and broader money organization into one place. That sounds convenient, but finance apps earn trust differently from games or casual utilities: I want to understand what I am recording, what I can control, and how much responsibility remains with me.
Expense IQ is made by Handy Apps and is available as a free Android app for everyone. It has passed one million installs, with an average score of 3.2 from roughly twenty-three thousand ratings and about two thousand eight hundred written reviews. Those figures suggest a sizeable audience, but also a mixed experience. I would not install it expecting a flawless, automatic financial assistant. I see it more as a hands-on expense tracker for people willing to maintain their own records.
How Expense IQ feels when money organization is the priority
The first useful distinction is between tracking money and managing money automatically. Expense IQ is strongest when I use it as a deliberate record of what happened: a meal, a transport payment, a subscription, a household bill, or an irregular purchase. The act of entering and classifying those transactions can make spending patterns easier to notice, especially when bank statements feel too broad or arrive too late.
That approach also explains where the app may feel less effortless than newer finance tools. A bank-connected service can reduce manual work by importing activity, while a personal money manager asks me to stay involved. I prefer that involvement when I want to decide exactly how a purchase is categorized. I also recognize the downside: if I stop recording transactions, the budget view becomes less useful because it reflects incomplete information.
The app’s all-in-one design brings several jobs together. I can think about a monthly limit, upcoming bills, and individual expenses without switching between a notes app, a calendar, and a spreadsheet. That is valuable for someone who wants a single routine. It is less attractive for a person who only needs a quick glance at a bank balance or who dislikes entering financial details by hand.
In everyday use, I would begin with a small number of categories that match real decisions: groceries, eating out, transport, housing, recurring services, and flexible spending. Overbuilding the category system is a common mistake. If every purchase needs a long explanation, recording becomes a chore. A simpler structure makes it easier to keep the information current and still reveals where money is going.
A realistic weekly routine
Imagine someone paid on the last working day of the month and wants to avoid running short before the next pay cycle. On payday, I would record the expected income, reserve the known bills, and set a practical limit for flexible expenses. During the week, I would enter purchases close to the time they happen instead of waiting until the weekend. That small habit matters because memory is poor at reconstructing small cash payments and split purchases.
At the end of the week, I would compare the budget with actual spending rather than judging the month emotionally. If restaurants are taking more than expected, the useful response is not simply to create a harsher limit. I would ask whether the category is too broad, whether a bill was placed in the wrong period, or whether the budget was unrealistic from the start. Expense IQ is helpful here because it gives me a place to inspect the record, but it cannot make those decisions for me.
One less obvious advantage of manual review is that it exposes timing problems. A bill may be affordable over a full month but still create pressure during a particular week. A budget planner that looks only at a monthly total can hide that uneven cash flow. I would therefore use the app alongside my actual account balance, not as a replacement for checking whether money has truly arrived or cleared.
Budgets and reminders need careful setup
The budget side is most useful when limits are based on observed behavior rather than wishful thinking. If I set every category extremely low, the app may show repeated overspending without helping me change anything. A better workflow is to watch a normal period, identify the categories that matter, and then adjust one or two limits at a time. That turns the tracker into a feedback tool instead of a source of guilt.
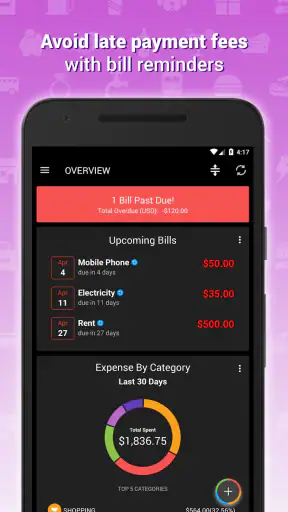
Bills are another area where precision matters. A reminder can help me remember an obligation, but I would still verify the amount, due date, payment method, and whether the bill has changed. I would not treat a reminder as proof that a payment was completed. After paying, I would update the transaction so the planned obligation and the real movement of money do not drift apart.
There is a useful trade-off here. Keeping bills and expenses in the same money manager gives me a more complete picture than storing reminders separately. However, combining planning with recording can also create confusion if I leave old planned items untouched. My advice is to make a short monthly maintenance appointment: review recurring entries, remove anything no longer relevant, and check that categories still describe current life.
For irregular costs, I would avoid pretending that a single monthly budget tells the whole story. Annual insurance, school expenses, repairs, gifts, and travel can make a month look unusually expensive. Recording them separately or using a dedicated category helps prevent ordinary spending from appearing responsible only because a large occasional cost was ignored.
Trust begins with visible choices
With any finance app, I pay attention to the difference between what I choose to enter and what the app might handle behind the scenes. Expense IQ’s most comfortable use case for me is one where I consciously add the financial information I want to organize. That gives me a clear role: I know the quality of the results depends on the completeness and accuracy of my entries.
I would not assume that an app’s presence in the finance category makes it a financial institution, bank, adviser, or secure vault for every kind of sensitive document. I use it for budgeting and expense organization, not for storing passwords, card security codes, identity documents, or anything unrelated to tracking household money. That boundary is sensible regardless of the app.
Before adding detailed information, I would inspect the permission prompts and the privacy choices shown on my device. Permissions should be understandable in context, and I would decline anything that does not fit the way I plan to use the app. If a feature requires access that I am uncomfortable granting, I would rather keep the workflow manual or choose a different tool than approve access automatically.
This is especially important because finance records can reveal routines: where I shop, when I travel, which services I pay for, and how my household operates. Even when an app is useful, I should limit the information to what improves the task. I would avoid entering unnecessary notes that identify other people, exact locations, or sensitive personal circumstances.
Account control and the cost of convenience
Expense IQ is free to download and use, while in-app purchases range from a few dollars to well over a hundred dollars per item. That range makes it worth checking the purchase screen carefully before confirming anything. I would look at which function is being offered, whether it is a one-time purchase or another billing arrangement, and whether the free workflow already covers my needs.
For a personal budget, paying may be reasonable if it removes a specific limitation that affects my routine. I would not pay simply because a premium prompt appears while I am still deciding whether I can maintain the habit. The best test is to use the basic experience long enough to discover whether I actually record transactions consistently. A feature cannot solve a routine I do not follow.
I also recommend keeping control of the underlying records. I would periodically review important totals against bank statements and retain any information I would need if I changed apps. A finance tool should support my organization, not become the only place where I know what happened to my money. If an app makes me dependent on a particular interface, the practical cost of switching can be higher than the purchase price.
The current version is 2.3.2, and the app supports Android 4.4 and later. That broad device compatibility may help people using older phones, but I would still keep the operating system updated where possible. An older phone can be perfectly adequate for a budget tool, yet device security, backups, and screen-lock habits remain my responsibility.
Where the app is strong—and where another option wins
Compared with a spreadsheet, Expense IQ gives the money-management process a more focused home. I do not need to design formulas or remember which column controls a total. That makes it friendlier for someone who wants structure without learning spreadsheet techniques. The trade-off is flexibility: a spreadsheet can be shaped around unusual household arrangements, shared finances, reimbursements, or custom forecasting in ways a fixed app may not match.
Compared with a bank’s own spending view, this app can be more intentional. Bank categories may be broad or assigned in ways I would change. A personal tracker lets me think in terms of my own budget decisions. The bank remains better for confirming balances and completed transactions, though, because it is the source connected to the actual account. I would use the two for different purposes rather than treating one as a complete substitute for the other.
Compared with a modern automatic finance service, Expense IQ may demand more effort. Automatic tools can be attractive to people who want accounts and transactions gathered with minimal input. Their convenience comes with a different trust decision: I must be comfortable connecting financial accounts and reviewing how that connection works. A manual tracker avoids that particular dependency in my routine, but only if I accept the work of entering and checking information myself.
That makes the app a good fit for someone who wants visibility without handing every financial detail to an automated dashboard. It is also suitable for a student, freelancer, or household organizer who needs to separate predictable bills from flexible purchases. I would be more cautious recommending it to a couple who needs live shared access, complex account reconciliation, or a detailed investment picture. Those needs call for a tool designed around collaboration or specialized financial reporting.
Small habits that make the records more reliable
My first practical tip is to record refunds and reversals explicitly instead of deleting the original purchase. Deleting can make a category look cleaner, but keeping the history helps explain why the total changed. I would label the return in a consistent way and check that it affects the correct period. This is particularly useful when a purchase and refund fall in different weeks.
My second tip is to separate a planned bill from the final transaction until payment is confirmed. That prevents me from mentally spending money twice or assuming a reminder equals completion. Once the payment clears, I would reconcile the amount and date. If the amount varies, I would update the record rather than leaving a recurring estimate that quietly becomes inaccurate.
My third tip is to use the app for decisions, not just archiving. Once a week, I would choose one question to answer: Which category surprised me? Which bill is approaching? Did a budget limit reflect reality? This keeps the review short and turns the information into an action. A finance app becomes much less valuable when it is only a diary of mistakes discovered long after they happened.
I would also avoid entering every tiny detail if the process starts damaging consistency. For some people, a daily total for cash spending is more sustainable than recording every low-value item individually. For others, individual entries reveal patterns that totals hide. The right level of detail is the one I can maintain while still answering the financial questions that matter to me.
Who should choose it, and who should skip it
I would recommend Expense IQ to a person who wants a dedicated money manager, prefers to make their own categories, and is comfortable checking entries regularly. It can be a sensible middle ground between loose notes and a bank-connected system. The free starting point also makes it easier to test the habit before deciding whether any in-app purchase is worthwhile.
I would skip it if I want completely automatic tracking, real-time account aggregation, advanced investing tools, or a shared household workspace as the main purpose. I would also skip it if manual entry feels like an obligation I will abandon after a few days. In that situation, the most feature-rich budget planner will still produce an incomplete picture.
The mixed average rating is a useful reminder to keep expectations realistic. A finance app can be technically capable and still feel frustrating when its workflow does not match a person’s habits. I would judge this one by a simple test: after a week, can I explain where my money went and what I plan to change? If the answer is yes, it is doing something valuable. If the answer is no because recording is too cumbersome, another category of tool may serve me better.
My cautious verdict is that Expense IQ Money Manager is worth trying for hands-on budgeting, bill organization, and personal expense review. I like the control that comes from deciding what gets recorded and how it is categorized, but that control comes with responsibility. I would keep sensitive information to a minimum, review permissions and purchase choices carefully, compare important figures with my real accounts, and maintain a backup or independent record of anything essential.
The app is most trustworthy as an organizing aid, not as a replacement for financial judgment. Used that way, it can turn scattered spending into information I can act on. Used as an automatic authority or a complete record of my financial life, it is not the right choice. That distinction is the key to getting practical value from Handy Apps’ finance app while keeping the final decisions—and the sensitive information—firmly under my control.
FAQ
What is Expense IQ Money Manager used for?
Expense IQ Money Manager is a personal finance app designed to help you track spending, organize income and expenses, manage budgets, and monitor your overall financial habits. After setting up accounts and categories, you can record transactions manually, review summaries, and use charts or reports to understand where your money is going. It is best suited to users who want a detailed budgeting tool rather than a simple expense notebook.
Does Expense IQ Money Manager connect directly to my bank accounts?
Expense IQ primarily focuses on manual financial tracking, so users should not assume that every bank or financial institution can be connected automatically. Depending on the app version, region, and available features, some data may need to be entered or imported manually. Before relying on the app for complete account synchronization, check the current listing and settings to confirm whether your bank supports the connection you need.
Can I use Expense IQ Money Manager to create budgets and spending limits?
Yes, budgeting is one of the app’s main purposes. You can generally create spending plans for categories such as groceries, transportation, bills, entertainment, or shopping, then compare your actual transactions with those targets. This makes it easier to identify overspending during the month. The quality of your budget depends on consistently recording transactions and assigning them to the correct categories.
Is my financial information safe in Expense IQ Money Manager?
Expense IQ may provide privacy and security features such as application access protection, backups, and data management options, but users should review the current privacy policy and permissions before entering sensitive information. Avoid storing unnecessary banking credentials or confidential details, keep your device protected with a strong lock screen, and download the app only from an official store to reduce security risks.
Is Expense IQ Money Manager free, and are there premium features?
Expense IQ can typically be downloaded and used with core money-management functions, although the exact free features, advertisements, and premium options may vary by platform and app version. Advanced tools, extra reports, customization, synchronization, or an ad-free experience may require an upgrade. Check the Google Play Store or Apple App Store listing for the current pricing and subscription terms before downloading.


