

EarnIn: Why Wait for Payday?
Activehours Inc.Finance
Scanned and Safe · Free
- Rating
- 4.8Out of 5
- Downloads
- 10.00M
- Android
- 8.0
Screenshots
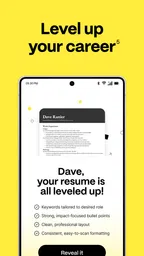
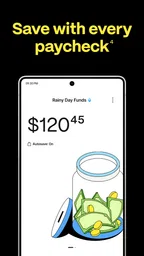
Analysis by Appxis
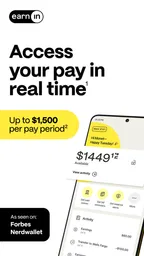
When a bill is due before payday, the problem is often timing rather than a lack of income. EarnIn is built around that gap: it lets eligible workers access some of the wages they have already earned before their regular pay arrives. I see the appeal in a narrow, practical use case—covering a necessary expense without turning a few days of bad timing into a longer borrowing problem. It is best thought of as a bridge, not extra income or a way to make an overstretched budget work indefinitely.
Getting money before payday, with limits
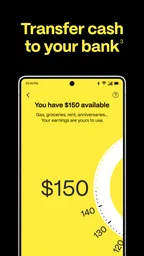
The central idea is straightforward: request an advance against earned pay, then use the money before the next paycheck. The current offer allows access to up to $150 a day, with a maximum of $1,000 per pay period. Those are ceilings, not promises that every user can withdraw those amounts; what you can access depends on your circumstances and earnings. That distinction matters when deciding whether to rely on it for a bill with a fixed deadline.
For a realistic example, imagine your utility payment is due on Tuesday, but your normal payday is Friday. If you have already earned wages and the app makes an amount available, an early transfer could help you avoid a late payment. I would still check the due date, transfer timing and repayment impact before requesting money. An advance solves a timing mismatch, but it does not reduce the bill or increase what you earn.
How I would use it without creating a cycle
I would reserve EarnIn for specific, short-lived gaps: an essential expense, an unusually timed payment, or a small emergency that would otherwise lead to a costly consequence. Before tapping to cash out, I would write down the amount needed and compare it with the next paycheck’s expected bills. Taking the smallest amount that handles the immediate need is a more cautious approach than treating the available limit as spending money.
A useful habit is to record the advance alongside the bill it covers and review the next pay period before making another request. That simple step makes the trade-off visible: money arriving early will affect what remains later. If the same shortfall appears every pay cycle, the pattern is a signal to look at recurring expenses, payment dates or longer-term budgeting rather than repeatedly leaning on an advance.
Where it sits among money options
Compared with a traditional payday loan, an earned-wage advance is designed around pay already accumulated rather than a new loan sized against future income. That can make it a more fitting option for a brief cash-flow pinch, but it should not be confused with free money. Tips, timing and the effect on the next paycheck still deserve attention. A bank’s overdraft protection or a bill provider’s payment arrangement may be a better first call if it avoids pulling money forward altogether.
A credit card can be more convenient for a purchase if the balance can be paid in full, while a personal loan is generally aimed at a larger, planned expense rather than a few days between paychecks. Those alternatives have their own costs and risks, so I would compare the actual amount due and repayment date instead of assuming one tool is always cheaper. EarnIn makes the most sense when the need is limited, the pay is already earned, and the following check can absorb the earlier access.
More Stories While You Read
What is EarnIn?
In the world of financial apps, EarnIn stands out with its unique approach to payday advances. Unlike traditional payday loans that come with hefty interest rates, EarnIn offers a more user-friendly solution by letting you access a portion of your earned wages before your official payday. It’s like getting a sneak peek at your paycheck without any strings attached.
Getting Started with Ease
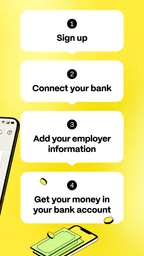
Starting with EarnIn is a breeze. Once you download and install the app on your Android or iOS device, the setup process is pretty straightforward. You’ll need to link your bank account and provide some employment details to prove your income. But no worries, the app ensures all your information is secure and encrypted. What I love about EarnIn is its seamless interface. It’s clean, intuitive, and makes accessing your money feel like a walk in the park.
For first-time users, I would treat setup as a point to double-check that the account details and employment information match your real situation. That can help prevent an avoidable snag when you need access quickly. I would also open the app before an urgent bill is due, rather than waiting until the last minute; using any financial service for the first time under pressure makes it harder to check the amount, timing and impact calmly.
Features That Make a Difference
One of the standout features of EarnIn is its Cash Out option. Imagine you’re halfway through the month and an unexpected expense pops up – maybe your car decides to take a day off. With EarnIn, you can cash out up to $100 per day, up to $750 per pay period, depending on your earnings. And the best part? No fees or interest rates. They operate on a tip-based system, allowing you to pay what you think is fair, even if it’s nothing at all.
The app is free to download, but I would separate that from the cost of using an advance. A voluntary tip may still affect how much the service costs you in practice, so decide deliberately rather than accepting a prompt on autopilot. The current cash-out limits are described above; the older figures in the feature description here should not be used as a budgeting guarantee. Always base a decision on the amount shown to you in the app at the time.
Another nifty feature is the Balance Shield. We’ve all been there – that terrifying moment when your bank balance is dangerously close to zero. Balance Shield sends you notifications when your balance is low and even offers a cash out to prevent overdraft fees. It’s like having a financial guardian angel watching over your account.
I would treat a low-balance alert as a prompt to review upcoming payments, not as an automatic reason to take an advance. If the alert arrives before several scheduled expenses, list those expenses and their dates first; one small withdrawal might not cover the whole week. This is also where it helps to distinguish a one-off timing issue from a recurring gap. A notification can draw attention to the problem, but the useful decision still comes from checking what is due and what the next check must cover.
Insights and Community
But EarnIn isn’t just about financial transactions; it’s about building a community and offering insights. The app provides a section called Health Aid, where users can access free financial resources and tools to improve their financial well-being. Whether it’s tips on budgeting or finding ways to save, EarnIn goes beyond just a payday advance app.
For me, the strongest use of financial guidance is to turn a temporary fix into a better routine. If a cash shortfall repeats, I would use budgeting material to identify whether the cause is a bill date, an irregular expense or a spending category that has crept up. That does not make the advance itself a budgeting solution, but it can help put the immediate choice in context and make the next payday less of a guessing game.
Moreover, the community aspect is pretty engaging. You can see what others are tipping and even join in on discussions about financial wellness. It’s a platform that encourages users to support one another, making it more than just a transactional app.
Community discussion can be useful for ideas, but I would not use another person’s tip choice or cash-out experience as a guide to what is right for my own finances. People have different pay schedules, obligations and cash-flow needs. The more dependable personal check is whether the advance covers a specific need and whether the remaining paycheck can still handle the bills already lined up.
Is EarnIn Right for You?
So, who exactly benefits from EarnIn? If you’re someone who occasionally finds yourself in a pinch before payday, this app can be a lifesaver. It’s particularly useful for those who want to avoid the pitfalls of traditional payday loans and their exorbitant fees. Plus, the flexibility of tipping means you’re not forced into paying more than you’re comfortable with.
EarnIn is developed by Activehours Inc. and sits in the finance category, where its focus is narrower than a full banking app: it is meant to help with access to earned pay, not replace an everyday account or a complete money-management setup. It is free to install, has an Everyone age rating, and its current version is 16.21. The app has a 4.7 average from around 279,000 ratings, with over 10 million installs, which suggests many people have considered it useful; popularity alone, of course, does not tell you whether the timing and repayment fit your own budget.
I think the best fit is someone with steady income who can point to a temporary mismatch between the day a necessary expense lands and the day wages arrive. It is less suitable if income is unpredictable, if the next paycheck is already committed to essentials, or if you need a large amount for a long-term problem. In those situations, asking a biller about a payment arrangement, reviewing recurring costs or seeking qualified financial guidance may be safer than shifting the shortfall into the next pay period.
One question people naturally have is whether the advertised maximum will be available right away. I would not plan around the headline limit: the amount shown in the app is what matters for an individual request, and eligibility can depend on the user’s circumstances. Another practical question is when the money will arrive. Because a bill deadline can be unforgiving, I would check the transfer details in the app before counting on an advance for a same-day payment, and keep a backup plan if missing the deadline would have serious consequences.
It is also worth asking whether using the app affects the next payday. The essential trade-off is that you are receiving part of already-earned income early, so that amount is no longer available as new money when the regular pay arrives. I would make a quick list of the next check’s fixed obligations—housing, utilities, transport and other scheduled payments—before deciding. If that check cannot comfortably cover them after the advance, the app may postpone the immediate stress while making the following week harder.
On Android, the minimum operating-system requirement is version 8.0. The app was released on January 21, 2014, and its current version is 16.21; for me, those details are most useful as a compatibility check rather than a reason to expect any particular experience. If you are deciding whether to install it, first make sure your device meets the requirement, then consider whether you need this kind of wage-timing tool at all. A finance app is only helpful when its role is clear and its use does not become another routine expense.
However, it's worth mentioning that EarnIn isn’t a solution for chronic financial issues. It’s more of a short-term relief option rather than a long-term financial strategy. But for those moments when you need a quick financial boost, it’s a reliable option to have in your back pocket.
In conclusion, EarnIn is like that friend who’s always there to spot you a few bucks when you’re short. It’s user-friendly, community-driven, and refreshingly free of hidden costs. So, if you’re looking to take control of your finances and bridge the gap between paychecks, give EarnIn a try. It might just be the financial sidekick you’ve been searching for.
Pros
- Instant access to earned wages.
- No interest or hidden fees.
- Helps avoid payday loans.
- Easy-to-use interface.
- Supports financial planning.
Cons
- Requires access to bank account.
- Limited to certain employers.
- May encourage spending.
- Potential privacy concerns.
- Not a substitute for savings.
EarnIn: Why Wait for Payday? FAQ
What is EarnIn and how does it work?
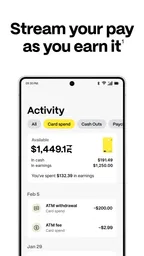
EarnIn is a financial app that allows you to access your earned wages before your payday. By linking your bank account and providing your employer information, you can withdraw a portion of your earned wages without waiting for the traditional payday. The app provides flexibility, helping you manage your finances better and avoid overdrafts, late fees, or payday loans.
Is there a fee to use EarnIn?
EarnIn does not charge mandatory fees or interest for using its services. Instead, it operates on a voluntary tipping system where users can choose to support the app by tipping an amount of their choice. This model makes EarnIn accessible to everyone, regardless of their financial situation, and helps promote financial inclusion.
How quickly can I get my money with EarnIn?
With EarnIn, you can receive your money almost instantly, especially if you use the Lightning Speed feature. This feature allows users to access funds within minutes, although availability can vary based on your bank's processing times. Typically, funds are available within one business day, providing a quick solution for urgent financial needs.
Is EarnIn safe and secure to use?
EarnIn takes user safety and security very seriously. The app uses bank-level encryption to protect your personal and financial information. Additionally, it requires multi-factor authentication to access your account, ensuring that only you can manage your financial transactions. Regular audits and updates further enhance security standards.
What are the eligibility requirements for using EarnIn?
To use EarnIn, you must have a steady income from an employer, a checking account with direct deposit, and a smartphone. The app also requires you to upload your timesheets if your employer does not use an electronic timesheet system. These requirements ensure that EarnIn can accurately track your earnings and provide timely financial assistance.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Activehours Inc.
- Package Name
- com.activehours
- Version
- 16.57
- Android
- 8.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@earnin.com, visit https://www.earnin.com, or view the https://www.earnin.com/privacy.