Ditch: Pay Off Debt Faster

- 62.00 Reviews
- 4.8
- Downloads
- 10.00K
- 1.5.6
- Version
Screenshots
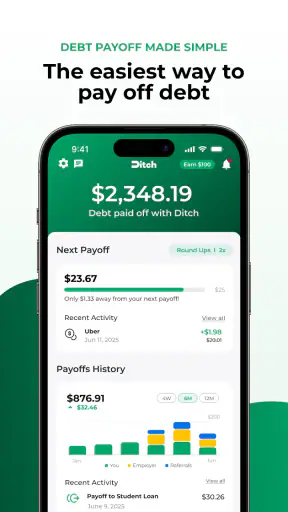
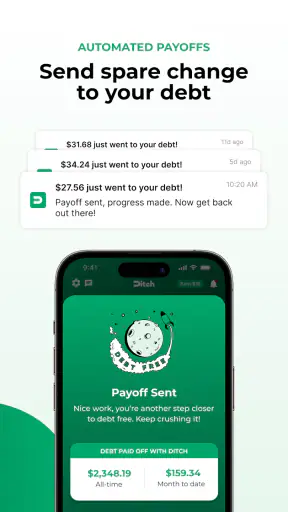
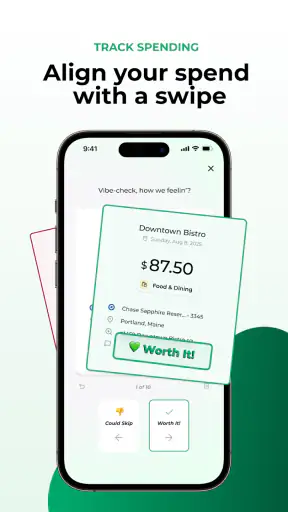
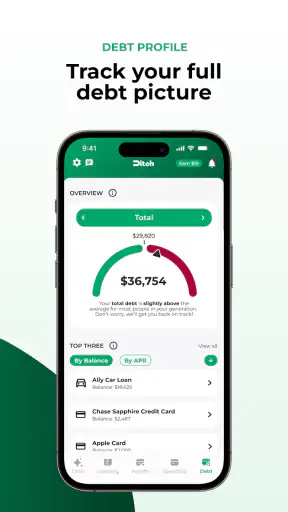
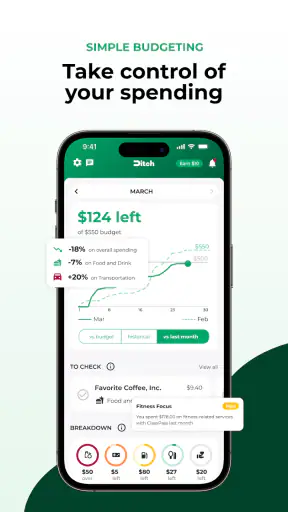
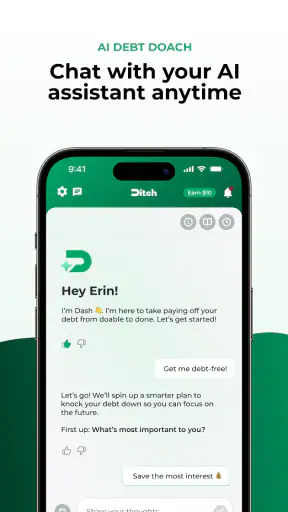
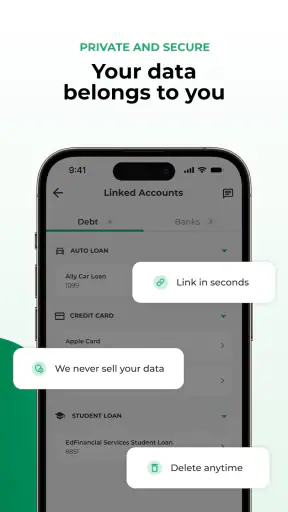
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Clear payoff tracking helps you see progress toward becoming debt-free.
- Supports focused repayment planning instead of leaving debts unorganized.
- Useful reminders can help prevent missed payments and late fees.
- Simple financial overview makes debt management easier to understand.
- Motivating progress visuals may encourage consistent repayment habits.
Cons
- May require manual updates if account balances are not synced automatically.
- Limited value for users with complex loans or irregular repayment schedules.
- Debt payoff estimates depend on accurate information entered by the user.
- Some advanced planning features may be restricted to paid plans.
- Does not replace professional advice for serious financial difficulties.
Review of Ditch: Pay Off Debt Faster Appxis
Debt payoff usually fails for a surprisingly ordinary reason: the plan is too difficult to maintain once real life gets busy. I found Ditch: Pay Off Debt Faster most useful because it turns repayment into something I can revisit regularly instead of a vague promise to “spend less.” It is a finance app from Ditch Technologies, Inc, designed around organizing debt, tracking progress, and automating parts of a payoff routine. The idea is simple, but the value depends on how carefully you set it up and how consistently you use it.
I would not describe it as a complete replacement for a bank app, a budgeting suite, or professional financial advice. I see it more as a focused debt-management companion. If you have several balances, struggle to see which payment should come first, or want a clearer picture of your progress, it gives that task a dedicated home. If your finances are already effortless to manage or your main need is investment tracking, it is probably not the right tool.
Building a debt routine that survives ordinary life
My preferred starting point is deliberately unexciting. I would enter every relevant debt carefully, check the balance and payment details against the latest statements, and avoid treating the first screen as a finished plan. The quality of any payoff schedule depends on the information behind it. A small mistake in a balance or required payment can make the progress view feel reassuring while pointing in the wrong direction.
Once the accounts are organized, I would use the app as a weekly or twice-monthly checkpoint rather than opening it constantly. A short review after payday works well: confirm what has changed, record payments, and decide whether extra money should go toward the selected priority. This habit is more useful than repeatedly checking a number without taking action.
The app’s central appeal is the connection between a payoff goal and a repeatable process. Instead of keeping separate notes for balances, due dates, and personal targets, I can use one place to see the debt picture. That reduces the mental effort of remembering what needs attention. It also makes a difficult goal feel more concrete because each payment becomes part of a visible sequence.
A realistic example would be someone with a credit card balance, a personal loan, and a store account. On payday, they open Ditch, review the required payments, and direct any planned extra amount toward the debt they have chosen to prioritize. After making those payments through their normal banking channels, they update the app so the remaining balances reflect reality. The important point is that the app supports the decision and tracking process; I would still verify transactions in the financial institution’s own app.
That distinction matters. I would not assume that opening Ditch automatically pays every bill or replaces the need to make payments through a lender. “Automate” is attractive language, but responsible use means checking exactly what the app is set up to do and what still requires action elsewhere. For me, the safest workflow is to use Ditch for planning and monitoring while treating the bank or lender as the final source for payment confirmation.
Another useful habit is separating fixed obligations from optional acceleration. Required payments keep accounts current, while extra payments change the speed of the plan. When those two ideas are mixed together, an ambitious month can become a stressful one. I prefer setting a base amount I can maintain even during an expensive month, then adding extra money only when my cash flow genuinely allows it.
This is where the app feels more practical than a spreadsheet for some people. A spreadsheet can be more flexible, but it also asks me to design formulas, maintain layouts, and remember which cell needs updating. Ditch offers a more focused experience for people who want the debt task presented directly. The trade-off is that a spreadsheet gives me more control over unusual situations, custom calculations, and broader household planning.
Settings that deserve attention before the first serious plan
I would spend time checking the core account details rather than rushing toward the most optimistic payoff date. Confirm the balance, minimum payment, interest information where applicable, and the timing of each obligation. Even when an app makes setup feel quick, debt planning is one of those areas where accuracy is more valuable than speed.
I would also decide what “success” means before changing the plan. Some people want the smallest balance gone first because early wins keep them motivated. Others prefer attacking the most expensive debt first to reduce interest over time. Ditch can help me track a chosen direction, but it cannot settle the personal trade-off between mathematical efficiency and emotional momentum. I would choose deliberately instead of switching strategies whenever progress feels slow.
Notification and reminder behavior is another area worth reviewing. A reminder should arrive early enough to help me act, not so often that I start ignoring it. If the app offers a choice of timing or frequency on the device, I would match it to my pay cycle and statement schedule. A reminder on the wrong day creates noise; one tied to a real financial routine can become a useful trigger.
I would be equally careful with any optional paid features. The app is free to install, while in-app purchases range from $5.99 to $89.99 per item. That makes it especially important to understand what is included before committing money. I would first establish whether the free experience handles my basic tracking needs, then evaluate a purchase against a specific problem I actually have. Paying for motivation is only worthwhile if the feature changes my behavior, not merely the appearance of the dashboard.
Privacy and account access also deserve common-sense attention. I would avoid entering information that is not necessary for my personal workflow, use a secure device lock, and review any connection or permission screen carefully. For sensitive financial decisions, convenience should not automatically win over control. If I prefer not to place debt information in a dedicated app, a local spreadsheet or paper system may feel more comfortable, even though it requires more manual work.
The age rating is Everyone, and the app supports devices running Android 8.0 or later. That makes it approachable for a broad range of users, including someone using an older compatible phone. Compatibility is not the same as suitability, though. A person sharing finances with a partner should agree on who updates the figures and how changes are recorded, otherwise the app can become another source of conflicting information.
Faster patterns that make the plan easier to maintain
The most effective shortcut I found is not a hidden button; it is reducing the number of decisions I make each month. I would choose a payoff order once, write down the rule for extra payments, and use the same review sequence every time: check balances, confirm required payments, record completed payments, and apply only the extra amount that is genuinely available. Repeating the same sequence prevents emotional spending decisions from taking over.
A second helpful pattern is to update immediately after a payment rather than waiting until the end of the month. The information is fresher, and the progress view remains trustworthy. If I wait too long, I may forget which payment belonged to which account or accidentally count the same payment twice. For anyone managing multiple balances, this small timing choice can prevent a surprising amount of confusion.
I would also create a “no extra payment” rule for unstable months. If rent, utilities, transport, or essential repairs are uncertain, the correct action may be maintaining required payments and keeping cash available. A payoff app can make acceleration feel virtuous, but sending every spare amount to debt can leave no buffer for the next emergency. Ditch works best when I use it alongside a basic cash-reserve decision, not instead of one.
Windfalls are another area where a written rule helps. Rather than deciding from scratch whenever a refund, gift, or unexpected payment arrives, I would split it according to priorities: some for immediate needs, some for a buffer, and some for the selected debt if the first two are covered. The app can show the effect of an extra payment, but the wiser amount depends on the rest of my household finances.
For couples or families, the practical shortcut is agreeing on one source of truth. If one person changes a balance in Ditch and another relies on a bank statement or a separate note, the payoff picture can drift. I would review the app together during a short monthly money meeting and treat disagreements as a signal to verify the lender’s records, not as a reason to keep editing numbers until the result looks better.
Compared with a standard budgeting app, Ditch feels narrower and more purposeful. A budgeting app may be better for categories, spending limits, income planning, and household cash flow. Compared with a spreadsheet, Ditch is easier to approach if I do not want to build a debt model myself. Compared with a lender’s app, it can provide a broader view when debts are spread across different companies, but the lender remains the place I would use to confirm account status and payment completion.
That focus is its strength and its weakness. I appreciate not having to wade through investment charts or a full spending taxonomy just to think about repayment. At the same time, someone whose debt problem is caused mainly by overspending may need a budgeting tool that explains where the money is going. Ditch can help organize the consequence, but it is not a complete diagnosis of the cause.
Where an experienced user should set limits
I would be cautious about treating any projected payoff result as a promise. Interest can change, fees can appear, balances can be corrected by a lender, and income can fluctuate. A plan is a working estimate, not permission to ignore statements. The app is most useful when I revisit assumptions after meaningful changes rather than assuming the original setup remains accurate forever.
There is also a behavioral limit. Tracking can create the feeling of progress without producing progress if I spend more time adjusting the plan than making payments. I would avoid endlessly comparing payoff orders or changing the target after every small change in income. Once the plan is sensible, execution matters more than optimization.
Another limitation is that focused debt tracking may not answer broader questions. If I need to compare refinancing offers, understand tax consequences, negotiate with creditors, or decide whether a debt is legally disputed, I would look for qualified guidance and the relevant lender documentation. Ditch may help me keep the situation organized, but it should not be treated as a financial adviser.
I would also skip it if I want a completely automated financial system with no manual checking. Even a well-designed payoff tracker cannot remove the need to confirm balances, review transactions, and notice when a lender changes terms. Anyone who dislikes updating financial information may abandon the app quickly, especially if their accounts require frequent corrections.
On the other hand, it is a strong fit for a person who has a clear repayment goal but lacks a dependable routine. The app has earned a 4.8 average from around 1.1 thousand ratings, and its install count is above 10 thousand. Those figures do not decide whether it fits my situation, but they suggest that the focused approach has found an audience. I would still judge it by whether it makes my own next payment easier to plan.
The current version is 1.5.6, so I would keep the app updated through the normal store process and recheck important settings after a substantial update. That is not unique to finance apps, but it matters more here because a small change in how information is displayed can affect how confidently I interpret a plan. I would keep my lender statements available instead of relying on memory.
My verdict after turning it into a repeatable system
Ditch: Pay Off Debt Faster works best when I treat it as a disciplined checkpoint, not a magic payment button. Its focused design makes debt feel more manageable, especially when several balances compete for attention. I like the way it encourages a visible payoff path and gives a routine structure to a task that many people otherwise postpone.
My strongest recommendation is to pair it with three habits: verify every account during setup, update the record soon after payments clear, and keep a separate rule for emergencies so that acceleration never threatens essentials. Those habits do more for the result than constantly searching for a more aggressive strategy. They also protect against the most common mistake in debt tracking: believing a neat progress screen without checking whether the underlying figures are current.
I would choose a broader budgeting app instead if spending control is my main problem, a spreadsheet if I need unusual formulas or highly customized household modeling, and a lender’s own app when I need official payment confirmation. I would choose Ditch when the central challenge is staying oriented and motivated across multiple debts.
As a free finance app for Everyone, with optional purchases that can reach $89.99 per item, it deserves a careful trial rather than an automatic upgrade. Start with the basic workflow, test whether the reminders and tracking fit your pay cycle, and only pay for something that solves a clearly identified limitation. For me, the app earns a recommendation because it makes a difficult goal easier to revisit, while still leaving enough room for sensible caution.
My final view is straightforward: if you want a dedicated place to organize repayment and you are willing to verify the details yourself, Ditch is a useful companion. If you expect it to replace banking, budgeting, emergency planning, or professional advice, you will likely find its focused scope limiting. Used with realistic amounts and a repeatable routine, though, it can turn debt payoff from an occasional worry into a process I can actually keep following.
FAQ
What is Ditch: Pay Off Debt Faster, and how does it help with debt repayment?
Ditch: Pay Off Debt Faster is a debt-management app designed to help you organize balances, interest rates, minimum payments, and payoff goals in one place. It can make it easier to understand your overall debt situation and compare repayment strategies, such as focusing on high-interest balances first or paying smaller balances for quicker progress. The app is best viewed as a planning and tracking tool rather than a lender or debt-consolidation service.
Can Ditch create a personalized plan for paying off my debts?
The app is intended to help users build a repayment plan based on details such as outstanding balances, interest rates, minimum payments, and the amount of extra money available each month. After entering accurate information, you can review estimated timelines and potential interest savings under different approaches. Results are projections, however, so they may change if rates, payments, fees, income, or spending habits change.
Does Ditch connect directly to my bank or credit-card accounts?
Whether account connections are available may depend on the current app version, your location, and the financial institutions you use. Some users may be able to enter debts manually, while others may see options for importing or linking financial information. Before connecting an account, review the permissions and privacy policy carefully. Manual entry can be a useful alternative if you prefer not to share login or financial data.
Is Ditch free to download, or does it include subscriptions and in-app purchases?
Ditch may be available to download at no initial cost, but some planning features, advanced tracking tools, or other functionality can be offered through a subscription or in-app purchase. Pricing and trial conditions may vary by platform and region. Check the Google Play Store or Apple App Store listing before downloading, and pay attention to renewal terms so you understand when charges may occur.
Is Ditch safe to use, and can it replace professional financial advice?
Ditch can be useful for organizing debt information and staying focused on repayment, but it should not be treated as a replacement for a qualified financial adviser, credit counselor, or legal professional. Avoid entering information you are uncomfortable sharing, use a strong device password, and review the app’s privacy and security details. If you are facing missed payments, collections, or serious financial hardship, seek independent advice before making major decisions.


