Deferit: Split Bills, Pay in 4

- 2.29K Reviews
- 4.6
- Downloads
- 1.00M
- 3.0.6
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Helps spread large bills across manageable payment dates.
- Clear repayment tracking makes upcoming installments easy to monitor.
- Useful reminders can help reduce missed payment risks.
- May provide financial breathing room during unexpected expenses.
- Simple interface makes bill-splitting tasks quick to set up.
Cons
- Eligibility requirements may vary and are not guaranteed for every user.
- Late payments could lead to fees or account restrictions.
- Using installments regularly may encourage overspending.
- Some bill types or merchants may not be supported.
- Payment schedules can be confusing when several plans overlap.
Review of Deferit: Split Bills, Pay in 4 Appxis
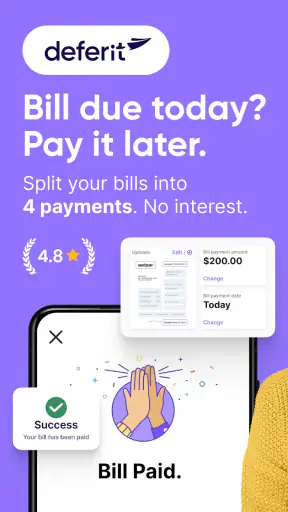
I came away from Deferit: Split Bills, Pay in 4 with a fairly clear impression: it is most useful as a short-term budgeting tool, not as a way to make expensive bills permanently affordable. The app turns one eligible bill into four smaller payments without interest, which can be genuinely helpful when the timing of a payment is the problem rather than the total amount. That distinction matters. If I had enough money overall but needed to bridge a gap between paydays, I could see the appeal immediately. If I were already struggling to cover regular expenses, I would be cautious about using another scheduled repayment.
Deferit is a finance app from Deferit, available free of charge and rated for Everyone. It has built a substantial audience, with more than a million installs, an average rating of 4.6 from roughly twenty thousand ratings, and about two thousand three hundred written reviews. Those figures suggest that the basic idea is easy for many people to understand, but they do not remove the need to think carefully about repayment dates and personal cash flow.
How the bill-splitting approach feels in everyday use
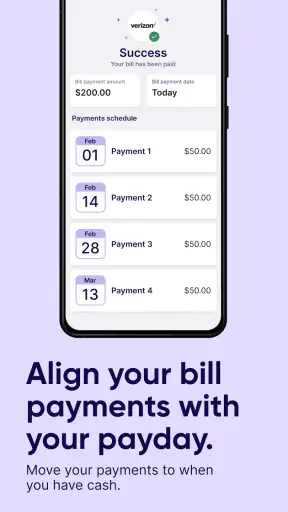
The central experience is simple to explain. Instead of handling a bill as one large payment, I can arrange it as four smaller payments spread across a schedule. The attraction is not a discount and it is not extra income; it is a change in timing. That makes the app particularly relevant for bills that arrive at an awkward point in the month, such as a utility charge, phone bill, insurance payment, or another ordinary household expense.
A realistic example would be a bill that lands just before payday, when my account is temporarily low even though my next payment is already expected. Paying the entire amount at once could force me to delay another necessary expense. Splitting it into four parts may make that week easier to manage. The trade-off is that the bill does not disappear after the first payment. The remaining installments become future commitments, so the relief is useful only if I have room for them later.
That is the first practical habit I would recommend: before confirming anything, I would look at the whole repayment calendar rather than focusing on the first installment. A smaller payment can feel comfortable in isolation while several active arrangements quietly add up. Deferit works best when I use it for one carefully chosen timing problem, not when I use it to make every bill appear smaller.
Where the app is stronger than paying a bill late
For someone deciding between an organized repayment plan and simply missing a due date, the structure is the strongest part of the concept. A planned sequence is easier to remember and easier to include in a budget than an unpaid bill that may lead to stress, follow-up messages, or a rushed payment later. The interest-free structure also makes the arrangement easier to understand than borrowing that grows through interest charges.
That does not mean the app should replace a normal bank payment whenever I can comfortably pay the bill in full. Paying directly is simpler and leaves no future installments to track. Deferit earns its place when payment timing is genuinely inconvenient and the four-part schedule fits my upcoming income.
I also like the psychological benefit of separating a large obligation into manageable steps, provided I treat those steps as real obligations. People often budget around what is due today and forget what is already promised for next week. The app’s value depends on resisting that temptation. I would use it alongside a basic calendar or budget note, especially if several household bills fall in the same period.
What I would check before relying on it
The most important question is eligibility. Not every bill or situation should be assumed to work in the same way, so I would enter the app with a specific bill in mind and read the details shown before committing. I would also check the payment schedule, the amount of each installment, and how the arrangement fits with other automatic payments already leaving my account.
Another sensible check is whether the first payment solves the real problem. If the initial amount is still too high, or if the next three payments collide with rent, groceries, transport, or debt repayments, splitting the bill may only move the pressure forward. In that situation, contacting the bill provider directly, asking about a payment arrangement, or using a conventional budgeting method may be safer.
One less obvious use is planning around irregular income. A freelancer or shift worker may have a month in which income arrives unevenly rather than on a fixed payday. Four smaller payments can make a known bill easier to place between those income events. However, that only works when the user has a reasonably reliable expectation of future money. It is not a substitute for an emergency fund, and I would not treat an uncertain invoice as guaranteed cash.
The meaningful weakness: convenience can hide accumulated commitments
The main weakness is built into the product’s greatest strength. Dividing a bill makes the immediate decision feel lighter, but it can also make borrowing-like commitments feel less serious. Even without interest, I am still committing future money. If I repeat the process across several bills, the total scheduled amount may become difficult to see at a glance.
This is why I would avoid using Deferit for discretionary purchases or recurring overspending. The app makes more sense for a temporary mismatch between the date a bill is due and the date money becomes available. It is much less suitable when the monthly budget is already short. In that case, splitting bills can postpone the warning sign instead of fixing the underlying gap.
I would also be careful during months with unpredictable expenses. A car repair, medical cost, school expense, or unusually high energy bill can make future installments harder to absorb. The four-payment format may look manageable when I start, but a new emergency can turn several modest commitments into a serious squeeze. Anyone using the app should leave some breathing room rather than budgeting every remaining dollar.
There is also a simplicity trade-off. A direct payment through a bank account or bill provider usually has fewer moving parts. A traditional savings plan is slower but gives me more control and does not create a repayment schedule. Deferit is convenient in the middle ground: more flexible than paying everything immediately, but more structured and potentially more complicated than simply waiting until I have saved the full amount.
Useful habits for keeping the arrangement under control
I would start by using the app for one bill, then observing how the installments affect the rest of the month. That small trial tells me more than the promise of a smaller first payment. If the schedule fits naturally and leaves room for essentials, the service may be useful. If I need to rearrange several other payments to make it work, that is a warning that the timing problem is larger than the app can solve.
A second useful habit is to label each arrangement by the bill it belongs to. “Electricity” or “mobile service” is more informative than a vague note saying “payment.” This makes it easier to understand which commitments will end and which ones are still active. It also prevents the common mistake of assuming that a lower current payment means a lower total obligation.
Third, I would avoid stacking a new split arrangement on the same day that several earlier installments are due. Even if each amount looks harmless, the combined withdrawal can create a sudden shortage. Looking at the calendar by week, rather than only by month, gives a more realistic picture of cash flow.
Finally, I would keep enough money available for essential direct debits before using the app for a less urgent bill. The service should support a budget that already has a plan, not become the plan itself. That is the difference between using it as a bridge and using it as a permanent patch.
Who will get the most from Deferit?
I think the best audience is someone with predictable income, a temporary timing issue, and a clear understanding of the upcoming installments. For that person, the interest-free four-part structure can reduce the shock of a large bill without requiring a traditional credit product. It may be especially practical for households that experience several bills arriving close together but can comfortably cover them across the following weeks.
It can also suit a careful user who wants a visible schedule rather than relying on memory. The app’s value comes from organization as much as from the split itself. If I know exactly when money will arrive and can match that with the repayment dates, I can make a more informed decision than I could by simply delaying payment.
I would recommend skipping it, or at least considering alternatives first, if income is unstable with no dependable payment date, if existing debts already consume most of the budget, or if the bill is something I could postpone without serious consequences. Someone building a long-term financial cushion would be better served by saving ahead, even though that takes more patience. Someone facing a genuine affordability problem should look for support from the bill provider or a qualified financial adviser rather than repeatedly dividing bills.
The age rating of Everyone makes the app broadly approachable, but that should not be confused with suitability for every financial situation. The important question is not whether the interface is easy to use; it is whether the repayment plan remains comfortable after essentials and unexpected costs are considered.
How it compares with the usual alternatives
Compared with paying a bill in full through a bank account, Deferit offers more breathing room but adds future dates to monitor. The normal payment wins when I already have the money and want the cleanest possible arrangement. Deferit wins when the money is available soon but not at the exact moment the bill is due.
Compared with a credit card, the four-part structure is easier for me to understand because the repayment path is defined from the beginning. A card can provide broader flexibility, but it may encourage an open-ended balance and can involve interest depending on how it is managed. Deferit’s narrower purpose is a strength for a user who wants a specific bill divided rather than a general spending facility.
Compared with asking the bill provider for an extension or payment plan, the app may be more convenient when I want one consistent process for eligible bills. The provider’s own arrangement may still be better if it avoids an intermediary or is designed specifically around that account. I would compare the exact schedules and any applicable conditions rather than assuming one option is automatically superior.
Compared with an emergency fund, Deferit is a short-term cash-flow tool, not a reserve. Savings give me more independence and do not create installments, but they take time to build. I see the app as something that can help during a narrow gap while I work toward a stronger buffer, not as a replacement for that buffer.
What the current app details tell me
The app was released on October 28, 2021, and the current version is 3.0.6. It supports devices running Android 7.0 or later, which makes it accessible to many older Android phones as well as newer models. For iOS readers, the practical step is still to check the current device listing before installing, because compatibility can depend on the device and operating system in use.
The free price removes an obvious barrier to trying the service, but “free” should not be interpreted as “without financial responsibility.” The meaningful cost is the commitment created by the repayment schedule and the possibility of a missed or poorly timed installment. I would read each confirmation screen carefully and keep the schedule visible after setting up a plan.
Its strong rating and large install base make it easier for me to take the app seriously as an established finance tool, but popularity is not a personal affordability test. A highly rated service can still be the wrong choice for a user whose income does not line up with the repayment dates. My recommendation would always depend more on the budget than on the app’s audience size.
My verdict after weighing the convenience against the risk
Deferit is a focused solution to a specific problem: a bill is due now, while the money to cover it arrives in smaller amounts over time. When that is genuinely my situation, splitting the bill into four interest-free payments can be practical, understandable, and less stressful than missing the due date. The app’s strongest quality is that it turns an awkward timing problem into a schedule I can plan around.
Its limitation is equally clear. The schedule does not reduce what I ultimately owe, and repeated use can make a tight budget look healthier than it is. I would use it selectively, check every future payment, and avoid stacking arrangements simply because each individual installment seems small.
My recommendation is positive but conditional: Deferit is worth considering for disciplined users with predictable income and a temporary cash-flow gap. It is not the right answer for persistent overspending, uncertain income, or bills that are already unaffordable. Used as a carefully managed bridge, it can be helpful; used as a permanent way to stay ahead of expenses, it may only delay the harder financial decision.
FAQ
What is Deferit: Split Bills, Pay in 4?
Deferit is a bill-management and payment service designed to help eligible users handle certain expenses over time. Depending on availability, it may let you pay a bill through Deferit while repaying the service in scheduled installments, including a Pay in 4 option. The exact features, repayment terms, supported bills, and eligibility requirements can vary by country and user account, so reviewing the current in-app terms is important before signing up.
How does Deferit’s Pay in 4 feature work?
With Pay in 4, an eligible purchase or bill may be divided into four scheduled repayments rather than being paid entirely at once. The app normally displays the repayment dates and amounts before you confirm the transaction. Approval is not guaranteed, and the available limit can depend on factors such as account history, verification, and regional rules. Always check for applicable fees and make sure the repayment schedule fits your budget.
Can Deferit pay any bill or split every type of expense?
No. Deferit may support common household and personal bills, but not every biller, merchant, service category, or payment method is necessarily accepted. Availability can also differ according to your location, account status, and the provider’s current policies. Before relying on the app for an urgent payment, enter the bill details and confirm that the recipient is supported. The app should show any restrictions or unavailable categories during the process.
Are there fees, interest, or late-payment charges with Deferit?
The total cost depends on the product you use, your location, and the terms presented at checkout or during enrollment. Some services may involve membership charges, transaction fees, late fees, or other costs, while promotional conditions can change over time. Deferit should show the relevant pricing before you commit, but users should read the fee schedule and repayment agreement carefully. Missing a scheduled payment may also affect future access to the service.
Is Deferit safe, and what information is needed to use it?
Deferit may request personal, identity, contact, bank, or payment information to verify your account, assess eligibility, process bills, and collect repayments. As with any financial app, download it only from an official app store and review its privacy policy, permissions, and security information. Use a strong password and monitor your payment account. Remember that approval and access to features can change, and the service is not a substitute for maintaining a realistic budget.


