

Dave: Credit, Cash & Money App
Dave Operating LLCFinance
Scanned and Safe · Free
- Rating
- 4.7Out of 5
- Downloads
- 10.00M
- Android
- 9
Screenshots
Analysis by Appxis
When a bill lands just before payday, I want a clear choice: adjust my spending, move money from savings, or find a short-term bridge without turning a small gap into a bigger one. That’s the situation where I’d consider Dave - Fast Cash & Banking. It’s a free finance app from Dave Operating LLC, built around short-term cash help, early pay access, interest-earning options and ways to find work. I see it as a set of tools for managing a tight stretch, not as a substitute for a steady budget or an emergency fund.
Start with the gap, not the advance
Before opening Dave, I’d work out exactly what is due, when it must be paid and when my next income is expected. That small check matters: a cash advance can shift a timing problem, but it does not erase the bill. If the expense can wait or be handled by moving a planned purchase, that may be the simpler choice. If it cannot, the app’s short-term support may be relevant.
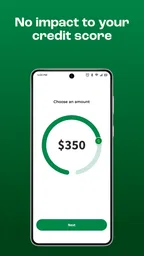
Dave’s store summary says eligible users can access up to $500, get paid early, earn interest and look for work, with no hidden fees. I would treat that headline as a menu of possible services rather than a promise that every option or the maximum amount will be available to every person. The useful first step is to decide which need I actually have: bridging a short gap, receiving income earlier, setting money aside, or finding additional work.
Getting started and choosing a route
So, I’ve been diving headfirst into the world of finance apps lately, and let me tell you, Dave - Fast Cash & Banking has been quite the discovery! If you’ve ever found yourself in a pinch, needing a bit of extra cash before your next paycheck, you might want to stick around for this one.
What’s the Buzz About?
Alright, let’s get into it. Dave isn’t just your average financial app. It’s like having a financial buddy who’s got your back when times are tough. The app is designed to help you avoid those pesky overdraft fees by giving you a cash advance on your upcoming paycheck. Yep, you heard it right—no more awkward moments at the checkout counter!
Setting It Up
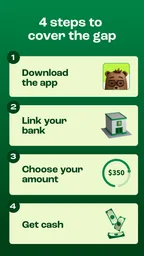
Getting started with Dave is pretty straightforward. You just download the app, sign up with your info, and link your bank account. The whole process is super intuitive, and I was pleasantly surprised at how quick it was. Plus, the app’s interface is clean and easy to navigate, which is always a plus in my book.
Features You’ll Love
One of the standout features of Dave is its budgeting tool. It’s like having a financial advisor in your pocket. The app analyzes your spending habits and helps you create a budget that’s realistic and easy to stick to. And if you’re someone who struggles with saving, Dave’s got a feature for that too. It helps you put away small amounts without even thinking about it.
More Stories While You Read
But wait, there’s more! Dave also offers a side hustle feature. You can find side gigs right through the app, which is perfect if you’re looking to make some extra cash on the side. It’s like having a mini-job board right in your hand.
Cash Advances Without the Hassle
Now, onto the cash advance feature, which is probably why most people download Dave in the first place. The app allows you to get a small cash advance to tide you over until your next payday. What’s cool is that there are no hidden fees or interest rates. You just tip what you think is fair, which is a refreshing change from the usual payday loan traps.
My Two Cents
So, what do I think about Dave? Honestly, it’s a lifesaver for those tight financial spots. The app is user-friendly, packed with useful features, and most importantly, it actually helps you manage your finances better. It’s not just about getting quick cash; it’s about fostering better financial habits.
However, like any app, it’s not perfect. The cash advance feature is great, but it’s limited to smaller amounts, which might not be enough for everyone. Also, while the tipping system is cool, it can add up if you’re not careful.
In conclusion, if you’re looking for a financial app that offers more than just basic banking services, Dave is definitely worth checking out. It’s got a little bit of everything, from cash advances to budgeting tools, making it a well-rounded choice for anyone looking to get a better grip on their finances.
What happens between requesting money and using it?
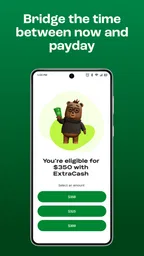
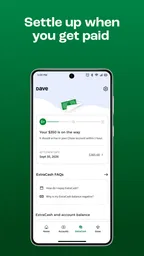
A shortfall usually involves more than tapping a button: I need to connect the account where income arrives, review what the app presents, decide whether the advance fits my repayment timing, then make sure the following payday still covers essentials. That sequence is the real test of a cash tool. I would not request money simply because an amount appears available; I’d compare the expected repayment with rent, utilities, food and transport due next.
For example, imagine a necessary car repair comes up a few days before payday. If delaying the repair risks missing work, a modest advance could help cover the timing gap. But I’d first check whether the repair shop accepts a later payment or whether another planned expense can move. After choosing an advance, I’d note the expected repayment date outside the app as well, so the deduction does not surprise me when the next paycheck arrives. The practical benefit is avoiding a more costly overdraft, not creating extra income.
Where the handoffs deserve attention
Dave is not operating in isolation: setting up an account involves providing information and connecting a bank account, while an advance depends on the relationship between the app, the linked account and incoming pay. I’d take a moment to verify that the account I connect is the one I actually use for income and regular bills. Linking an account that rarely receives deposits could make the whole workflow less useful, even if the app itself is easy to navigate.
The other handoff is from Dave back to my everyday money routine. Once funds arrive, I’d use them for the specific expense that justified the request and keep the repayment in mind when planning the next week. That sounds obvious, but it is an easy trap to treat a short-term advance as extra spending money. A quick note in a budget or calendar can make the cost in future cash flow visible before it becomes a second squeeze.
Dave has an average rating of 4.4 from around 567,000 ratings, with roughly 226,000 written reviews and over 10 million installs. Those figures suggest that many people have tried it, but popularity is not a guarantee that it will suit my banking habits or that I’ll qualify for every service. I’d judge it by whether the cash timing, account connection and repayment fit my own situation.
Choosing between Dave and the usual alternatives
Compared with a traditional payday loan, an advance in Dave may feel less intimidating because the app describes a no-hidden-fees approach and a voluntary tipping model. I would still look carefully at the amount I receive, the amount I must repay and the date the money leaves my account; “no hidden fees” does not make borrowing consequence-free. If I can use an interest-free option from a trusted source or negotiate a bill date, that may be a better fit than taking any advance.
Compared with a basic budgeting app, Dave brings short-term cash support and work-finding into the same financial setting, alongside the budgeting and saving tools described in the app. That combination may be convenient if I want to check spending and consider ways to improve cash flow in one place. A dedicated bank account or a savings-first tool may be preferable if my main goal is long-term planning, a wider range of banking services, or keeping borrowing out of my routine.
The work option is best viewed as a lead-finding aid, not as money already earned. I’d assess any opportunity on its own terms and avoid counting it toward an urgent bill until I know the work is suitable and the pay timing works for me. Likewise, an interest-earning option is more useful for money I can leave alone than for cash I expect to need immediately. Thinking through those distinctions helps me choose the right part of the app instead of expecting one feature to solve every financial problem.
Small habits that make the app more useful
One useful approach is to open Dave before a predictable tight period, not only when a payment is already overdue. Looking ahead gives me time to compare the expense with my payday and decide whether adjusting my budget, using savings or seeking an advance makes more sense. I’d also review the budget after an unusually expensive week, because a spending plan based on an ordinary month can be misleading when a one-off bill changes the picture.
For saving, I’d start with an amount small enough that it does not force me to borrow again for essentials. The appeal of setting aside little sums is that it can make saving feel manageable, but consistency matters more than choosing an ambitious target. If the next few weeks are already committed to bills, I would not treat saving as a reason to leave too little available for necessities.
The app is free to download, but I’d still read the terms shown for any service I choose and pay attention to optional tipping. A tip that feels minor in one moment can become meaningful if I rely on advances repeatedly. I’d decide deliberately rather than tapping through automatically, and I’d keep track of how often I need short-term help. Repeated use is a cue to revisit income, recurring bills or the timing of expenses, not simply a reason to request another advance.
Who is likely to benefit—and who may be better served elsewhere?
I can see Dave working well for someone with regular income who occasionally faces a mismatch between a bill date and payday, wants basic spending guidance, or is curious about finding extra work. It may also suit someone who prefers a single app for several cash-flow tasks rather than switching between separate services. The app is rated for Everyone, and its current version is 3.88.2; it supports devices running Android 9 or later. Dave was released on April 24, 2017, so it is an established app rather than a brand-new experiment.
I would skip the advance feature if repayment would leave me unable to cover essentials, if my income timing is unpredictable, or if I need a large loan for a major expense. A small short-term bridge is not the same as financing a long-term need. Someone who wants only a conventional bank account, does not want to connect an account, or prefers not to use advances may be better off with a bank’s own tools or a budgeting service focused solely on tracking and planning.
There is also a difference between convenience and control. Dave can put relevant options in front of me, but it cannot decide whether a purchase is necessary, whether a gig is worth pursuing or whether a repayment fits my next pay cycle. I still need to make those calls. If I want a tool that automatically solves a chronic shortfall, this is not the right expectation; the more useful role is helping me see choices and manage a temporary gap with care.
My practical recommendation
I’d treat Dave as a useful backup and cash-flow companion, not as my first line of defense every month. Its mix of advances, early-pay access, interest-earning options, budgeting, saving and work discovery gives it more range than a simple spending tracker. The trade-off is that each option still needs a personal check: confirm the timing, understand the repayment, and avoid relying on a possible advance or future gig before it is actually available.
If my finances were stable but occasionally awkward around payday, I’d be comfortable exploring it and using only the feature that solves the immediate problem. If money were short every month, I’d use the budgeting view to identify the pattern while also looking for a more durable change, rather than treating repeated advances as a plan. That distinction is what makes Dave potentially helpful: it can support a careful decision, but the best result comes from using it with a clear limit and a realistic view of the next paycheck.
Pros
- Instant cash advances available
- No hidden fees or interest charges
- User-friendly interface
- Automated budgeting features
- No credit check required
Cons
- Limited to small cash advances
- Requires access to bank account
- Not available in all regions
- Monthly membership fee
- Limited financial products offered
Dave: Credit, Cash & Money App FAQ
What is Dave and how does it work?
Dave is a financial app designed to help users manage their money efficiently by offering features such as budgeting tools, cash advances, and banking services. It aims to prevent overdraft fees and provide a financial cushion by allowing users to access small cash advances based on their anticipated earnings. The app simplifies financial management by linking to users' bank accounts and providing insights into spending habits.
Is Dave safe to use for banking and cash advances?
Yes, Dave is generally considered safe for banking and cash advances. The app uses encryption and other security measures to protect users' financial information. However, as with any financial service, users should exercise caution, regularly monitor their accounts, and read user reviews and privacy policies to ensure they are comfortable with the app's practices and security protocols.
How much does it cost to use Dave, and what are the fees involved?
Using Dave typically involves a monthly subscription fee, which is around $1. However, there are no interest charges on cash advances, unlike traditional payday loans. Users may also opt to pay a tip for the service, which is optional. It's important to review the fee structure within the app to understand any additional costs that may apply.
Can Dave help improve my financial health and budgeting skills?
Yes, Dave can assist in improving financial health and budgeting skills through its comprehensive tools. The app offers personalized budgeting advice and alerts to help users avoid overdrafts and manage their spending more effectively. Additionally, its predictive algorithms can help identify potential financial pitfalls and provide proactive solutions, making it a useful tool for those looking to enhance their financial literacy and stability.
What are the requirements to qualify for a cash advance with Dave?
To qualify for a cash advance with Dave, users typically need to have a steady income source, a linked checking account, and a history of consistent transactions. The app evaluates users' financial history and predicted earnings to determine eligibility. Meeting these requirements can make it easier to access the cash advance feature, which is intended to provide short-term financial relief.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Dave Operating LLC
- Package Name
- com.dave
- Version
- 4.9.1
- Android
- 9
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@dave.com, visit https://dave.com, or view the https://www.dave.com/privacy.