Común: Your money, your way

- 2.75K Reviews
- 4.8
- Downloads
- 500.00K
- 2.29.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple interface makes everyday money management easy.
- Supports clearer spending awareness through organized financial information.
- Useful for users who want more control over personal finances.
- Convenient access to money tools from a mobile device.
- Can help users make more informed budgeting decisions.
Cons
- Some features may depend on your country or account eligibility.
- Financial information may take time to update in the app.
- Requires sharing sensitive financial data to use its services.
- Not all users may find its money tools detailed enough.
- App performance and available features can vary by device.
Review of Común: Your money, your way Appxis
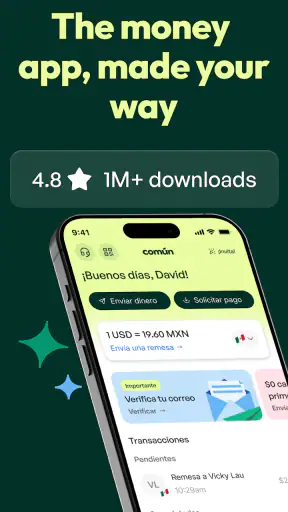
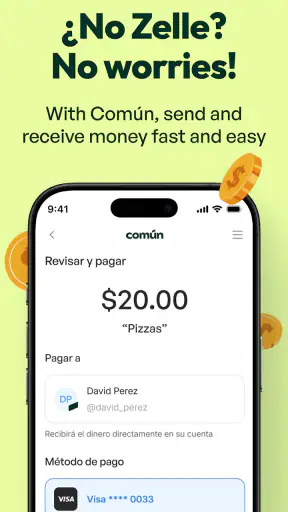
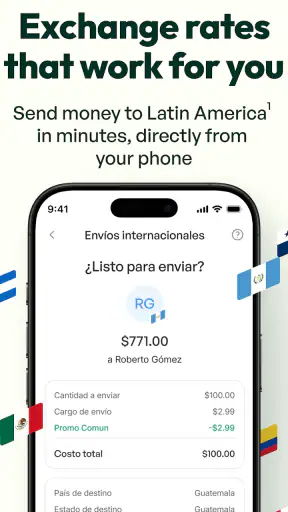
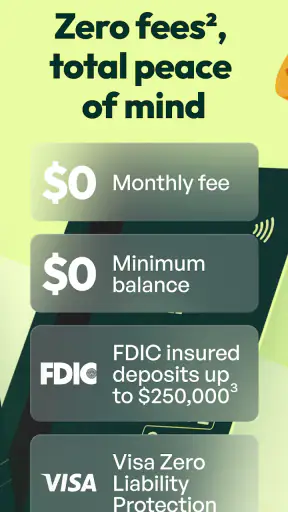
Money apps are easy to judge from a short description and much harder to judge after you start depending on one. I spent time looking at Común as a practical finance app rather than treating it as just another digital wallet. Its appeal is clear: it brings everyday payments, transfers to Latin America, and a Visa debit card into one place. The more important question is whether that combination matches the way you actually handle money.
Común is developed by Comun and is available free of charge for everyone. It has built a strong public reception, with an average rating of 4.8 from around 22 thousand ratings, and it has passed half a million installs. Those figures suggest that the idea connects with a sizeable audience, but they do not answer the personal questions that matter most: Will it simplify your routine? Is it a good fit for cross-border family support? And will moving away from your current bank or wallet create more work than it saves?
What I looked for before recommending it
I approached Común through four practical tests. First, I considered how naturally it could fit into ordinary spending. A finance app should reduce steps, not merely move familiar banking tasks onto a smaller screen. Second, I looked at its usefulness for sending money to Latin America, because that is the part that separates it from a basic spending wallet. Third, I considered the Visa debit card as a bridge between the app and places where mobile payments are not enough. Finally, I weighed the inconvenience of changing routines, especially for someone who already uses a bank account, a card, and a separate transfer service.
This way of judging the app is important because Común is not trying to be only one thing. It sits between a conventional bank account, a remittance tool, and a debit-card wallet. That can be convenient, but it also means the right comparison depends on your priorities. Someone who mainly wants domestic budgeting may value a different kind of app. Someone who regularly sends money to relatives in Latin America may care much more about the transfer workflow than about budgeting extras.
The current release is version 2.29.0 and requires Android 10 or later. On iOS, the broader question is less about a specific feature checklist and more about whether you want one app to become the starting point for several money tasks. I would make that decision based on your habits, not on the attraction of having a newer-looking interface.
Why the combined approach is useful
The strongest idea here is consolidation. Instead of opening one service to pay someone, another to send money abroad, and a third place to manage card spending, Común is designed around a single financial relationship. That does not automatically make every action better, but it can make the overall routine easier to remember and review.
I find this especially useful for people whose finances cross borders. If you pay friends locally and also support family in Latin America, separating those activities across unrelated services can create small but annoying problems: different login details, different balances, and different places to check whether a transaction went through. Having the activities connected gives the app a more coherent purpose than a wallet that only handles card purchases.
The Visa debit card adds another practical layer. A physical or card-based payment option matters when a merchant does not accept a phone-based payment method or when you simply prefer to use a card. It also gives the service a role in daily spending rather than restricting it to occasional transfers. In my view, that makes Común more interesting for regular use than an app that exists only for sending money.
There is also a psychological advantage to a focused money app. When the main tasks are paying people, sending money to Latin America, and using a debit card, the purpose is easier to understand. You are less likely to download it expecting a complete replacement for every financial product you own. That clarity helps, although it also means you should not assume that a convenient transfer-and-card combination covers every banking need.
A realistic way I would use it
Imagine a user who receives income in one country, pays rent and groceries locally, and sends money to a parent in Latin America near the end of the month. With a traditional setup, that person might use a bank card for purchases, a peer-to-peer payment app for friends, and a separate remittance provider for family transfers. Común offers a way to make the local payment and card side feel connected to the international transfer side.
The useful workflow is not simply “send everything through one app.” I would first decide how much money belongs to everyday spending and how much is intended for the family transfer. Keeping those purposes mentally separate makes it easier to notice mistakes before confirming a payment. I would also review recipient details carefully each time, particularly when sending to someone with a similar name or when switching between regular and occasional recipients.
That habit is one of the less obvious benefits of using a single place for related tasks: it encourages a repeatable routine. At the same time, it exposes a trade-off. If the app becomes your only place for these activities, an access problem or a forgotten login can affect more than one part of your financial life. I would keep essential account information organized and avoid treating convenience as a reason to abandon every backup option.
Where Común is likely to win
Común makes the most sense when international transfers are not a rare event. If you send money to Latin America regularly, the service has a clear reason to exist in your phone. The Visa debit card makes the relationship more useful between transfers, so you are not maintaining an app that you open only once every few weeks.
It can also suit someone who dislikes juggling separate financial services. The benefit is not just fewer app icons. It is the possibility of building one familiar sequence: open the app, check the available balance, pay someone or arrange a transfer, and use the associated card when needed. That simplicity is valuable for people who are comfortable with digital finance but do not want a complicated collection of specialized tools.
The free price is another reason to try it without making a large commitment. A free app lowers the barrier for someone who wants to test the workflow before changing their main habits. Still, “free” should not be interpreted as “every transaction is costless.” Financial services can involve conditions around particular actions, exchange, delivery, or card use, so I would always read the confirmation screen and any applicable terms before treating the app as a permanent replacement.
The age classification is Everyone, which makes the product broadly approachable from a content-rating perspective. That does not mean every financial decision is simple. Younger or inexperienced users still need to understand where money is going, verify recipients, and protect access to the account. The friendly presentation of a finance app should never replace careful checking.
Small details that affect daily use
One practical tip is to make the first few transactions deliberately boring. I would begin with a familiar payment or a small transfer workflow, then check how the confirmation, balance update, and recipient information are presented. This gives you a chance to learn the app’s rhythm without making your first experience depend on an urgent or high-value transaction.
A second useful habit is to separate “available to spend” from “available to send.” Even when an app presents money in one balance, your own plan should reserve the amount intended for a family transfer. This is particularly important when the debit card is convenient enough to encourage casual purchases. The card can make Común feel like everyday money, while the international transfer function may represent a more important obligation.
A third insight concerns recipient management. In any transfer tool, speed is helpful only after identity is clear. I would use recognizable names for contacts, pause before confirming, and avoid relying on memory when several relatives or friends have similar details. This is not a criticism unique to Común; it is the trade-off that comes with making person-to-person transfers easy.
Finally, I would treat updates as part of the experience rather than ignoring them. Version 2.29.0 shows that the app is actively maintained, but an update can still change the location of a control or the way a confirmation appears. After updating, I would take a moment to review the transfer and card screens before using them under pressure.
When a different category may fit better
Común is not automatically the best choice for someone who wants a full-service traditional bank. If your priority is a broad set of banking products, extensive account administration, or a long-established branch relationship, a conventional bank may remain the better foundation. Común’s appeal is focus and convenience, not the assumption that one app must replace every financial institution in your life.
A dedicated remittance service may also be preferable for a person whose only goal is sending money to Latin America. Such a service may feel more direct if you never plan to use a debit card or make local payments through the same account. In that case, Común’s broader design could be more than you need, and a specialist workflow may feel clearer.
On the other hand, someone who mainly wants expense tracking or envelope-style budgeting should compare it with a budgeting app rather than with another transfer service. The core attraction here is moving and spending money, not assuming that every planning feature found in a personal finance tracker will be present. Choosing the product category first prevents disappointment later.
People who rarely send money abroad may also find that the international angle does not justify changing their routine. If you already have a debit card you like and only make occasional payments to friends, adding another financial account can create extra balances to monitor. In that situation, the right question is not whether Común is good, but whether its particular combination solves a problem you actually have.
The real cost of switching
Because Común is free to download and use as an app, the largest switching cost is usually not the installation itself. It is the attention required to establish a new routine. You need to learn where to find the card information, how to start a payment, how to review a transfer, and how to recognize a completed transaction. That learning period is manageable, but it should not be ignored.
There is also an organizational cost. Moving money between services, deciding which account holds spending funds, and updating the places where friends or relatives expect to receive payments can take more effort than the app store page suggests. I would not close an existing account on the first day. I would run Común alongside the old arrangement long enough to understand whether it genuinely reduces friction.
Security habits are part of that transition. A new finance app means another account to protect, another set of notifications to understand, and another place where a lost phone or compromised credentials could matter. I would use a strong device lock, keep contact details current, and inspect every transfer before approving it. These are simple steps, but they are more valuable than choosing an app based only on appearance.
There is a further trade-off in consolidation. One app can make money management easier because fewer services are involved, but it can also make the account more central to your routine. I prefer a gradual switch: test local payments, test the card, then try an international transfer when you are not rushed. That approach gives you practical confidence without making an important family payment part of an experiment.
Who should install it
I would recommend Común to someone who wants a free finance app built around everyday payments, a Visa debit card, and transfers to Latin America. It is especially compelling for users who currently split those jobs between several services and would rather have a more unified workflow. The app’s strong rating and growing install base add reassurance, although my recommendation still depends on whether those tasks match your needs.
I would be more cautious with someone who wants an all-purpose bank replacement, advanced financial planning, or a service used only once in a while for international transfers. Those users may be happier with a bank, budgeting tool, or specialized remittance provider that concentrates on one job. Choosing Común simply because it is free could leave you with another account to maintain without solving a meaningful problem.
For families and friends who regularly move money across borders, the combination is more persuasive than any single feature. The debit card gives the app a daily role, while the transfer function gives it a clear reason to remain installed. The key is to use it intentionally: keep spending and transfer money distinct in your own plan, verify recipients, and test the process before an urgent payment is due.
My final view is positive, but measured. Común is strongest when convenience comes from combining local spending with transfers to Latin America, not when a user expects it to replace every financial service. The free entry point makes experimentation sensible, and the Visa debit card gives the app practical reach beyond occasional transfers. I would try it gradually, keep an eye on the terms shown for each transaction, and continue using it only if it reduces the number of steps in my real financial life.
After using it as a decision rather than an impulse, I see Común as a focused option for people whose money habits match its purpose. It is not the universal answer for banking, budgeting, or remittances, but it can be a genuinely useful middle ground for everyday payments and cross-border support. If that is the gap in your current setup, it deserves a careful trial; if not, staying with a tool that already fits may be the smarter choice.
FAQ
What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users organize, monitor, and manage their money from one place. Depending on the services available in your region, it may provide tools for tracking spending, managing accounts, planning finances, and accessing related financial products. Before downloading, check the official listing to confirm which features and services are currently supported in your country.
Is Común: Your money, your way safe to use?
Financial apps require users to share sensitive information, so security should be a priority. Común may use account authentication, encryption, and other protective measures to help safeguard personal and financial data, but no digital service is completely risk-free. Download the app only from an official store, use a strong password, enable available security options, and review the privacy policy before connecting accounts or submitting identification documents.
Does Común charge fees or require a subscription?
The cost of using Común can depend on the specific service, account type, transaction, or financial product you choose. Some features may be free, while others could include service charges, transfer fees, subscription costs, or third-party expenses. Carefully review the app’s pricing information and terms before signing up, and pay particular attention to recurring charges, withdrawal conditions, and fees that may vary by location.
Can I use Común to manage my bank accounts and transactions?
Común may offer tools that allow users to view financial information, organize transactions, or manage money through supported accounts and services. However, compatibility can vary by country, bank, and account type. Before relying on the app for everyday banking, confirm which institutions are supported, how account connections work, whether updates are automatic, and whether certain actions must still be completed through your bank.
What information do I need to create an account with Común?
Registration requirements may vary depending on your location and the features you want to use. You may be asked for an email address, phone number, password, identity details, and information needed for financial verification. Have accurate documents available if verification is required, and make sure the details you provide match your official records. Also review permissions carefully so you understand what data the app can access.


