

Chime® – Fee-Free Banking
ChimeFinance
Scanned and Safe · Free
- Rating
- 4.7Out of 5
- Downloads
- 10.00M
- Android
- 10
Screenshots
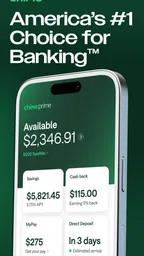
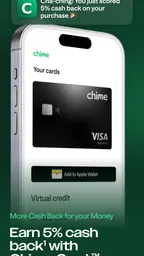
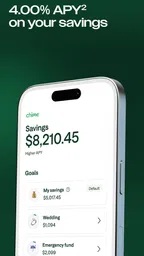
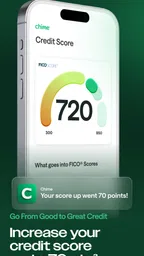
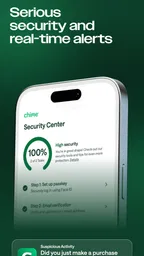
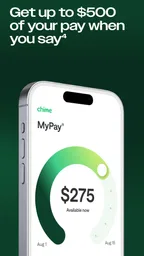
Analysis by Appxis
If you’re anything like me, balancing a checkbook is about as exciting as watching paint dry. Enter Chime – Mobile Banking, a game-changer in the world of digital finance that promises to make managing money not just easy, but dare I say, enjoyable. I’ve spent some quality time with this app, and here’s my no-holds-barred take on it.
Where banking apps can feel confusing
My first impression of Chime is that it puts routine money tasks on a phone-sized screen without asking you to learn a complicated system. That simplicity matters when you only want to check whether a payment has cleared or make sure there is enough in your account before heading out. Still, a clean layout cannot remove every point of friction: signing up, linking your everyday habits to a new account, and waiting for money to arrive are separate steps, and each can take patience.
Chime is a finance app from developer Chime. It is free to download, rated for Everyone, and has a 4.7 average from around 946,000 ratings. More than 10 million installs suggest it is a familiar choice for people looking to handle banking from a mobile device, though popularity alone does not tell you whether it suits your particular pay schedule or cash needs. The app’s current version is 5.301.0, and it requires Android 10 or later on Android devices.
The key question I would ask before switching is not simply whether an app is easy to use, but whether its way of working matches my financial routine. A person paid electronically who mostly checks balances and uses a card may value a different setup from someone who regularly deposits cash, needs in-person help, or wants several financial products under one roof. I would compare those needs before making Chime the center of my banking.
Getting Started with Chime
Signing up for Chime is as breezy as a Sunday morning. You’ll need to download the app from either the Google Play Store or the Apple App Store, and then it’s just a matter of entering some basic details. The app’s smooth interface guides you effortlessly through setting up your account. Within minutes, I was exploring what Chime had to offer.
Setup checks that save time later
Even a guided signup goes more smoothly when you have your personal details ready and enter them consistently. I would take a moment to check for typos before moving on; a small mistake in information can turn a simple setup into an avoidable verification delay. If a step does not go through, I would reread the on-screen instructions and check the app’s connection before repeatedly submitting the same form.
It also helps to decide what role the account will play before you start moving money. If you plan to use it for regular income and everyday spending, think through how you will handle bills already attached to another account and which payments need to stay there during the transition. Keeping the old arrangement in place until you have confirmed the new routine works is a sensible way to avoid a missed due date.
More Stories While You Read
For anyone comparing mobile banking options, the practical distinction is often convenience versus breadth of service. Chime is designed around banking through the app, while a traditional bank may be a better fit if you rely on branch visits or want face-to-face help. A familiar bank’s app may also make more sense if your finances already depend on accounts and services there. I would choose based on the tasks I do every month rather than on the appeal of a fresh interface.
Features That Make You Go "Wow"
One of the first things that stood out to me was the lack of fees. That’s right, folks—no monthly fees, no minimum balance requirements, and no foreign transaction fees. It’s like a breath of fresh air in a world where banks seem to nickel and dime you at every turn. Plus, with access to over 60,000 fee-free ATMs, you’re never far from your cash.
The automatic savings feature is another highlight. By rounding up your purchases to the nearest dollar and depositing the difference into your savings account, Chime makes saving money feel less like a chore and more like a natural part of spending. I also loved the early direct deposit feature, which lets you access your paycheck up to two days early. Who doesn’t want to get paid sooner?
Making the features fit real life
These tools are most useful when they support a routine rather than when they are treated as a shortcut to better budgeting. Rounding up can make saving feel almost invisible, but the small transfers still come from money that would otherwise remain available for spending. I would watch the account balance during the first few weeks and decide whether the automatic pace feels comfortable. If a week is unusually expensive, the priority should be keeping enough available for essentials.
Early access to a paycheck can help with timing, but I would not build a budget around assuming every deposit will arrive early. Treat the expected pay date as the reliable planning point and any earlier arrival as breathing room. That approach makes the feature a useful cushion instead of a reason to schedule a bill before the money is actually available.
Picture a familiar payday week: groceries are due, a utility bill is approaching, and you are trying to avoid dipping into money set aside for rent. Having your balance visible in the app can help you check the situation before making another purchase, while an earlier-arriving deposit may give you more flexibility when it lands. I would still keep a simple note of upcoming bills, because a banking app can show account activity without deciding which expense deserves priority.
The fee-free angle also deserves a little care. It can make ordinary account use easier to understand, but it should not be read as a promise that every outside service or unusual transaction is free. I would check the terms shown for the specific task I plan to do rather than assume that a broad no-monthly-fee approach covers every possible cost. That is a useful habit with any financial app, not a reason to dismiss this one.
Recovering when a workflow stalls
If a transfer, payment, or deposit does not appear when expected, I would first separate what I know from what I am guessing. Check the activity shown in the app, confirm that I am looking at the right account, and review any status or instructions attached to the transaction. Then I would allow for normal processing time rather than submitting the same action again immediately, since duplicate attempts can make it harder to tell what happened.
For a login or loading problem, I would try the basics before assuming there is a problem with the account: confirm the phone has a working connection, close and reopen the app, and make sure it is up to date. If the issue remains, use the app’s available support route and describe the exact step that failed, along with what the screen showed. Clear details are more useful than repeatedly tapping through the same stalled screen.
Security You Can Trust
When it comes to my hard-earned cash, security is non-negotiable. Thankfully, Chime gets this. The app uses robust security measures, including two-factor authentication, to keep your information safe. I found peace of mind in knowing that my data was protected by encryption and that I could instantly block my card from within the app if it was ever lost or stolen.
When the app is not the cause
A delayed deposit or a declined purchase can feel like an app failure, but the phone screen is only one part of a financial transaction. The timing of incoming money, the merchant’s payment process, a connection problem, or an incorrect detail can all affect what appears. I would check the transaction status and the information I entered before reinstalling the app or repeating a payment.
If a card is misplaced, the ability to block it from the app is a practical first response. I would use that control promptly, then look for the next steps presented in the app rather than assuming that blocking a card automatically resolves every concern about a missing card or a transaction I do not recognize. For anything that looks genuinely suspicious, contacting support through the appropriate channel is wiser than trying to diagnose it by guessing.
Security also depends on everyday habits. I would keep my phone’s screen lock enabled, avoid sharing sign-in codes, and be cautious about entering account details after following an unexpected message. Two-factor authentication adds a layer, but it does not make it safe to hand over credentials. A banking app can offer useful controls; the user still has to protect access to the device and account.
User Experience: Smooth Sailing
I’ve got to hand it to Chime; they’ve really nailed the user experience. The app is intuitive, with a clean design that makes navigation a breeze. Whether you’re checking your balance, transferring funds, or paying bills, everything is just a tap away. I never once felt overwhelmed or confused, which is more than I can say for some other banking apps I’ve tried.
Who will get the most from it
I see the strongest fit for someone comfortable managing money on a phone, who values a straightforward day-to-day account and wants to pay attention to fees and deposit timing. It can also suit a person who wants a small, consistent saving habit built into spending, provided they keep an eye on how those round-ups affect available cash. The benefit is less about complicated financial planning and more about making common account checks and routines easy to reach.
I would be more cautious if I needed a nearby branch, frequent in-person assistance, or a broad relationship with a traditional bank. Someone who handles a lot of cash should also think carefully about whether the available ways to get cash in and out match their actual routine. And if I wanted a single provider for a wide range of borrowing or investment needs, I would compare options rather than assume a mobile banking account covers that whole job.
Compared with a conventional bank app, Chime’s appeal is its mobile-first, fee-conscious approach and its emphasis on convenient access to routine banking. A traditional provider may offer a different mix of services and human support, which can matter more than a tidy interface when a complicated issue comes up. Compared with budgeting apps, Chime is not simply a place to categorize accounts from elsewhere: its value is tied to using its banking features directly. I would choose the kind of product that solves the problem I actually have, not just the one with the most appealing headline benefit.
Final Thoughts
To sum it all up, Chime – Mobile Banking is a solid option for anyone looking to simplify their financial life. It’s particularly great for those of us who appreciate convenience, transparency, and a no-fee approach to banking. Sure, it doesn’t have all the bells and whistles of a traditional bank, like in-branch services or loans, but what it lacks in extras, it more than makes up for in ease of use and peace of mind.
If you’re ready to ditch the fees and embrace a more seamless way to manage your money, give Chime a try. You might just find that banking doesn’t have to be a necessary evil—it can actually be a pleasant part of your everyday routine.
My practical recommendation is to start with one clear purpose: checking everyday spending, receiving regular income, or building a modest saving habit. Learn how deposits and payments behave in your own routine before moving every bill or relying on early access to funds. That gives you a fair test without making a new account responsible for everything on day one.
Overall, I find Chime – Mobile Banking most convincing for people who want a simple mobile-first way to handle ordinary banking and are happy to manage the details themselves. Its convenience is real, but it works best when paired with sensible planning and realistic expectations about timing and support. If those trade-offs match how you handle money, it is worth considering; if not, a bank with branches or a broader service lineup may be the more comfortable choice.
Pros
- No monthly fees or minimum balance requirements.
- Instant notifications for transactions.
- Fee-free overdraft up to $200.
- Access to 60
- 000+ free ATMs.
- Automatic savings features.
Cons
- No physical branches available.
- Cash deposit fees at certain locations.
- Limited customer service availability.
- No joint account options.
- Requires smartphone for full functionality.
Chime® – Fee-Free Banking FAQ
What features does Chime – Mobile Banking offer?
Chime Mobile Banking offers a variety of features designed to help users manage their finances effectively. These include a spending account, savings account, and the ability to receive paychecks up to two days early with direct deposit. Additionally, Chime provides a fee-free overdraft service, automatic savings options, and a user-friendly mobile app interface for managing all transactions.
Is Chime – Mobile Banking safe to use?
Yes, Chime is a safe option for mobile banking. It employs advanced security measures such as two-factor authentication, encryption, and account notifications to protect user information. Chime is insured by the FDIC up to the standard maximum limit through its partner banks, ensuring that your money is protected.
Are there any fees associated with using Chime – Mobile Banking?
Chime is known for its fee-free banking services. Users can enjoy banking without monthly fees, minimum balance requirements, or overdraft fees. However, there may be fees for using out-of-network ATMs or certain other third-party fees. It's advisable to review Chime's fee schedule for detailed information.
How do I deposit money into my Chime account?
Depositing money into your Chime account is simple and convenient. Users can set up direct deposits with their employers, deposit checks via the mobile app using mobile check deposit, or transfer funds from an external bank account. Additionally, cash deposits can be made at over 90,000 retail locations nationwide.
What should I do if I encounter an issue with my Chime account?
If you experience any issues with your Chime account, customer support is readily available to assist you. Users can contact Chime support through the mobile app, by email, or via phone. Chime also offers a comprehensive help center on their website with answers to frequently asked questions and troubleshooting tips.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- Chime
- Package Name
- com.onedebit.chime
- Version
- 5.332.0
- Android
- 10
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@chime.com, visit https://www.chime.com/, or view the https://www.chime.com/privacy.