Cashli: Cash Advance & Rewards

- 2.78K Reviews
- 4.1
- Downloads
- 100.00K
- 1.0.19
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast application process with clear eligibility information.
- Rewards can provide extra value beyond the cash advance feature.
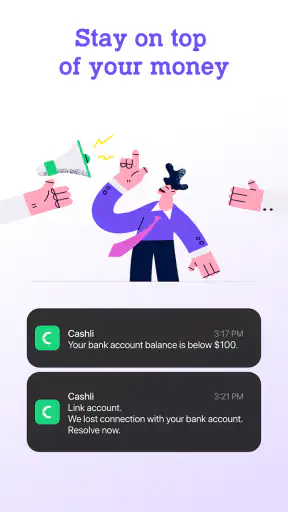
- Useful repayment reminders help users avoid missed due dates.
- Simple interface makes account details easy to review.
- May offer financial support without requiring a traditional bank visit.
Cons
- Cash advances may include fees or other costs that reduce their value.
- Availability and terms can vary by state
- profile
- or account history.
- Repayment deadlines may arrive quickly after receiving an advance.
- Rewards may require specific actions and have limited redemption options.
- Late repayment could lead to additional charges or account restrictions.
Review of Cashli: Cash Advance & Rewards Appxis
When money feels tight between paydays, Cashli: Cash Advance & Rewards presents itself as a finance app built around short-term access to cash. I approached it less like a shopping app and more like a tool that deserves careful attention, because anything involving personal finances should be judged by its controls and choices, not only by how quickly it sounds useful. After looking at the app’s role, presentation, and practical fit, my view is cautiously positive for a narrow situation: it may be worth exploring when a small, temporary gap needs attention, but it should not become a substitute for a proper budget or a dependable emergency fund.
Cashli is free to install, is aimed at everyone from an age-rating perspective, and comes from Cashli Funds. It belongs firmly in the finance category rather than the general rewards space, even though rewards are part of its identity. That distinction matters. A rewards app can usually be treated as optional entertainment or a way to collect small benefits; a cash-advance service can influence a user’s next financial decision. I would therefore install it with the same care I use for any app that may ask for identity, income, banking, or repayment-related information.
What the app is really useful for
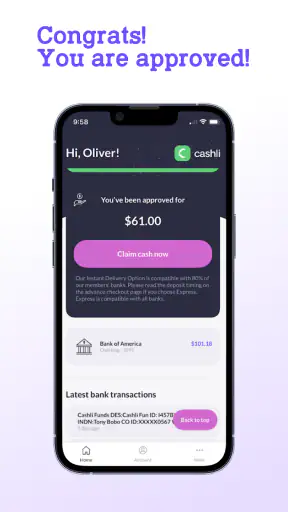
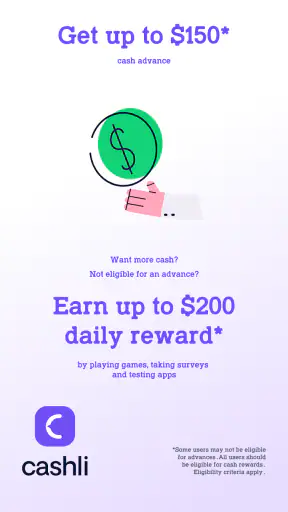
The clearest use case is a short-lived cash-flow problem: a necessary purchase arrives before income does, and waiting would create a more serious inconvenience. Think of a household that needs groceries, transport, or a basic bill covered for a few days. In that situation, the app’s promise of access to up to 150 dollars may sound relevant. The important word is “up to.” I would not plan a payment around the maximum before completing the app’s own process and seeing what is actually available to me.
That makes Cashli different from a conventional budgeting app. A budgeting tool helps me understand where money is going and decide what to change. Cashli is oriented toward immediate liquidity, with rewards included as an additional reason to engage. Those purposes can coexist, but they should not be confused. Rewards may make the app feel more active or useful between cash needs, while the advance side is the part that deserves the most disciplined examination.
I also would not treat it as a replacement for a bank account, a credit union relationship, or a regulated personal loan chosen after comparing terms. Those alternatives may offer broader account services, clearer long-term planning tools, or more predictable borrowing arrangements. Cashli’s appeal is convenience and immediacy, not comprehensive financial management. If I needed help restructuring debt, comparing annual costs, or planning several months of expenses, I would look elsewhere first.
Why trust needs to be earned here
The app has reached more than 100 thousand installs and carries a 4.1 average from roughly 4.9 thousand ratings, with about 2.8 thousand written reviews. Those figures suggest that it has attracted a meaningful audience and that many users found enough value to rate it. They do not, by themselves, prove that the experience will suit every financial situation. A rating can describe ease of use, speed, rewards, or general satisfaction without answering the questions I care about most before sharing sensitive information.
For me, trust starts with the screen in front of me. I want to know why a permission or piece of information is being requested, whether I can decline it, and what happens if I do. I also want account controls that are easy to find rather than buried behind unrelated menus. A finance app can look polished and still leave users uncertain about how to change their details, stop notifications, or close an account. Those are not minor conveniences; they determine how much control I retain after signing up.
Cashli’s current version is 1.0.19, and it supports devices running Android 8.0 or later. That makes compatibility fairly broad for many Android users, although anyone using an older phone should check the system requirement before spending time on registration. I would also keep the app updated through the official app store, since finance-related software should not be run casually from unknown download sources.
Controls I would check before applying
My first practical step would be to open the account and inspect the registration flow without rushing into an advance request. I would read each permission prompt separately and decline anything that does not make sense for the task. If the app asks for access that appears unrelated to receiving funds or managing the account, I would pause and look for an explanation before continuing. This is a simple habit, but it prevents the urgency of needing money from making me approve everything automatically.
I would then look for the account area, support route, notification settings, and any option connected with personal information. A good user experience should make it possible to review what I entered and correct mistakes. I would also check whether the app clearly shows the status of a request, any repayment expectation, and the next action required from me. If those details are scattered across several screens, I would take screenshots for my own records before confirming anything.
One useful workflow is to separate exploration from commitment. I can install the app, review the available controls, and understand the process before deciding whether to request money. That reduces the chance of accepting something simply because I have already invested time in the setup. It also gives me a chance to compare the app’s final terms and timing with another option, instead of comparing only its attractive opening message with the less exciting details elsewhere.
I would pay particular attention to whether the app gives me a clear way to stop using optional rewards or promotional communication. Rewards can be appealing, but they should not blur the difference between a benefit and a financial obligation. If I only need a small advance, I would avoid taking extra actions that do not directly support that goal. Keeping the account simple makes later review easier and limits the amount of activity I need to monitor.
Sensitive moments deserve slower decisions
The most data-sensitive moment is the initial application. A cash-related service may need information to determine eligibility or deliver funds, but I should still understand each request before submitting it. I would avoid entering details while connected to an unfamiliar public network, and I would use a strong, unique password if the app requires one. I would never share a verification code with another person claiming to represent support.
The next sensitive moment is linking or confirming a payment destination. I would double-check every account or card detail and make sure the destination belongs to me. A rushed typo can create a difficult support problem, especially when the user is already waiting for money. Before confirming, I would review the amount, destination, and any timing information shown on screen. If the final review is unclear, I would stop rather than assume the system will correct it automatically.
Notifications are another overlooked part of privacy. On a shared lock screen, a message about an advance or account activity could reveal more than I want others to see. I would review Android’s notification preview settings and limit sensitive previews if necessary. This is not a special Cashli feature; it is a user-side control that helps protect financial information regardless of the app being used.
I would also be careful with the rewards side. If a reward requires opening an offer, completing an action, or sharing information with another service, I would read what that action involves before accepting it. The attractive part of a reward is usually obvious, while the data or subscription implications may be less prominent. My rule would be straightforward: if I cannot explain what I am agreeing to in one sentence, I do not proceed until I understand it.
How much control does the user have?
User agency is strongest when the app lets me make an informed choice at every stage. I want to decide whether to apply, whether to participate in rewards, which notifications to receive, and whether to continue using the account. I would not regard a fast path as genuinely user-friendly if it hides the meaningful choices behind a single prominent button.
In everyday use, I would keep my own record of the request date, amount, expected repayment or settlement details, and any confirmation screen. That record is useful even when an app is working normally. It gives me something to compare against later notifications and helps me identify a misunderstanding early. I would also set a calendar reminder for the relevant date rather than relying only on push notifications, particularly if the advance is connected to my next income cycle.
Another practical tip is to decide the repayment source before requesting funds. If the money will come from the next paycheck, I would write down which bills and essentials must still be covered from that paycheck. A small advance can solve today’s problem while creating a larger gap later if I do not account for that reduction. Cashli may help with timing, but it cannot make an unaffordable budget affordable. That is the central trade-off I would keep visible.
I would also consider what happens if I change my mind. Before using the service, I would look for cancellation guidance, account closure instructions, and a support channel inside the app. If I could not find those controls easily, that would lower my confidence. The ability to leave a financial app cleanly is part of trust, even if I never need to use it.
Where it fits beside familiar alternatives
Compared with borrowing from a friend or family member, Cashli may offer a more structured digital process, but it also places the user inside an app-based financial relationship that must be understood carefully. A personal loan from a bank or credit union may be slower and involve more formal assessment, yet it can be more appropriate for a larger or longer-term need. A credit card may already be available, but its costs and repayment pattern can make it a poor choice for someone who is already carrying a balance.
Compared with an earned-wage or payroll-linked service, the key question is how closely the app fits my income and account situation. I would not assume that every cash-advance product works the same way simply because the wording sounds similar. I would compare the actual amount available, timing, repayment expectations, optional activities, and account controls before choosing. A budgeting app remains the better alternative when the problem is recurring overspending rather than a single timing mismatch.
Cashli’s rewards angle may make it more engaging than a plain advance tool, but that is not automatically an advantage. If rewards encourage me to spend more time opening offers or supplying extra information, the convenience may come with a privacy or attention cost. I would use that part only when the value is clear and the action is genuinely optional. For me, the cash function should stand on its own; rewards should never be the reason I borrow.
Who should use it, and who should skip it
I can see Cashli working best for an adult who understands the amount needed, has a realistic plan for the next income cycle, and is comfortable reviewing permissions and account choices carefully. It may also suit someone who wants to investigate a short-term option from a phone rather than visit a branch or make several calls. The free installation lowers the barrier to trying the app, but it should not lower the standard I apply to financial decisions.
I would skip it if I already struggle to cover regular essentials, if I am considering repeated advances, or if I need a larger loan with predictable long-term repayment. I would also avoid it if the app’s requested information or agreement screens were unclear to me. A financial product is not a good fit merely because it is available quickly. If using it would force me to delay rent, utilities, food, or another essential obligation later, the short-term relief would not be worth it.
People who mainly want coupons, points, or casual rewards may find that a dedicated rewards app is a better match. Likewise, users seeking detailed spending categories, savings goals, bill calendars, or debt payoff planning should choose a dedicated money-management tool. Cashli’s identity is narrower, and judging it against those broader apps would be unfair. The right question is whether its short-term cash purpose matches my immediate need without weakening my control over the rest of my finances.
My cautious verdict after weighing the trade-offs
Cashli: Cash Advance & Rewards has a clear practical appeal: it brings a short-term cash option and rewards into one finance app, and its established presence on Android gives interested users a straightforward place to begin evaluating it. I like the idea of separating the browsing stage from the borrowing decision, and I would recommend that approach to anyone considering it. The app is free to install, but the real cost of any financial service is determined by its terms, timing, and effect on the user’s next budget, not by the download price.
My recommendation is therefore measured rather than enthusiastic. I would consider it for a specific, temporary gap only after reviewing every request, confirmation, and account control. I would keep records, limit optional permissions and notifications, and avoid treating rewards as a reason to borrow. If the app makes those choices clear and the resulting obligation fits comfortably into my plan, it may be useful. If the details feel rushed or difficult to control, I would choose a more transparent alternative.
In short, the app may help with timing, but it cannot replace financial breathing room. Its 4.1 average and growing user base make it worth examining, not blindly trusting. I would install it only with a defined purpose, use the smallest amount that solves that purpose, and leave it alone when the underlying problem is ongoing income or debt pressure. That cautious boundary is what makes a cash-advance tool potentially helpful instead of turning a temporary fix into another monthly burden.
FAQ
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app designed to help eligible users access potential cash advances while also offering rewards-related features. After creating an account, you may be asked to provide personal, employment, income, and banking information so the app can evaluate eligibility. Available amounts, fees, repayment terms, and other conditions can vary by user and should be reviewed carefully before accepting any offer.
Is Cashli a lender, and will everyone qualify for a cash advance?
Cashli may operate as a platform that connects users with financial service providers rather than acting as the direct lender in every transaction. Approval is not guaranteed, and eligibility can depend on factors such as income, employment, account activity, location, and information supplied during registration. Before downloading or accepting an offer, check the app’s disclosures to understand which company provides the funds and makes the final decision.
Are there fees, interest charges, or repayment requirements in Cashli?
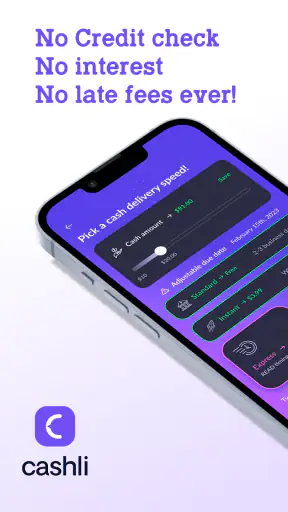
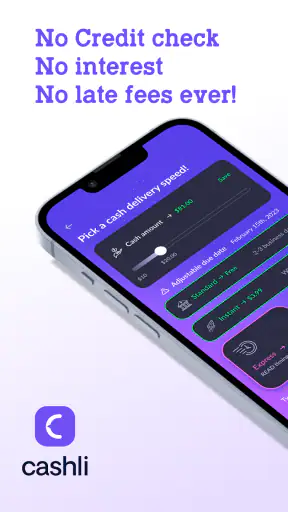
A cash advance is not necessarily free, even when an app advertises quick access to money. Cashli may present service fees, optional expedited-transfer charges, subscription costs, or other expenses depending on the product and your eligibility. Repayment dates and automatic debit arrangements may also apply. Always read the complete offer, including the annual percentage rate or equivalent cost where applicable, before confirming a transaction.
What personal and financial information does Cashli require?
To provide account services or assess eligibility, Cashli may request information such as your name, contact details, identity documents, employment details, income, bank-account information, and transaction data. Some permissions may be optional, while others could be necessary for specific features. Before granting access, review the privacy policy and permission settings, and avoid submitting sensitive information through unofficial websites or modified versions of the app.
Is Cashli: Cash Advance & Rewards safe and available on Android or iOS?
Cashli’s safety depends on using the official application from a trusted store, keeping your device updated, and protecting your login credentials. Availability, features, advance limits, and rewards can differ by country, state, or operating-system version. Before installing, verify the developer name, ratings, recent reviews, privacy disclosures, and requested permissions. Never assume that rewards or cash advances are guaranteed simply because they appear in promotional material.


