Cash Advance: Get 250 Fast

- 983.00 Reviews
- 4.7
- Downloads
- 100.00K
- 1.2.2
- Version
Screenshots
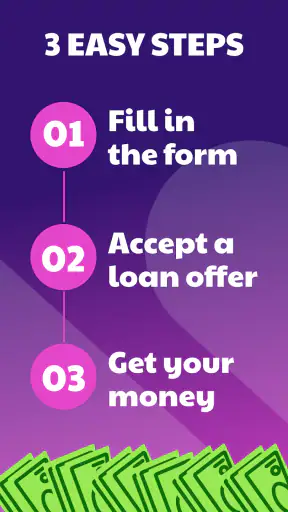
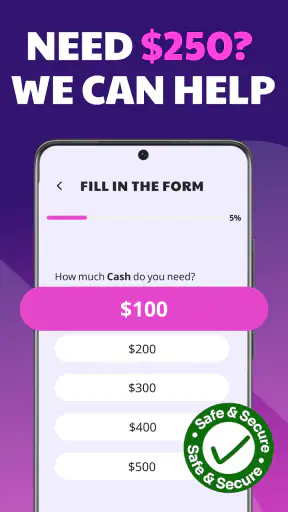
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Fast application process with clear eligibility information.
- Funds can help cover unexpected expenses between paychecks.
- No need to visit a physical branch to request an advance.
- Repayment dates and amounts are shown before confirmation.
- Useful budgeting tools may help track upcoming cash needs.
Cons
- Approval and advance amounts depend on eligibility and account history.
- Express funding may include additional fees.
- Repayment can reduce the balance available for your next paycheck.
- Not available in every state or for all employment situations.
- Late repayment may lead to extra charges or account restrictions.
Review of Cash Advance: Get 250 Fast Appxis
Cash Advance: Get 250 Fast is a finance app aimed at people looking for a short-term cash advance through a straightforward mobile process. I approached it as I would any borrowing app: not as a promise of easy money, but as a tool that needs careful checking before it becomes part of a real budget. Its focus is narrow, which can be useful when you need to understand one particular type of service quickly, but it also means the app deserves more scrutiny than an ordinary budgeting or expense-tracking tool.
The app is free to install and is listed for everyone, with a minimum operating-system requirement of Android 7.0. It comes from KOMPANIIA LORENS PP and has reached over one hundred thousand installs, with a 4.7 average from around twenty-five thousand ratings. Those figures suggest that many people have been willing to try it, but popularity should not be confused with affordability. A borrowing product has to be judged by the complete repayment obligation, not by its download count or store score.
How the app fits into a real borrowing decision
At its core, this is a cash advance app, not a general-purpose banking replacement. I would open it when I was considering a short-term borrowing request and wanted to go through the steps from a phone. That makes it different from a spending tracker, a savings app, or a traditional bank application. Its usefulness depends on whether the available offer, eligibility process, and repayment terms fit the situation in front of me.
The wording around the app emphasizes simple steps and no subscription fees. That is an important distinction: free access to the app is not the same thing as free borrowing. I would not treat the absence of a subscription charge as evidence that a cash advance has no other costs. Before accepting anything, I would read every displayed figure related to repayment, timing, fees, and the total amount due. If those details are not clear enough to explain to another person, I would stop before submitting a request.
This is the first practical lesson I took from using a finance product with this purpose: the app can make the application path more convenient, but convenience can also make an expensive decision feel routine. A few taps may be easier than visiting a branch, yet the financial responsibility remains exactly as serious. I would use the app to inspect an offer, not to let the app decide whether borrowing is sensible.
What “free” means here
The installation and access cost is free, and there is no subscription fee presented as part of the app’s basic positioning. That gives it an advantage over services that charge simply for keeping an account active. Still, the meaningful question is not whether I paid to download it. The meaningful question is what I would repay if I accepted a cash advance.
For that reason, I would separate three ideas whenever I evaluate it. First is the free app access. Second is the value of having a mobile route to a potential advance. Third is the cost of the actual financial agreement, which must be assessed from the terms shown during the process. These are not interchangeable. A free app can still lead to a borrowing decision that is poor value if the repayment amount is difficult to manage.
I would also avoid assuming that the name indicates a guaranteed amount or guaranteed approval. A title referring to a fast advance may sound definite, but a responsible user should wait for the actual eligibility result and the full terms. The sensible workflow is to enter only information I am comfortable providing, review the result slowly, and compare the total repayment with alternatives before agreeing.
What I found useful in the mobile format
The strongest practical benefit is concentration. Instead of searching across unrelated financial pages, I can focus on the specific question of whether a short-term advance is appropriate. For someone facing an urgent bill, that focused route may feel less intimidating than a broad banking app filled with savings, cards, investments, and account-management tools.
I also like the idea of reviewing a borrowing decision away from a sales counter. On a phone, I can pause, write down the amount I would receive, and compare it with the amount I would need to repay. That pause matters. My tip is to take a screenshot or note of the final terms for personal records before leaving the decision screen, provided the app allows that kind of normal device use. I would never rely on memory after a rushed application.
Another useful habit is to calculate the repayment against the next two pay cycles rather than asking only whether the money is needed today. An advance that solves a small immediate gap can create a larger gap later. The app may streamline the request, but it cannot replace a cash-flow plan. I would list rent, utilities, food, transport, and existing repayments first, then see whether the proposed repayment still leaves room for essentials.
Where it differs from familiar alternatives
A traditional bank may offer more established account tools and a broader view of income and spending, while a credit union or employer-based option may suit someone who can wait for a more personal review. A budgeting app, meanwhile, may help prevent the emergency by showing where money is going, even though it does not provide an advance. Cash Advance: Get 250 Fast sits in a different place: it is built around accessing a potential short-term borrowing route rather than improving the whole financial picture.
That narrow focus is both its appeal and its limitation. If I already know the exact amount I need and have checked how repayment will fit my budget, a focused advance app can be more direct than a full bank platform. If I am repeatedly short before payday, however, I would prefer a budgeting conversation, a savings plan, or a lower-cost borrowing option. Repeated advances can hide an income-and-expenses problem instead of solving it.
I would also compare the complete cost with any available alternative before proceeding. That could include asking a bank about an existing facility, checking whether an employer offers an advance, or discussing a payment arrangement directly with the bill provider. The right comparison is not “which app is fastest?” It is “which option leaves me with the least damaging repayment burden while still solving the need?”
Everyday situation: an unexpected bill before payday
Imagine I receive an essential household bill several days before my usual income arrives. I could use the app to explore whether a cash advance is available, but I would begin by confirming the bill’s deadline and asking the provider whether a short extension or payment arrangement is possible. If that route worked, it might be better than borrowing at all.
If borrowing remained necessary, I would enter the app with a fixed maximum amount rather than requesting whatever limit appeared attractive. I would compare the amount received with the full repayment and place the repayment date on my calendar. I would also check whether the repayment would collide with rent, food, or another scheduled obligation. This is a more disciplined use of the app than opening it in a panic and accepting the first apparent solution.
Afterward, I would treat the advance as a one-off bridge, not as extra income. If the same situation happened again the following month, that would be a sign to stop using short-term credit and examine the underlying budget. The app may be helpful for one urgent gap, but it should not become the default part of a monthly spending cycle.
Important friction and tradeoffs
The main tradeoff is speed versus reflection. A mobile application can reduce the effort involved in exploring an advance, but that same ease can encourage an impulsive decision. I would deliberately slow down at the point where money becomes a commitment. Reading the final agreement is more important than finishing the application quickly.
Another limitation is that a high store rating cannot tell me whether a particular offer is suitable for my circumstances. Ratings describe broad user reactions to the app, not the affordability of an individual repayment schedule. I would use the 4.7 average as a sign that the app has attracted positive engagement, but I would not use it as a substitute for reading the financial terms.
The app’s focused purpose may also frustrate users who expect a complete personal-finance dashboard. Someone looking for bill reminders, detailed spending categories, long-term savings goals, or broad account management should look elsewhere. This is not the tool I would choose to build a full financial plan. Its value is tied to the specific cash-advance journey.
Privacy and eligibility also deserve a deliberate pause. Any finance app may require personal information as part of an application, so I would review the screens carefully and provide only what is necessary for the process. I would avoid installing it on a device I do not control, and I would keep my phone protected with a screen lock. These are simple precautions, but they matter more when an app is connected to borrowing and identity details.
One practical tip is to distinguish an application from an acceptance. Starting the process does not mean I should assume money will arrive, and seeing an offer does not mean I have to take it. I would keep a backup plan for the bill rather than spending money in advance based on an expected advance. That small change in mindset prevents the app from becoming part of a chain of assumptions.
Who is likely to get real value
I see the most value for an adult who needs to investigate a short-term advance, has a reliable repayment plan, and wants a mobile-first process. The free installation lowers the barrier to exploring the service, and the straightforward focus may be easier to navigate than a large financial platform. Someone who has already compared alternatives can use it as one option in a broader decision.
It may also suit a person who prefers to review financial information privately and at their own pace. Rather than making a rushed verbal decision, I can pause over the figures, check my calendar, and discuss the commitment with someone I trust. That is the responsible way I would use a finance app: as an information and application tool, not as encouragement to borrow.
I would be much more cautious if my income is irregular, if I already have several repayments, or if I am using one advance to cover another. In those situations, a short-term product may increase pressure instead of relieving it. A free app is not automatically the right financial choice for someone who cannot comfortably absorb the repayment.
I would also skip it if my need is not urgent or if I am simply looking for general money-management help. A budgeting application, a conversation with a bank, or direct negotiation with a service provider could be more useful. The best alternative depends on the problem: borrowing is not the only answer to a timing mismatch, and it is rarely the best answer to a persistent budget deficit.
Version, audience, and practical expectations
The current version is 1.2.2, and the listed age classification is Everyone. Those details make the app broadly approachable from an installation perspective, but they do not remove the need for adult financial judgment. I would still expect the person making the borrowing decision to understand the repayment obligation fully, regardless of how simple the interface feels.
Because the app supports a financial decision rather than casual entertainment, I would keep my expectations realistic. I would not install it expecting guaranteed approval, instant access in every situation, or a replacement for a bank account. I would install it to examine a possible cash advance and then decide whether the terms make sense. That distinction is essential to getting genuine value from it.
I would also keep the app updated through the normal platform process and check that the version on my device matches the current listing before beginning an application. That is not a reason to borrow, but it is a sensible maintenance step for any finance-related tool. More importantly, I would verify the final terms every time rather than assuming a previous experience applies to a new request.
My buying decision: free to try, not automatically cheap to use
My verdict is cautious but fair. Cash Advance: Get 250 Fast offers free access to a focused way of exploring a short-term advance, and its strong user rating and substantial install base show that it has found an audience. The developer, KOMPANIIA LORENS PP, has positioned it around a simple mobile borrowing journey rather than a broad finance suite. For a carefully prepared user with a clear repayment plan, that focus can be useful.
However, I would not recommend accepting an advance merely because the app is easy to install or because there is no subscription fee. The real value depends on the complete repayment obligation, not the download price. I would compare the offer with a bank, credit union, employer option, payment arrangement, or personal budget before committing. If the repayment would force me to delay essentials or borrow again, I would skip it.
So, would I recommend trying it? Yes, as a tool for investigating a specific short-term need and comparing the result with safer alternatives. Would I recommend treating it as a regular payday solution? No. I would use it only when the need is genuine, the amount is limited, the terms are clear, and the repayment is already accounted for. Used with that discipline, the app can be convenient. Used as a substitute for a sustainable budget, it is the wrong choice.
FAQ
What is Cash Advance: Get 250 Fast, and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help users explore short-term cash advance options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. The app may connect you with third-party lenders or financial providers, and approval, fees, repayment terms, and funding speed can vary.
Can everyone receive a cash advance of up to $250?
No. The advertised amount is not a guarantee that every applicant will receive $250. Eligibility normally depends on factors such as age, residency, income, employment, an active bank account, and the information submitted during the application. The app or its lending partners may approve a smaller amount, offer different terms, or decline the request. Always review the final offer before accepting it.
How quickly can the money arrive after approval?
The app promotes fast access, but the actual delivery time depends on the review process, lender decisions, banking hours, and the receiving financial institution. Some approved requests may be deposited quickly, while others can take longer, particularly around weekends or holidays. Before submitting an application, check whether express-transfer charges apply and confirm the expected arrival date shown in the final agreement.
What fees, interest, or repayment obligations should users check?
A cash advance is not free money, and the total cost can differ significantly depending on the provider and the selected terms. Carefully look for origination fees, subscription charges, expedited-funding fees, interest, finance charges, late-payment penalties, and automatic repayment rules. Read the complete disclosure and repayment schedule, calculate the total amount due, and avoid accepting an offer you cannot comfortably repay.
Is Cash Advance: Get 250 Fast safe to use, and what information does it request?
Because financial applications handle sensitive data, users should review the app’s privacy policy, permissions, developer information, and lender disclosures before continuing. The application may request identity, contact, income, employment, and bank-account details to process an application. Download it only from an official app store, use a secure connection, never share passwords or verification codes, and understand how your information may be shared with partners.


