Budget App — PocketGuard

- 1.16K Reviews
- 4.5
- Downloads
- 100.00K
- 5.19.3
- Version
Screenshots
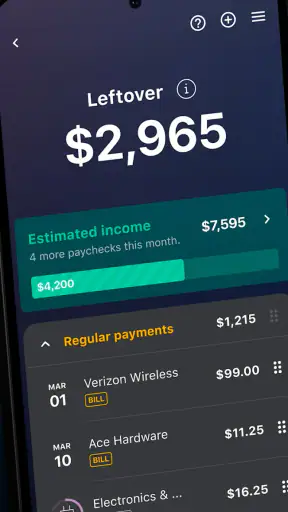
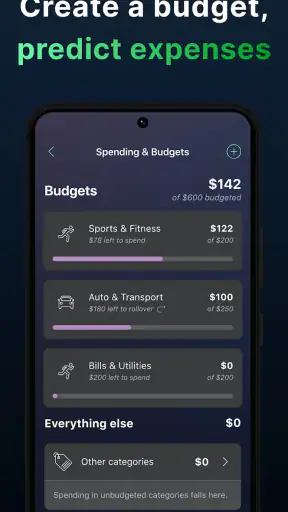
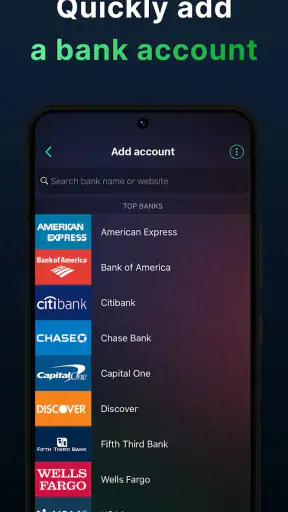
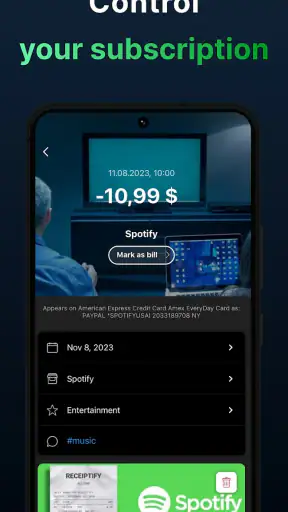
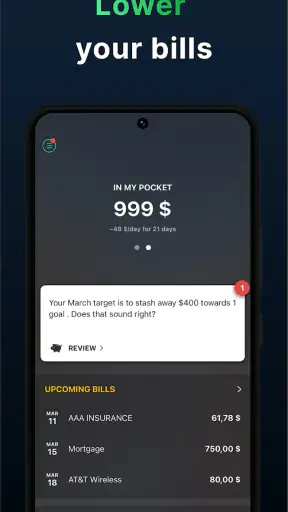
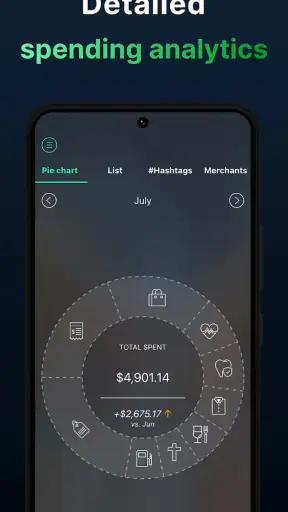
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple dashboards make everyday spending easy to understand.
- Automatic categorization reduces the effort needed to track purchases.
- Useful alerts can help prevent overspending and missed bill payments.
- Supports savings goals for users building better financial habits.
- Bank-level security features help protect connected financial information.
Cons
- Some useful tools require a paid PocketGuard Plus subscription.
- Bank connections may occasionally fail or need to be refreshed.
- Limited customization may frustrate users with complex budgeting systems.
- Automatic categories can require manual corrections for unusual transactions.
- Availability and features may vary depending on your country and bank.
Review of Budget App — PocketGuard Appxis
Managing money usually becomes difficult at the exact moment life gets busy. Bills arrive on different days, card purchases blend into one long statement, and a budget that looked realistic at the start of the month can quietly disappear. I spent time with PocketGuard to see whether its central promise—giving you a clearer view of what you can safely spend—actually makes everyday budgeting easier. My short answer is that it can, especially if you want guidance from your existing financial activity rather than another blank spreadsheet to maintain.
This is a free finance app from PocketGuard, Inc., aimed at people who want to track spending, organize income, control expenses, and put money aside with less manual work. It is rated for Everyone, runs on Android versions from 8.0 onward, and has built a sizeable audience with more than one hundred thousand installs. Its average rating is 4.5 from roughly 2.9 thousand ratings, which suggests that the basic approach works well for many users, although a rating alone cannot tell you whether its style suits your finances.
Why the “safe to spend” idea matters
The most useful way to understand this app is not as a digital envelope system or a simple expense notebook. Its real appeal is the attempt to turn a complicated financial picture into a practical spending decision. Instead of asking only, “How much money is in my account?”, I found myself asking, “After regular obligations and planned saving, what is genuinely available for ordinary spending?” That is a much more useful question when the month is still in progress.
This distinction matters because an account balance can be misleading. A balance may include money reserved for rent, utilities, a subscription renewal, or a payment that has not cleared yet. If I treat the full amount as available, I can feel comfortable for a few days and then face a shortage later. The app’s budgeting focus is designed to separate day-to-day freedom from money that already has a job.
The strongest benefit is not seeing every transaction; it is giving those transactions context. A list of purchases tells me where money went. A spending view connected to income, expenses, and savings goals can help me decide what to do next. That changes the app from a passive record into a more active budgeting companion.
There is also a psychological advantage. Traditional budgeting often requires a person to remember several categories and perform their own calculations before making a small purchase. A clearer available-spending figure reduces that mental load. It does not remove responsibility, but it makes the consequence of a purchase easier to understand while the decision is still in front of me.
What I would set up first
I would begin with the financial picture that affects the current month, rather than trying to build a perfect historical record. Income, recurring obligations, ordinary spending, and a realistic savings target are the pieces that make the app useful. If these are vague, the result will be vague too. A budgeting app cannot know that a payment is important unless I identify it properly or keep the relevant information current.
My advice is to treat the first setup as a short financial audit. Look at recent statements, notice which payments repeat, and separate genuine necessities from flexible purchases. This is more valuable than immediately creating a long list of categories. The objective is to make the spending figure believable, not to create an elaborate system that becomes tiring after a week.
Once the basic structure is in place, I would check whether the app’s view matches reality. If the amount that appears available feels too generous, I would pause before trusting it and look for an obligation, irregular bill, or planned transfer that has not been represented. That small verification step is important because financial apps are only as useful as the information they are working with.
Using it during an ordinary month
Imagine I receive my salary near the beginning of the month. Rent and regular bills are due at different points, groceries vary from week to week, and I want to save a little without making the plan so strict that I abandon it. With a basic expense tracker, I would see purchases after they happen and perhaps notice a pattern at the end of the month. With PocketGuard’s budgeting approach, I can use the remaining-spending view as a decision aid throughout the month.
Suppose I am considering a restaurant meal after several grocery trips and a larger household purchase. The useful question is not whether my bank balance can cover the meal today. It is whether the meal still fits after the upcoming obligations and the amount I intended to preserve. If the available figure has narrowed, I can choose a cheaper option before the purchase, rather than discovering the problem when a bill is due.
This is where the app feels more practical than a spreadsheet for many people. A spreadsheet can be more flexible, but it depends on regular data entry and personal discipline. PocketGuard is built around making the financial picture easier to consult. I still need to review unusual spending and correct mistakes, but the routine decision can be quicker.
I would also use it at the end of each week, not only when I feel financially stressed. A brief review can show whether the month is drifting because of frequent small purchases, one exceptional expense, or an unrealistic savings target. Those causes require different responses. Cutting every category is not sensible if the real issue was a single annual payment, while ignoring repeated small purchases can leave the same problem unresolved.
A practical workflow for irregular expenses
Irregular expenses are where many monthly budgets become unreliable. A car repair, school cost, annual service, or seasonal purchase may not appear every month, but it still belongs in the broader plan. I would use the app’s income, expense, and saving focus to make these costs visible before they arrive, rather than treating them as surprises.
The important trade-off is between a simple plan and a complete plan. If I add every possible future expense, the available amount may become discouraging and difficult to interpret. If I ignore non-monthly obligations, the figure may look comfortable while hiding a future problem. I would include expenses that are both likely and financially meaningful, then review the plan when circumstances change.
This approach also helps with “false savings.” Moving money into a savings category can look positive, but if I then need to withdraw it for a predictable bill, the plan was not really working. A better workflow is to distinguish money reserved for a known obligation from money intended for a genuine longer-term goal. That separation makes the app’s spending guidance more honest.
Where the app is more useful than familiar alternatives
Compared with a bank app, PocketGuard is more focused on interpretation. A bank application is the authoritative place to check balances and transactions, but it often leaves me to decide how much of the balance is already committed. PocketGuard’s value is in putting budgeting questions at the center rather than making me construct the answer from separate screens.
Compared with a spreadsheet, it offers less of the open-ended control that appeals to people who enjoy designing their own financial model. A spreadsheet can handle unusual household arrangements, detailed forecasting, and custom formulas. It can also become a second job. I would choose PocketGuard when I want a ready-made budgeting perspective and choose a spreadsheet when my finances require a highly personal structure.
Compared with a basic expense tracker, the difference is the connection between spending and remaining capacity. A tracker is excellent for awareness: it can reveal that takeout, transport, or online shopping is consuming more than expected. PocketGuard is more useful when I want that awareness to influence what I can spend next. The two approaches are not opposites, but this app is aimed at the decision after the tracking.
The friction I would not ignore
The first limitation is that financial clarity still requires maintenance. No budgeting view should be accepted blindly. Income can change, bills can vary, and a purchase can be categorized incorrectly. If I stop checking the information behind the summary, the app may give me a neat answer based on an outdated situation. The convenience is real, but it does not replace a monthly review.
Another concern is that people with complicated finances may find a simplified available-spending number too narrow. Multiple income sources, shared household accounts, debt repayment plans, business expenses, or frequent transfers can require more explanation than a quick budget view provides. In that situation, I would use PocketGuard as one perspective rather than the only financial system.
The app may also feel unnecessary to someone who already has a reliable manual routine. If I reconcile a spreadsheet every few days, understand my upcoming obligations, and rarely overspend, switching tools may not produce a dramatic improvement. The strongest case is for people who know they need structure but do not consistently maintain a detailed manual budget.
There is a further practical point about cost. The app itself is free to download, but in-app purchases range from under a dollar to nearly one hundred fifty dollars per item. That wide range means I would examine the available plan and payment screen carefully before committing to anything beyond the free experience. A free entry point is useful, but it should not be confused with every possible function being permanently free.
Who gets the most from this approach
I think the best audience is someone whose money is not completely out of control but feels difficult to read. Perhaps the person earns regularly, pays bills on time, and still wonders where the month went. The app can provide a more immediate connection between past spending and the amount that remains safe for ordinary use.
It is also a good fit for someone starting a first serious budget. A blank spreadsheet can be intimidating, while a simple spending-oriented view gives the beginner a concrete place to start. I would still encourage learning the reasoning behind the figures, because understanding the budget is more valuable than following a number without question.
Couples or families may find it useful as a shared conversation starter, but I would be cautious about treating one summary as a complete household agreement. Different people may define “available” differently, especially when some expenses are personal and others are shared. The app can support the discussion, yet the household still needs clear rules about responsibilities and savings priorities.
People with very predictable income and recurring costs may appreciate the calm of checking one practical figure. People with unstable income should use more caution. In that case, I would plan around the lower dependable income level and regard extra earnings as a buffer rather than immediately increasing flexible spending. The app can help organize that thinking, but it cannot make uncertain income predictable.
What the current release means for new users
The current version is 5.19.3, and the app has been available since March 16, 2016. I see that long presence as useful context: this is not a brand-new experiment in the finance category. At the same time, a long-running app can still change in ways that affect how familiar screens feel, so I would give myself a little time to understand the current layout instead of relying on older instructions or memories of previous versions.
Android users should note that the minimum operating-system requirement is version 8.0. The Everyone age rating makes the app broadly approachable, although financial decisions themselves are still personal and sometimes complex. I would keep notifications and review habits proportionate to my needs; checking too often can create anxiety, while never checking makes any budgeting tool ineffective.
The developer is PocketGuard, Inc., and the app has attracted more than one hundred thousand installs. Its roughly one thousand two hundred written reviews and 4.5 average give a useful signal that many people find the experience worthwhile, but I would still judge it by my own financial workflow. A popular budgeting method is not automatically the right method for someone who needs detailed forecasting or strict cash-envelope control.
My recommendation after using the budgeting view
I would recommend PocketGuard to a friend who wants a faster answer to the question, “Can I afford this without damaging the rest of my month?” Its emphasis on connecting spending, income, expenses, and saving gives it a clear purpose, and that purpose is more actionable than simply collecting transaction history. The everyday restaurant example is small, but repeated decisions like that are where a budget succeeds or fails.
I would not recommend relying on it without an initial reality check or regular updates. The app can simplify the picture, but simplification becomes dangerous if it hides irregular bills, changing income, or shared financial responsibilities. I would also point someone with a highly customized financial system toward a spreadsheet or a more specialized tool if they need detailed forecasting beyond a practical spending overview.
For the right user, the free starting point makes it easy to test the method before deciding whether any in-app purchase is worthwhile. My final view is positive but measured: PocketGuard works best as a daily spending compass, not as a substitute for understanding your entire financial life. If you want less guesswork between payday and the next round of bills, it is a sensible app to try. If you already have a precise system or need deep customization, its streamlined approach may feel limiting rather than liberating.
FAQ
What is PocketGuard, and how does it help with budgeting?
PocketGuard is a personal finance and budgeting app designed to show how much money you can safely spend after accounting for bills, savings goals, and everyday expenses. After connecting eligible financial accounts, the app organizes transactions and presents an “available to spend” figure. This can make budgeting easier for users who prefer a simple overview instead of building a detailed spreadsheet manually.
Is PocketGuard safe to use with my bank accounts?
PocketGuard uses financial-data connection services and security measures intended to protect account information, but users should still review the app’s privacy policy and permissions before connecting any accounts. The app generally provides read-only access rather than the ability to move money, although availability can depend on the institution and connection provider. Use a strong password and enable any available security features.
Does PocketGuard automatically track bills, subscriptions, and spending?
PocketGuard can automatically import and categorize transactions from connected accounts, helping you monitor purchases, recurring bills, and subscriptions in one place. In testing this type of feature is convenient, but categories and merchant names may occasionally need correction. Users should review imported information regularly, especially when an account connection fails or a bill changes, so the spending overview remains accurate.
Is PocketGuard free, or does it require a subscription?
PocketGuard offers a free version in some markets, but several advanced budgeting and customization tools may be restricted to a paid plan. Premium features can include more detailed budgeting controls, additional financial insights, or enhanced account management options. Pricing, trial availability, and included features may vary by platform and region, so check the current App Store or Google Play listing before downloading.
Who should consider downloading PocketGuard?
PocketGuard is a good choice for people who want a quick, automated view of their finances and need help controlling discretionary spending. It may be especially useful for beginners, busy users, or anyone who finds traditional envelope systems and spreadsheets too complicated. However, users requiring highly detailed investment tracking, complex household budgeting, or complete manual control may prefer a more advanced finance app.


