

B9: Cash Advance
B9 - Get Your Paycheck EarlyFinance
Scanned and Safe · Free
- Rating
- 4.6Out of 5
- Downloads
- 1.00M
- Android
- 8.0
Screenshots
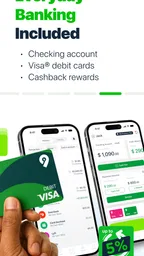
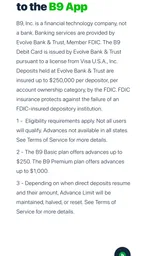
Analysis by Appxis
I find a pay-advance app easiest to judge in the kind of ordinary moment when a household bill arrives before the next paycheck. That is where B9: Cash Advance・Banking・Earn may be useful: it is a finance app from B9 - Get Your Paycheck Early, built around access to money ahead of payday. I would treat it as a possible short-term tool, not as a substitute for a household budget or a reliable source of extra income.
Using a pay-advance app in a shared household
In a shared home, I’d keep the decision to use a pay-advance app with the person whose paycheck and account are involved, even when the money is meant for a common bill. A quick household check of the bill date and the next pay cycle can help everyone coordinate without sharing logins or treating an advance as extra income.
When one person needs a short-term bridge
Picture a household where one adult pays for groceries and another covers a utility bill. A necessary expense lands a few days before payday, and the person responsible for it is short on cash. An advance could help bridge that timing gap, but it does not make the bill cheaper; it shifts when some of the paycheck is available. I would first check the next pay cycle’s obligations and decide together whether using an advance solves a one-off timing problem or merely moves the shortfall forward.
That distinction matters more than the convenience of opening an app. If the expense is urgent and the repayment timing fits the household’s existing commitments, a cash advance may be worth considering. If the same gap returns every pay period, I would look for a longer-term change—such as adjusting bill due dates or revisiting recurring expenses—instead of relying on advances as routine income.
Keep financial accounts personal on a shared device
A phone used by more than one person can make financial tasks convenient, but it also calls for clear boundaries. I would use my own account and avoid sharing sign-in details, even with someone I trust. Before handing a device to another household member, I would close the app and make sure the phone itself is protected with a screen lock. These are practical account-safety habits, not special family controls.
If a partner helps with planning, agree on what information you actually need to share: perhaps the amount of a bill and its due date, rather than access to each other’s financial account. Keeping that conversation separate from the login reduces confusion about who requested an advance, who is responsible for a repayment, and whose paycheck is affected.
Coordinate the timing, not just the amount
When an advance is being considered for a shared expense, I would write down the bill, the person paying it, and the expected paycheck it needs to fit around. That small step can prevent a household from treating the available amount as spare spending money. It also gives everyone a chance to spot a conflict with rent, groceries, or another essential payment before making a decision.
More Stories While You Read






One useful check is to plan the following pay period before taking money early. If the advance would leave too little for obligations that are already scheduled, it may not be the right fix, even if it covers today’s need. I would also avoid making a second person responsible for a repayment unless the account and terms genuinely put them in that position; household agreement should not be confused with account access or legal responsibility.
Age, trust, and who should use it
The app is marked for Everyone, but that content label is not a recommendation for children to use a financial product. In a household, I would keep any financial account under the control of the adult who owns it and explain the difference between earned pay and money made available early. Younger family members can learn about budgeting without handling an adult’s login or making borrowing decisions.
I would consider the app most relevant to an adult with a paycheck, a short-lived cash-flow mismatch, and a clear plan for the next pay cycle. Someone with irregular income, uncertain repayment capacity, or a recurring shortfall should be cautious. A lower-cost option such as asking a bill provider about a due-date change, using savings set aside for emergencies, or speaking with a bank or credit union may be a better fit, depending on the situation.
What to check before relying on an advance
Before using any pay-advance service, I would read the current terms in the app and check the exact amount available to me, the timing of the transfer, and how repayment works. An advertised maximum is not a promise that every user will qualify for that amount. Eligibility and access can depend on an individual’s circumstances, so I would plan around what the app actually offers rather than building a bill-payment plan around a headline figure.
I would also compare the full cost and timing with the alternatives available for that specific bill. A late fee, a bank overdraft, a credit-card balance, and an advance all have different consequences; none is automatically the best choice. If I cannot tell how repayment will affect my next paycheck, I would pause and get clarity before proceeding. The key question is not only whether money can arrive sooner, but whether the next payday still covers essentials.
For a shared household, one person should be the decision-maker for their own account, while the people affected by a shared bill can coordinate the household budget. That approach keeps the practical conversation—how to pay for groceries or a utility bill—separate from handing over financial credentials. It is a small boundary, but an important one when a phone is used around the home.
Where B9 fits among the alternatives
Compared with a conventional bank account, a pay-advance app is aimed at a narrower problem: getting access to some pay earlier rather than simply storing money and paying bills. Compared with a credit card, it is not a reusable line of credit for purchases. And compared with a personal loan, it is not best viewed as a way to fund a larger expense over a long period. Those options have different costs, application processes, and repayment structures, so I would compare the actual terms rather than assume one is always cheaper or faster.
The app is free to install, and it has an average rating of 4.2 from around 11,000 ratings, with more than 6,000 written reviews. Those figures offer a little context about its audience, but they do not tell me whether a particular user will qualify or whether an advance is the right choice for their budget. I would use other people’s feedback as a prompt to inspect the current experience and terms, not as a guarantee of results.
It has been available since August 2021, and version 3.27.0 is listed for devices running Android 8.0 or later. The app is used by more than 500,000 people, but a large install base does not remove the need to understand account security and repayment before connecting a financial routine to it. I would also keep the app updated through the relevant app store and use the device’s ordinary security settings.
A practical first-use routine
If I were trying it for a real household expense, I would begin with the bill rather than with the amount of money the app might make available. I would note the due date, check the cash already on hand, and work out what the next paycheck must cover. Then I would review the app’s current eligibility and terms, decide whether the timing actually helps, and avoid taking more than the expense requires.
Afterward, I would record the advance alongside the next pay period’s planned bills. That makes it easier to see whether the decision solved a one-time mismatch or points to a recurring budget problem. If the same expense keeps pushing the household toward early access, I would treat that pattern as a signal to revisit the budget rather than as proof that a larger advance is needed.
The developer is B9 - Get Your Paycheck Early, and the app is free to download. That does not by itself establish what a specific advance will cost or how quickly it will be available, so I would check those details before making a decision. For me, that is the sensible way to judge a financial app: understand the transaction in front of me, then decide whether the convenience is worth it.
What the app offers and what I would verify
Ever felt the crunch right before payday? You know, that awkward stretch where you’re counting pennies and wondering if it’s ramen for dinner again? Well, that's where B9 swoops in like a superhero in your financial saga. It's like having a mini financial assistant in your pocket, ready to rescue you when times get tight.
A Quick Peek into Features
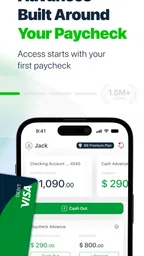
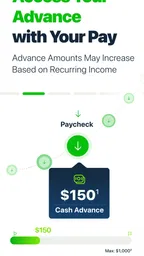
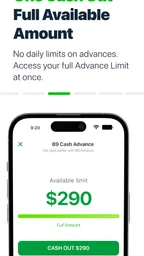
So, what exactly does it do to make life easier? First off, it offers cash advances which can really help bridge the gap until your next paycheck. The amount available can be as much as $1,000 per pay, but I would treat that as a ceiling rather than a promise: what one person can access may not be what another can. Before planning around an advance, I’d check the amount shown to me and the terms that apply.
But wait, there’s more! The app also doubles up as a digital banking platform. You can manage your finances with ease, keeping track of your spending, and even setting up direct deposits. It’s like having a bank that fits in your back pocket, ready to go wherever you do.
The User Experience
Let's talk usability. The interface is clean, intuitive, and super easy to navigate. Whether you're a tech geek or someone who still struggles with setting up a Facebook account, you'll find it user-friendly. The app guides you through its features without overwhelming you with unnecessary jargon or complicated steps.
Signing up is a breeze too. With just a few taps, you’re ready to explore all that B9 has to offer. Plus, the support team is just a message away if you ever hit a snag.
Why Consider It?
In a world where financial stress is all too common, having a tool like this can be a real game-changer. It’s not just about getting a cash advance; it’s about financial empowerment. You have control over your money, with the flexibility to manage unexpected expenses without breaking a sweat.
Moreover, the app is continuously updated with new features aimed at making your financial life easier. From budgeting tools to savings options, B9 is committed to evolving with its users’ needs.
In conclusion, if you’re someone who occasionally finds yourself in a financial pinch or you're looking for a convenient banking alternative, B9: Cash Advance・Banking・Earn might just be the right fit. I’d consider it for a short-term timing gap, while keeping the next paycheck and household commitments firmly in view. Your wallet will thank you only if the advance fits the budget rather than postponing a problem.
Pros
- Instant cash advances available.
- No hidden fees or charges.
- User-friendly interface design.
- Real-time transaction alerts.
- 24/7 customer support available.
Cons
- Limited to eligible users only.
- Requires bank account linking.
- Not available in all regions.
- Cash advance limits apply.
- Some features require subscription.
B9: Cash Advance FAQ
What is B9: Cash Advance・Banking・Earn and how does it work?
B9: Cash Advance・Banking・Earn is a financial app designed to provide users with cash advances, banking services, and opportunities to earn. It connects to your existing bank account to analyze your income patterns and offers cash advances based on your earnings. By using B9, you can access funds before payday, avoid overdraft fees, and manage your finances more effectively through its banking features.
Is B9: Cash Advance・Banking・Earn safe to use?
Yes, B9: Cash Advance・Banking・Earn uses bank-level security measures to protect your personal and financial information. The app employs encryption and secure servers to ensure that your data is safe. Additionally, it does not store your banking credentials, which adds an extra layer of security. Users can feel confident using B9 knowing that their privacy and security are prioritized.
How much does it cost to use B9: Cash Advance・Banking・Earn?
B9 offers a subscription model to access its services, which includes cash advances and other banking features. The subscription fee is competitive, and users often find the convenience and savings on overdraft fees to be worth the cost. It's important to review the app's pricing details in the app store or official website to understand the specific cost associated with the service.
Can I use B9: Cash Advance・Banking・Earn if my credit score is low?
Yes, B9: Cash Advance・Banking・Earn does not require a credit check to provide cash advances. The app bases its advance limits on your income and financial behavior rather than your credit score. This makes it an accessible option for individuals with lower credit scores who need financial assistance to bridge gaps between paychecks.
What are the eligibility requirements for using B9: Cash Advance・Banking・Earn?
To use B9: Cash Advance・Banking・Earn, you need to be at least 18 years old, have a valid bank account, and demonstrate a consistent income flow. The app connects to your bank to verify your income patterns and assess your eligibility for cash advances. Ensuring these requirements are met will facilitate a smoother experience when using the app.
Other Picks in This Category

Google Wallet
Google LLC 4.4 Out of 5

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe 4.5 Out of 5

Binance: Buy Bitcoin & Crypto
Binance Inc. 4.8 Out of 5

Cash App
Block, Inc. 4.7 Out of 5
More Finance Reviews

PayPal - Pay, Send, Save
PayPal Mobile 4.2 Out of 5

TrueMoney
True Money Co. Ltd. 3.6 Out of 5

MetaTrader 5 — Forex, Stocks
MetaQuotes Software Corp. 4.7 Out of 5

Wise: International Transfers
Wise Payments Ltd. 4.8 Out of 5

Revolut: Spend, Save, Trade
Revolut Ltd 4.5 Out of 5

Investing.com: Stock Market
INVESTING.com 4.7 Out of 5
About This Listing
- Developer
- B9 - Get Your Paycheck Early
- Package Name
- com.b9.app
- Version
- 3.71.0
- Android
- 8.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at support@bnine.com, visit https://bnine.com, or view the https://bnine.com/privacy-policy.