Ava Finance

- 1.69K Reviews
- 4.7
- Downloads
- 500.00K
- 5.1.6626
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple way to track budgets
- spending
- and financial goals.
- Personalized insights can help identify unnecessary expenses.
- Useful reminders support more consistent bill and payment management.
- Clean interface makes key financial information easy to find.
- Can encourage better saving habits through progress tracking.
Cons
- Some features may require linking sensitive financial accounts.
- Available tools can vary depending on your country or bank.
- Automatic transaction categorization may occasionally be inaccurate.
- Users may need time to review and correct imported transactions.
- Privacy policies and data permissions deserve careful review.
Review of Ava Finance Appxis
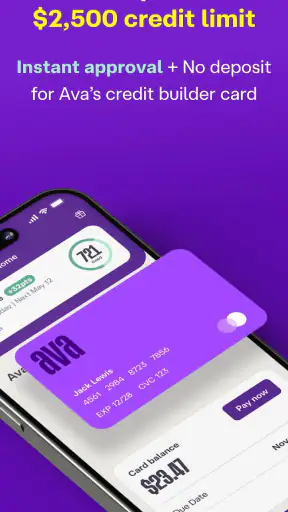
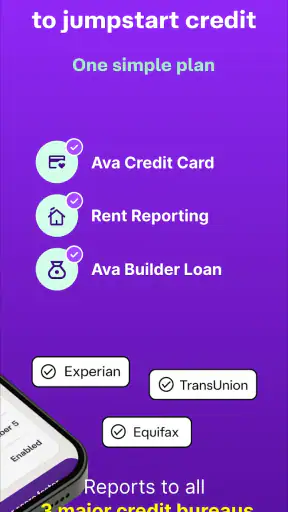
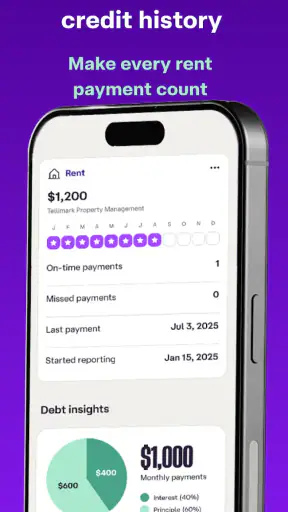
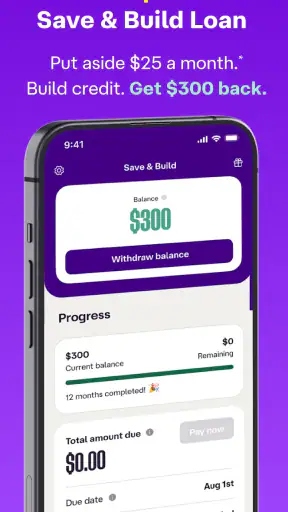
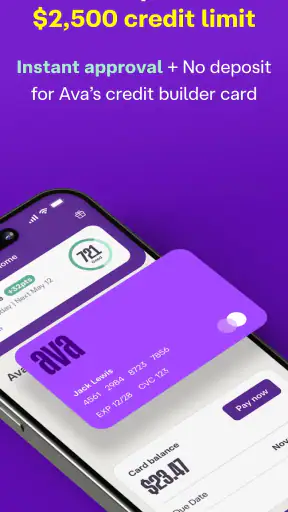
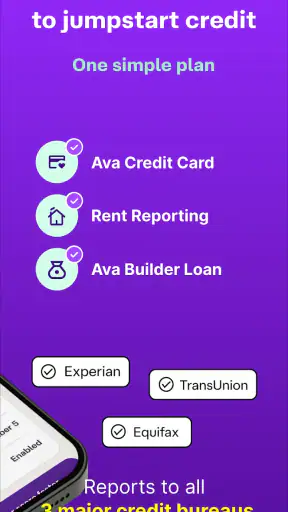
Building credit can feel frustrating when the actions that help most are slow, difficult to track, or disconnected from everyday spending. I found Ava Finance most useful as a guided finance app for people who want a clearer routine around credit-building rather than another full banking replacement. Its focus is narrow, and that is part of its appeal: instead of trying to become your checking account, investment platform, and budgeting dashboard at once, it centers the experience on helping users work toward stronger credit habits.
Ava Finance is a free finance app from Ava Finance, Inc., available for users aged Everyone. It has attracted over 500 thousand installs and holds a 4.7 average from around 17 thousand ratings, which suggests that the basic idea is resonating with many people. I would still treat those figures as a sign of popularity rather than a guarantee that it will suit every financial situation. Credit products are personal, and the right choice depends on what you already use, what you need to improve, and how consistently you can follow a repayment routine.
How I used Ava Finance as a repeatable credit routine
The most helpful way to approach the app is to establish a baseline workflow before chasing every available option. I would begin by completing the setup carefully, reading each screen instead of tapping through automatically, and making sure the information supplied is accurate. Finance apps are only as useful as the profile behind them, and a rushed setup can create confusion later when you are trying to understand progress or manage a payment-related task.
Once the initial work is complete, I would treat Ava as a recurring check-in rather than an app to open only when something goes wrong. A simple habit is to review the current status at the same point in your weekly money routine. For example, someone paid every other Friday could check after payday, confirm what needs attention, and then revisit the app before the next pay cycle. That turns credit-building into a scheduled behavior instead of a vague goal.
A realistic everyday scenario would be a person who has limited credit history and is trying to become more organized before applying for a larger financial product. They might use Ava alongside their normal bank account, keep a reminder for the relevant payment activity, and avoid treating the app as permission to spend more. The app can make the routine easier to follow, but it cannot replace the discipline of keeping enough money available and understanding the commitments involved.
This distinction matters because “build credit fast” sounds more immediate than credit improvement usually feels in real life. Ava can provide a structured path, but progress is not something I would expect to control instantly from a single screen. I see the app as a tool for making responsible actions more repeatable, not as a shortcut around time, affordability, or the consequences of missed payments.
Compared with a traditional bank app, Ava is more focused on the credit-building objective. A bank application is usually better for checking balances, moving money, and reviewing ordinary account activity. Compared with a general budgeting app, Ava is less about categorizing every purchase and more about a specific financial outcome. That focus is useful if credit is your main concern, but it also means you may still need another app for a complete household budget.
What I would check before relying on it
Before using any credit-focused product, I would read the in-app terms and make sure I understand how the arrangement works in practice. Pay attention to the timing of obligations, the money that must remain available, and any instructions connected with account activity. The most important question is not whether an app looks simple; it is whether you can follow its routine without creating a cash-flow problem elsewhere.
I would also keep expectations realistic. A credit-building tool is not the same as a guaranteed approval service, and a stronger credit profile does not automatically make every loan or card affordable. If you are already carrying expensive debt, an app centered on building credit may not be the first financial step to take. In that situation, reducing missed payments and understanding existing balances may matter more than adding another credit-related workflow.
The app is particularly appealing for someone who feels lost when looking at credit for the first time. Its focused purpose can reduce the number of decisions competing for attention. On the other hand, experienced users who already have a well-managed credit card, automatic payments, and a reliable monitoring system may find less added value. They may prefer their existing bank tools or a broader credit-monitoring service that combines more accounts in one place.
Settings and habits worth checking
Rather than changing settings casually, I would review notification preferences and account-related reminders during setup and again after using the app for a few days. A reminder that arrives at the wrong time is easy to ignore, while one that fits your payday or bill-review routine is more useful. The goal is not to receive every alert; it is to receive the alerts that prevent a missed action without creating notification fatigue.
I would also check the app after an important change in my financial life, such as switching banks, changing income timing, or adjusting recurring expenses. Even if the app itself does not replace a budget, your ability to complete its routine depends on the money available in your wider financial system. A credit strategy that works comfortably during one month may become risky after a rent increase or an irregular paycheck.
One practical tip is to keep Ava’s role clearly separated from your spending account in your own mental checklist. When people see a credit-building balance or available amount, they can mistakenly treat it as extra money. I would write down the amount that must remain available and compare it with upcoming essentials before making optional purchases. This small separation helps prevent the app from encouraging behavior that undermines the reason for using it.
Another useful habit is to save the key dates and actions in the same place where you manage other bills. I would not rely on memory or on a single push notification. A calendar reminder, a weekly money review, and a quick in-app confirmation form a stronger system than any one of those steps alone. This is especially important for users who share household finances or whose income arrives on an irregular schedule.
Faster patterns for regular users
Once the basic routine is comfortable, the fastest approach is usually consistency rather than constant interaction. I would create a short sequence: open the app, review the current status, check whether anything needs action, confirm that the supporting money is available, and close it. Repeating that sequence at a fixed time makes the app less mentally expensive and reduces the chance of overlooking a small but important task.
Users who prefer shortcuts should build them around their own calendar rather than assuming the app can automate every part of the process. Pairing the review with an existing habit, such as checking a bank balance after payday or planning groceries, is more reliable than opening Ava randomly. This is one of the less obvious strengths of a focused app: because it has a clear purpose, it can fit neatly into a short weekly financial ritual.
I would also avoid checking progress repeatedly throughout the day. Credit-related changes are not usually improved by refreshing a screen, and frequent checking can create unnecessary anxiety. A scheduled review gives you enough awareness to act while keeping the app from becoming a source of constant reassurance-seeking.
For households, the useful pattern is to agree on who owns the routine. If two people assume the other person is monitoring the app, a missed action becomes more likely. One person can handle the weekly review while the other confirms that the necessary funds remain available. This is not a special feature of Ava; it is a practical way to use any shared financial tool without duplicating work or leaving gaps.
I would also keep a simple record of what I did and when, especially during the first few cycles. A note in a personal finance journal can help answer questions later without depending entirely on memory. It also makes it easier to spot a mismatch between the app’s routine and your real cash flow. If the process repeatedly feels tight, that is a warning to reconsider the setup rather than simply trying to move faster.
Where the app reaches its limits
The biggest limitation is that Ava cannot make an unaffordable financial commitment safe. If your income is unpredictable, your emergency savings are minimal, or your existing bills already consume most of your available money, adding a credit-building routine may increase pressure. In that case, a basic budgeting system or direct help from a qualified financial counselor may be more appropriate as a first move.
I also would not use it as my only source of financial information. A focused credit app may help with its particular workflow, but it is not a substitute for reviewing bank statements, checking recurring charges, and understanding debt costs. The broader picture still lives across your accounts. Anyone expecting Ava to provide a complete view of spending, savings, debt payoff, and long-term planning may find the experience too limited.
There is also a learning curve hidden beneath the simple goal. New users may understand that they want better credit without understanding how utilization, payment timing, account age, and applications interact across their wider profile. Ava can support a routine, but I would still learn the basic principles independently. That knowledge helps you judge whether the app is helping your situation and prevents you from assuming that one positive action fixes every credit issue.
People with established credit habits should compare the app with what they already have before adding it. If your current card issuer offers clear statements, dependable automatic payments, and useful credit education, another service may add complexity without solving a real problem. Ava makes more sense when its focused workflow fills a gap, not simply because it is free.
Device compatibility is another practical consideration. The current version is 5.1.6626 and requires Android 9 or later. That makes it accessible to many Android users, but anyone with an older phone should check compatibility before planning around it. iOS users should likewise confirm the appropriate mobile-store availability for their device before assuming the same experience is available on every platform.
Who should use it, and who should skip it
I would recommend Ava to a newcomer who wants a dedicated credit-building routine and benefits from having one clear objective. It can also suit someone who has tried to improve credit informally but keeps forgetting dates, losing track of tasks, or treating the goal as something to handle later. The free entry point makes it easier to explore without committing to a purchase, although the financial responsibilities connected with the workflow still deserve careful attention.
I would be more cautious if you are looking for a complete money-management center. Someone who wants detailed envelope budgeting, investment tracking, extensive debt snowball tools, or a unified view of several financial institutions may be better served by a broader personal finance app. Likewise, if your main problem is high-interest debt rather than limited credit history, a debt-reduction plan may deliver more immediate value.
I would also skip it if you are tempted by the promise of speed and are not prepared to maintain a routine. Credit improvement rewards patience and accurate follow-through. No interface can compensate for spending money you need for essentials, ignoring notices, or opening products without understanding their effect. The app is best viewed as support for good decisions, not as a replacement for them.
My final view after testing the workflow
Ava Finance is a focused finance app that makes the most sense when your goal is to establish a repeatable credit-building habit. I like that its purpose is easier to understand than the crowded dashboards found in many general finance apps. The strongest experience comes from combining the app with a calendar routine, a separate check of available cash, and a realistic understanding of what credit improvement can and cannot do.
Its weaknesses are equally clear. It does not remove the need for broader budgeting, it cannot guarantee a particular credit outcome, and it may feel unnecessary for users who already have dependable systems in place. The app works best when it fills a specific gap rather than becoming another financial account to monitor without a plan.
With an Everyone age rating, a free price, and a current Android requirement of 9 or later, it is approachable for many users. The developer, Ava Finance, Inc., has built an experience aimed at a common problem, and the strong user response gives it a credible starting point. My recommendation is simple: use it if you want structure around credit building, but pair that structure with your own budget and a careful review of every obligation.
For me, the mastery test is not how often I open the app or how quickly I move through its screens. It is whether the routine remains affordable, understandable, and easy to repeat month after month. If Ava helps you achieve that without confusing you about your available money, it can be a worthwhile addition. If it makes your finances harder to track or encourages you to stretch your budget, a simpler alternative is the better choice.
FAQ
What is Ava Finance, and what can I use it for?
Ava Finance is a personal finance application designed to help users organize and monitor their money in one place. Depending on the services available in your region, it may provide tools for tracking spending, managing budgets, viewing financial accounts, and reviewing transactions. Before downloading, check the official app description to confirm which features and financial products are supported in your country.
Is Ava Finance safe to use with my financial information?
Ava Finance may require sensitive information if you connect bank accounts, cards, or other financial services. Before signing up, review its privacy policy, security information, and the permissions requested by the app. Use a strong, unique password, enable any available two-factor authentication, and download only the official version from a trusted app store. No finance app can eliminate every security risk.
Does Ava Finance connect directly to my bank accounts or cards?
The available connection options depend on your location, supported institutions, and the version of Ava Finance you install. Some users may be able to link bank accounts or cards for automatic transaction updates, while others may need to enter information manually. Check the supported providers before downloading, and remember that connection availability can change when a bank updates its security or login requirements.
Is Ava Finance free, or does it include subscriptions and additional fees?
Ava Finance may offer free access to some tools while reserving advanced features, financial services, or premium support for paid plans. Pricing, trial periods, transaction charges, and eligibility requirements can vary by country and may change over time. Carefully read the in-app pricing details before starting a trial, especially because subscriptions can renew automatically unless canceled through the appropriate app-store settings.
Can Ava Finance provide financial advice or guarantee better money management results?
Ava Finance can help present financial information, organize transactions, and support budgeting decisions, but it should not automatically be treated as a licensed financial adviser. Any recommendations, estimates, or insights should be reviewed carefully and compared with your own circumstances. The app cannot guarantee savings, investment returns, loan approval, or improved credit results, so important financial decisions should be independently verified.


