
- 191.00 Reviews
- 3.7
- Downloads
- 100.00K
- 2.0.27
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple interface makes tracking income and expenses easy.
- Useful cash-flow summaries help users understand spending habits.
- Supports better budgeting by organizing transactions in one place.
- Quick data entry makes recording daily expenses convenient.
- Helpful for users who want a clearer view of available funds.
Cons
- May require regular manual updates to stay accurate.
- Limited value if transactions cannot be imported automatically.
- Advanced budgeting and investment tools may be missing.
- Financial data may need extra protection on shared devices.
- Some features could be restricted behind a paid version.
Review of СASHFLOW Appxis
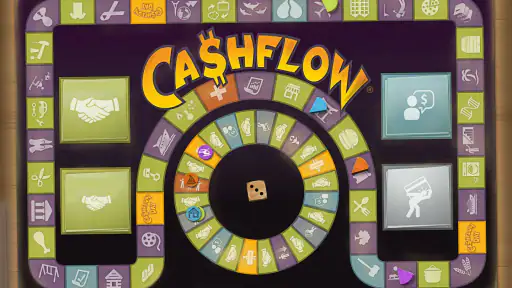
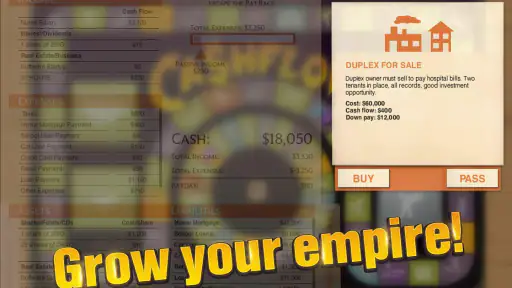
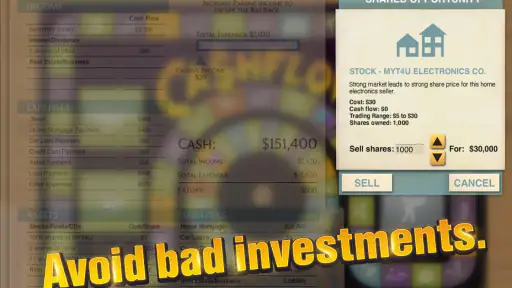
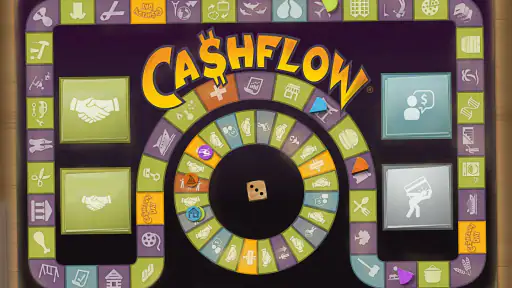
I approached CASHFLOW as an educational game rather than a conventional finance tool, and that distinction matters. Its purpose is to make investing ideas feel more tangible through play, not to replace a budgeting app, a brokerage account, or a formal personal-finance course. After spending time with it, I found the most useful question is not whether it can teach every part of investing, but whether it can make financial cause and effect easier to discuss and remember.
The game comes from Torn Screen Entertainment,Inc. and sits in a fairly unusual space on mobile: it asks you to learn by making choices instead of simply reading explanations. It is available for $1.99, carries an Everyone age rating, and has reached over 100K installs. Its average rating is 3.7 from around 3K ratings, with 191 written reviews, so there is enough public use behind it to suggest that the concept has found an audience while also showing that it will not suit every player equally.
Learning through decisions instead of passive reading
What I like about the format is that financial ideas become easier to examine when they are attached to consequences. A paragraph about income, expenses, assets, or liabilities can be easy to forget. A choice made during a game tends to stay with me because I can connect it to what happened next. That makes this a more approachable starting point for someone who finds investment vocabulary intimidating.
The educational value is strongest when I treat each session as a conversation with myself: Why did I choose that option? Was I chasing a quick result? Did I overlook the effect of recurring costs? Would the same decision make sense outside the game? Those questions turn the play session into a simple review exercise rather than a race to finish.
That also explains why I would not recommend it as a substitute for a real financial plan. A game can simplify situations so that the lesson is visible. Real investing includes changing goals, taxes, fees, personal risk tolerance, emergency savings, and many other details. Someone who already understands those subjects may find the game too basic, while a beginner can benefit from the structure as long as they do not mistake it for personalized advice.
How it feels in everyday use
I can imagine using it on a quiet evening with a teenager who has started asking about saving and investing. Instead of opening a spreadsheet immediately, I would use a short play session to introduce the difference between earning money and building assets. Afterward, we could compare one in-game decision with a real household example, such as saving for education, handling a car payment, or deciding whether a purchase creates lasting value.
It can also work for an adult who wants a low-pressure refresher. If financial terminology has always felt abstract, the game gives you a reason to revisit it without beginning with a dense textbook. The useful habit is to pause after an important decision and explain it in plain language. That pause is where much of the learning happens.
For group use, I would keep the discussion more important than the score. Two people can make different choices for sensible reasons, especially when they have different ideas about risk and timing. Comparing those reasons is more valuable than declaring one player financially correct.
Speed expectations and the feel of a session
From a performance perspective, this is the kind of game I would expect to be relatively undemanding compared with a modern action title or a visually elaborate simulation. Its educational, decision-focused identity suggests that the main workload is likely tied to presenting choices and processing the results rather than rendering a complex world. I would not install it expecting console-style spectacle; I would install it for a focused mental exercise.
That lighter expectation is helpful because it changes how I judge responsiveness. I care less about dramatic animation and more about whether the interface lets me understand a choice, select it confidently, and follow the outcome without confusion. When a learning game feels slow or cluttered, the delay interrupts the lesson. When it keeps the decision cycle clear, even a simple presentation can remain engaging.
My practical advice is to play in short, deliberate stretches at first. Rushing through choices can make the experience feel repetitive because the educational point is in considering the trade-off. A slower approach also makes it easier to notice which assumptions are influencing you. If you always choose the safest-looking option, for example, you can use that pattern as a discussion point rather than treating it as a failure.
What happens during heavier use
The most demanding moments are likely to come from the number of decisions and the attention they require, not from visual intensity. A long session can become mentally tiring even when the device itself is doing very little. That is an important distinction: a game can be technically light but still feel heavy if every turn asks you to compare income, obligations, opportunity, and risk.
I found that the best way to avoid decision fatigue is to give each session a purpose. One time, focus on how recurring expenses affect flexibility. Another time, pay attention to the difference between an attractive opportunity and a sustainable one. This approach makes repeated play more useful and prevents the experience from becoming a series of hurried taps.
For parents or teachers, I would avoid presenting it as a test that students must win. A better exercise is to ask players to record one decision they would repeat and one they would change. That turns a potentially competitive activity into reflection. It also helps reveal whether a player understands the principle or is simply following a pattern that happened to work in one session.
There is a trade-off here. People looking for fast entertainment may find the decision-making pace too measured, while people who enjoy strategy and discussion may appreciate the breathing room. The game is more compelling when I approach it as an interactive lesson, less so when I expect constant novelty.
Reliability, recovery, and the cost of interruption
A learning game earns trust when it makes it easy to return to the lesson after an interruption. Mobile use is rarely perfectly uninterrupted: a call arrives, another app takes focus, or I simply put the phone down for a while. In that situation, recovery matters almost as much as initial speed. I want to know what I was deciding, what the current objective was, and whether my progress has remained understandable.
I would therefore test the game in the way I actually use mobile apps: begin a session, leave it briefly, return later, and see whether the experience still feels coherent. I would also avoid closing it immediately after a major decision until I am satisfied that the current state has been retained. That is not a criticism of this particular title; it is a sensible habit for any mobile game where a session may be interrupted.
The existing audience gives me some confidence that the app is established rather than a brand-new experiment. Still, an average rating of 3.7 tells me to keep expectations measured. It suggests a mixed experience: the central idea appeals to many people, but presentation, pacing, or fit may divide players. I would read the rating as a reason to try it with a specific goal, not as proof that it will suit every learning style.
Recovery also has an educational side. If I have to restart a situation, I can use the second attempt to change one variable in my thinking rather than repeat every choice automatically. That makes a setback useful. In an app centered on financial decisions, the ability to examine mistakes calmly is more valuable than being protected from them.
Device constraints and practical expectations
The listed minimum operating-system requirement is Android 6.0, which places the game within reach of older compatible Android devices. That is helpful for families or classrooms using phones that are not recent flagship models. Even so, operating-system compatibility does not guarantee identical comfort on every screen. A smaller display, older touch hardware, or a device with limited available storage can make reading and selecting options less pleasant.
I would give the game a little breathing room before starting a serious session: close unrelated apps if the phone is already struggling, keep the display readable, and make sure the battery is not about to force an interruption. These are simple steps, but they matter more in an educational game because missing a detail can change the meaning of a decision.
The current version is 2.0.27, so I would install the latest available release rather than rely on an old copy. Keeping the app current is especially sensible when returning to a title after a long break. It reduces the chance that an outdated installation creates avoidable friction, while also ensuring that the experience matches the version the developer currently distributes.
On iOS, Android, and different screen sizes, the central question is not whether the game looks luxurious. It is whether the text, choices, and results remain easy to follow. Anyone with visual or motor-access needs should judge that directly on their own device before committing to extended sessions. A finance lesson loses value quickly if the interface makes careful reading uncomfortable.
Where it beats ordinary alternatives
Compared with a budgeting spreadsheet, this game is more inviting for someone who needs a reason to engage before learning the mechanics. A spreadsheet is better for recording actual household figures, testing a monthly plan, and seeing personal totals. CASHFLOW is better at creating a safe space where a beginner can encounter financial trade-offs without putting real money at risk.
Compared with a standard investing article or video, it offers more active participation. Reading can explain a concept clearly, but it does not force me to choose. The game’s advantage is that it gives the lesson a sequence: I decide, observe the result, and reconsider. Its weakness is the same as its strength: a simplified scenario cannot cover the personal detail of a real financial decision.
Compared with a conventional strategy game, it is less about reflexes and spectacle and more about the reasoning behind a choice. That makes it a better fit for a study group, a parent and child, or a beginner who wants a gentler entry point. It is a weaker fit for someone who wants rich graphics, rapid action, or an expansive fictional world.
The $1.99 price also changes the comparison. It is inexpensive enough to consider as a learning experiment, but I would still want a clear purpose before buying. If I only want a general entertainment game, there are likely more immediately exciting choices. If I want an accessible way to start talking about investing principles, the cost is easier to justify.
Three ways to get more from it
Play the same situation with different priorities. On one attempt, protect flexibility; on another, pursue growth. The point is not to find a universal winning style but to see how your priorities alter the result.
Keep a short decision journal. Write down the choice, the reason it seemed attractive, and what you learned afterward. This exposes habits such as overvaluing immediate gains or ignoring ongoing obligations.
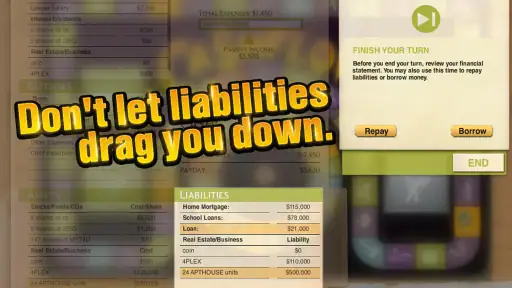
Translate one lesson into a real-world question. After a session, ask whether a household purchase creates an asset, an expense, or a liability. Do not copy the game’s answer directly; use it to start a more careful conversation.
Those methods address a weakness common to educational games: players can finish a session feeling entertained without retaining the principle. A few notes and follow-up questions turn play into learning. They also make the title more useful for adults who already know basic terms but want to examine their own decision-making style.
Who should choose it, and who should pass
I would recommend it to beginners who want investing concepts presented through choices, parents looking for a discussion starter, and educators who can guide reflection around the game. The Everyone rating makes it approachable for a broad audience, but age suitability does not mean every player will find the subject equally engaging. Younger players may need real-life examples explained alongside the game, while adults may want more depth than the simplified format provides.
I would skip it if I needed a tool for tracking my actual money, comparing real investments, or building a personalized retirement plan. It is also not my first choice for someone who learns best through detailed written instruction or wants advanced market analysis. In those cases, a spreadsheet, structured course, or specialist finance resource would be more appropriate.
I would also hesitate to recommend it to a player who dislikes replaying decisions or discussing why a choice worked. The game’s value is not only in moving forward; it is in examining the reasoning behind each move. Without that reflection, it can feel like a simplified board-game adaptation rather than a meaningful educational experience.
My performance verdict
After weighing its educational purpose against its limitations, I see CASHFLOW as a focused introductory game with modest technical expectations and a potentially useful learning loop. I would not choose it for visual excitement or for managing real finances. I would choose it when I want to make investing conversations less abstract and give a beginner a safe way to think through consequences.
Its strongest quality is the way it turns financial ideas into decisions that can be questioned. Its main weakness is that the same simplification that makes it accessible can leave experienced users wanting more detail. Performance should be judged accordingly: a smooth session is valuable here because it keeps attention on the lesson, but the real measure is whether the player leaves with a clearer understanding of their choices.
My final recommendation is cautious but positive. At $1.99, it is a reasonable option for someone specifically interested in an educational investing game, especially if they plan to play alongside conversation or note-taking. I would approach it as a starting point, not a complete financial education. The best result comes when the game sparks better questions about real money rather than pretending to answer them all.
FAQ
What is CASHFLOW, and what is the main purpose of the app?
CASHFLOW is a personal finance and money-management app designed to help users understand where their money goes. It typically lets you record income and expenses, organize transactions into categories, monitor spending habits, and review your financial progress. Before downloading, check the app’s exact feature list, supported currencies, and whether it focuses on budgeting, cash-flow tracking, or broader financial planning.
Is CASHFLOW free to download and use?
The availability of free and premium features may depend on the version of CASHFLOW and your device’s app store. Some functions may be accessible without payment, while advanced tools, additional reports, synchronization, or an ad-free experience could require a subscription or one-time purchase. Review the store listing carefully and check the pricing terms before starting any trial or entering payment information.
Does CASHFLOW connect directly to my bank accounts?
Some finance apps offer bank synchronization, while others require users to enter transactions manually. You should verify CASHFLOW’s current connection options, supported banks, countries, and security procedures before relying on automatic imports. If bank access is available, read the permissions and privacy policy carefully. Manual tracking may be slower, but it can provide greater control over the information you share.
Is my financial information safe when using CASHFLOW?
Because CASHFLOW may contain sensitive details about your income, spending, and financial goals, privacy and security are important considerations. Before installing it, review the developer’s privacy policy, data-collection disclosures, encryption claims, login protections, and backup options. Avoid entering banking credentials unless you understand how they are handled, and use a strong password or device security lock whenever the app supports it.
Can I use CASHFLOW on both Android and iPhone?
CASHFLOW’s availability can vary by platform, region, and app version, so confirm whether an official Android or iOS release is offered for your device. Also check the minimum operating-system requirements, tablet compatibility, and whether your data can be synchronized between devices. If cross-platform access is important, look for account-based backup or export tools before beginning your financial records.


