Piggy Bank Allowance - Bomad

- 46.00 Reviews
- 4.4
- Downloads
- 50.00K
- 2.0.266
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Simple way to track children’s allowances and spending
- Encourages saving habits through clear money goals
- Useful for teaching budgeting in everyday situations
- Family-focused design is easy for younger users to understand
- Can make allowance discussions more organized and consistent
Cons
- May require parental involvement to keep balances accurate
- Features may depend on account or subscription availability
- Not ideal for families seeking advanced financial reporting
- Children may lose interest without regular rewards or guidance
- Privacy settings should be reviewed before adding family information
Review of Piggy Bank Allowance - Bomad Appxis
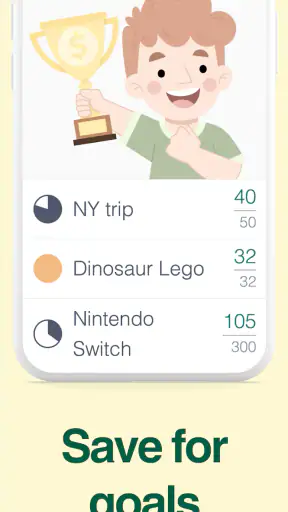
Teaching children how money works is much easier when the lesson is visible. Piggy Bank Allowance - Bomad turns pocket money into a simple digital routine built around saving and spending jars or pots. I found the idea especially useful for families who want to move beyond verbal promises such as “you can have it later” and give children a clear place to see what they have earned, saved, and used.
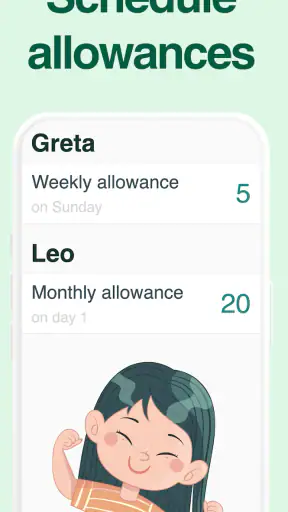
This is a free parenting app from Graeme P, with optional in-app purchases ranging from $1.99 to $29.99 per item. It is rated for Everyone, runs on devices using Android 9 or later, and the current version is 2.0.266. The app has passed the early-experiment stage: it has more than 50 thousand installs, an average rating of 4.4 from roughly 685 ratings, and 46 written reviews. Those figures suggest a small but established audience rather than a completely untested tool.
How Piggy Bank Allowance fits into family routines
The central appeal is not that it tries to become a full banking platform. Instead, it gives allowance a visual structure. A child can think in terms of separate pots: money for spending now, money being kept for something special, or perhaps a portion reserved for another family-agreed purpose. That makes the app more concrete than keeping a note in a parent’s phone or relying on memory.
I would use it as a shared conversation tool, not as an automatic replacement for real money. The parent still needs to decide when an allowance is earned, whether a task qualifies, and when a child can spend. The app helps record those decisions and makes the result easier to understand. That distinction matters because a digital balance can teach planning, but it does not independently enforce a family’s rules.
The strongest use case is a household with children who are beginning to ask where their money goes. A child can see why a purchase reduces a spending pot, while a saving pot remains untouched. That separation creates a small but meaningful lesson: having money and having money available for immediate use are not always the same thing.
It is also helpful for parents who dislike mixing chores, rewards, and spending in a single notebook. A dedicated allowance tracker keeps the conversation focused. Rather than searching through messages or trying to remember an amount from last week, I can open the routine and discuss the current balance with the child.
What the jar and pot approach teaches
The jar model is more valuable than a plain running total. A single balance tells a child how much exists, but separate containers encourage a decision about purpose. That is a subtle difference. If everything sits in one number, spending can feel unlimited until the balance reaches zero. With pots, the child has to choose whether a purchase belongs to immediate spending or conflicts with a longer-term goal.
I would recommend agreeing on the meaning of each pot before entering regular allowances. For example, one pot could be for everyday treats and another for a larger target. The important point is consistency. If parents move money between pots without explaining why, the visual system loses its teaching value. If transfers are discussed openly, the app becomes a prompt for better money conversations.
A useful routine is to review the pots at the same time each week. The review does not need to be long. Ask what was added, what was spent, and whether the child still wants the same saving goal. This turns the tracker into a habit instead of an occasional correction tool. In my view, that is where the app’s real educational value lies: not in the screen itself, but in the repeated discussion it makes easier.
Speed during ordinary use
For this type of app, perceived speed should be judged by how quickly a parent can record or review an allowance, not by demanding graphics or complex calculations. Piggy Bank Allowance has a focused purpose, so its everyday workflow should feel lighter than opening a full budgeting service. I would expect the main benefit to be the short path between deciding on an allowance and seeing it represented in the child’s pots.
That focus is important when the app is used in real family moments. A parent may be standing in a kitchen, helping with homework, or answering a child who wants to know whether a purchase is affordable. A tracker that requires a long setup every time would quickly be abandoned. The jar-and-pot design points toward a more approachable interaction than a spreadsheet, particularly for younger users who would find financial categories intimidating.
There is a trade-off, though. A simplified interface is excellent for quick decisions, but it may not satisfy a parent who wants detailed records, extensive reports, or advanced household budgeting. I would not choose this as a replacement for a personal finance app. Its value is speed of understanding rather than depth of accounting.
To keep the experience responsive in practice, I would avoid turning every tiny event into a separate administrative task. Decide in advance whether allowances are logged daily, weekly, or only when paid. A clear schedule reduces repeated data entry and prevents the parent from spending more time maintaining the tracker than discussing money with the child.
What happens when the app is used heavily
Heavy use here is less about demanding processing and more about repeated family activity. A household with several children, frequent rewards, and many changes to saving pots will place more pressure on organization than on the device. The important question is whether the system remains understandable when balances change often.
My practical advice is to keep the number of pots meaningful. Creating a separate pot for every possible category may sound educational, but it can make the child’s financial picture harder to read. Two or three clear purposes are likely to be more useful than a crowded collection of labels. This is one of the non-obvious trade-offs of a jar-based tracker: flexibility helps families adapt it, while too much flexibility can weaken the simplicity that makes it appealing.
Multiple-child households should also establish a naming convention. If each child’s money is represented in the same shared routine, names and purposes need to be unmistakable. Otherwise, the parent may spend time checking whose balance is being adjusted. The app is best used alongside a family agreement about ownership and responsibility, rather than expecting the interface alone to solve household organization.
Another realistic heavy-use moment is a child making several small spending decisions in one afternoon. Logging every minor change can become tedious, especially if the child is still learning the difference between an allowance, a gift, and a purchase. I would group agreed transactions when that reflects the family’s actual process, while still explaining the total clearly. The goal is a reliable learning record, not bookkeeping for its own sake.
Reliability and recovery in everyday family use
Reliability matters more in a money tracker than in a casual game because an incorrect balance can create an argument. I would treat every update as something worth checking with the child, particularly after a purchase or a transfer between pots. A quick verbal confirmation protects the educational routine even if someone taps the wrong control or changes a value unintentionally.
The app’s strongest reliability advantage is conceptual clarity. When each amount has a visible purpose, it is easier to notice that something looks wrong. A child may immediately ask why a saving pot changed after a snack purchase. That kind of visibility makes mistakes easier to catch than a vague total stored in a parent’s notes.
Still, I would not rely on any digital tracker as the only record for significant sums. For ordinary pocket money, the app can be a practical shared reference. For larger family arrangements, keep the parent’s own confirmation of what has actually been paid. This is not because the app is unsuitable for allowance tracking; it is because the digital balance and the physical or real-world money should not be confused.
Recovery is also a family habit. If a balance looks unexpected, pause before correcting it. Ask what the child remembers, check the recent agreement, and then make one clear adjustment. Quietly changing numbers may restore the screen but removes a chance to teach accountability. I prefer treating corrections as part of the lesson: mistakes happen, and the important skill is finding and fixing them together.
Device limits and the right audience
The minimum requirement of Android 9 makes the app suitable for many relatively modern Android phones and tablets, but it is still worth checking the child’s device before planning around it. An older hand-me-down phone may not qualify, even if it is perfectly adequate for basic communication. In that situation, the parent can keep the tracker on their own supported device and review it with the child.
The Everyone age rating fits the family-oriented purpose, but it should not be interpreted as meaning that children need to manage the system without adult guidance. Younger children may understand the visual pots quickly while still needing a parent to explain what an allowance is, why a purchase changes a balance, and why saving money means waiting.
Parents should also consider whether their family needs a shared device experience, a child-owned device, or simply a parent-controlled record. The best arrangement depends on maturity and trust. Giving a child access can encourage ownership of the routine, while keeping the app with the parent may be better when the child is too young to understand that changing a displayed balance does not create real money.
The optional purchases deserve a deliberate approach as well. The app is free to start, but individual in-app items can cost from $1.99 to $29.99. I would begin with the free experience and decide whether any paid additions genuinely improve the family’s routine. A child should not learn that every new visual option or extra convenience is automatically worth buying, especially in an app intended to teach thoughtful spending.
Where it beats the usual alternatives
The most common alternative is a paper chart on the refrigerator. Paper is wonderfully visible and does not depend on a phone, but it can become messy when allowances change, purchases are corrected, or money needs to be divided between purposes. Piggy Bank Allowance offers a cleaner digital record and makes the idea of separate pots easier to maintain over time.
A notes app is more flexible, but that flexibility is also its weakness. A plain note can hold numbers, yet it rarely gives a child an intuitive picture of spending versus saving. A spreadsheet can deliver more detail, but it usually asks parents to design the system themselves and may feel like work rather than a family activity. This app sits between those options: more structured than notes, less demanding than a spreadsheet.
A full budgeting or banking app may be better for teenagers who need transaction history, broader financial planning, or a connection to actual accounts. I would choose that route when the family’s goal is formal money management. I would choose this app when the priority is making allowance visible and understandable without introducing the complexity of adult finance.
It is not the right choice for a family that wants automatic bank transfers, detailed financial reports, or a complete chore-management platform. It is also a poor fit if parents will not review the balances with the child. The app can organize an agreement, but it cannot create a consistent allowance habit by itself.
A realistic week with the tracker
Imagine a child receives a regular allowance on the weekend and wants a small toy after school. Before the purchase, I would open the pots together and ask which one should pay for it. If the spending pot covers the cost, the child can see the decision without touching the longer-term saving pot. If it does not, the conversation becomes about waiting, choosing a cheaper item, or moving money with a clear reason.
Later in the week, the child might complete an extra task that the family has already agreed can earn a reward. The parent records it during the weekly review and asks whether the new amount should be divided between spending and saving. That second decision is where the tracker becomes more than a balance display. The child practices allocating money before it disappears.
At the next review, the family can look at whether the original goal still feels worthwhile. If the child changes plans, the parent can explain the effect of moving money between pots. This workflow avoids using the app as a punishment system. Instead, it makes earning, choosing, waiting, and revising plans visible parts of one routine.
My performance verdict
My overall impression is that Piggy Bank Allowance is strongest when it stays small in scope. Its performance value comes from reducing friction around a specific parenting task: showing children how allowance can be divided between spending and saving. The focused design should make ordinary checks feel more approachable than a conventional finance tool, while the visual pot system gives children something concrete to discuss.
Its limitations are equally clear. It depends on parents entering and explaining the information, it is not a substitute for real financial accounts, and families wanting deep reporting may outgrow it. Optional purchases also mean that “free” does not necessarily describe every possible addition, so I would review the available choices carefully before spending.
For parents introducing pocket money, I think the app is worth trying because the barrier to understanding is low. Start with a simple allowance rule, create only the pots that have a clear purpose, and review them together rather than handing the whole responsibility to the child. That approach makes the tracker useful even when the family is still learning what system works best.
With its Everyone rating, Android 9 minimum, free entry point, and established audience, it is an accessible option for basic digital allowance tracking. I would recommend it to families seeking a visual bridge between chores, pocket money, and saving goals. I would skip it in favor of a more advanced finance tool if the household needs bank integration or detailed accounting. For the narrower job it sets out to handle, however, Piggy Bank Allowance - Bomad offers a practical way to turn abstract money lessons into decisions a child can actually see.
FAQ
What is Piggy Bank Allowance - Bomad, and who is it designed for?
Piggy Bank Allowance - Bomad is an allowance-management app designed to help families organize children’s pocket money, chores, savings, and spending habits in one place. Parents can use it to record allowances or rewards, while children can follow their progress toward financial goals. It is most suitable for families looking for a simple educational tool rather than a full banking replacement.
How does the allowance and chore system work in Piggy Bank Allowance - Bomad?
The app allows parents to set up recurring allowances, assign chores or tasks, and record additional rewards or deductions when appropriate. Children can then see what they have earned and how their balance changes over time. Before downloading, parents should review the available settings carefully, since the exact workflow and customization options may depend on the app version and the device platform.
Does Piggy Bank Allowance - Bomad connect to a real bank account or make payments?
Piggy Bank Allowance - Bomad should generally be treated as a tracking and educational tool, not as a conventional bank account or payment service. Its purpose is to help families manage virtual balances and discuss money responsibilities. Users should not assume that balances can be withdrawn, transferred, or spent directly unless the current app description specifically confirms banking, card, or payment functionality.
Is Piggy Bank Allowance - Bomad safe for children to use?
The app can be useful for teaching children about earning, saving, and responsible spending, but parents should remain involved. A parent or guardian should create the family setup, decide what information is entered, and explain that the displayed balance may be a record rather than real money. It is also wise to check the latest privacy policy, permissions, age guidance, and parental-control features before allowing independent use.
Is Piggy Bank Allowance - Bomad free, and are there any limitations?
Availability, pricing, advertisements, and optional in-app purchases can vary between Android and iOS and may change with future updates. Some features may be included in the basic version while advanced customization or family-management tools could require payment. Before installing, check the official store listing for the current price, subscription details, supported devices, privacy information, and user reviews so there are no surprises.


